Texas Bond to Indemnify Against Lien
About this form
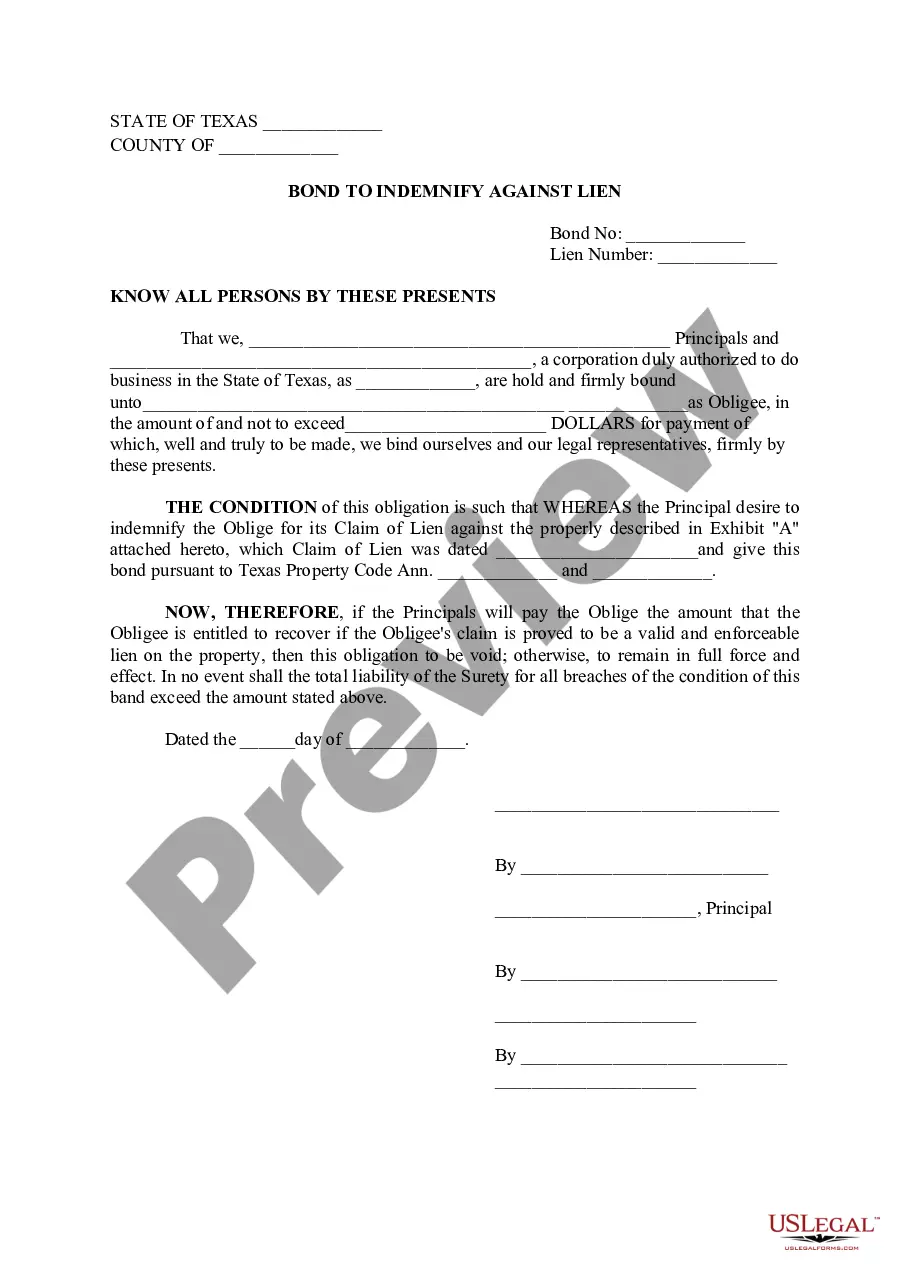
The Bond to Indemnify Against Lien is a legal document used to protect property owners by ensuring payment for valid claims against liens. This bond allows the Principal to satisfy obligations if a lien against their property is proven valid, differentiating it from other forms of lien release by establishing financial responsibility upfront.
Form components explained
- Principal and Obligee details, including names and roles.
- Bond amount indicating the maximum liability.
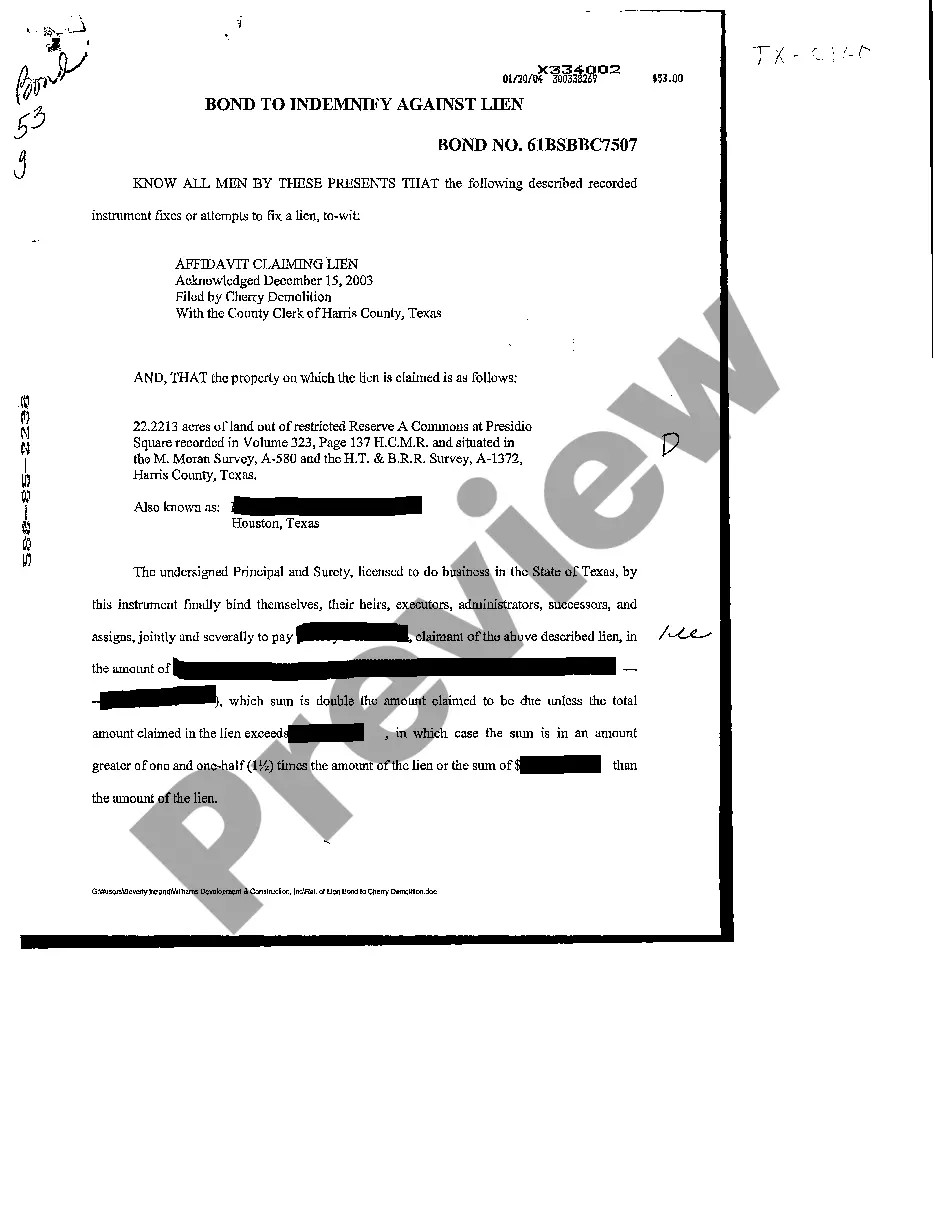
- Claim of Lien details, including description and date.
- Conditions under which the bond is valid.
- Signature lines for all involved parties.

Common use cases
This form is typically used when a property owner wants to release a lien against their property but needs to ensure that they can compensate the lien claimant if the claim is found valid. It is often employed in situations where a property is in dispute or undergoing repairs, and a contractor or supplier has filed a lien for unpaid services or materials.
Who needs this form
- Property owners facing a lien on their property.
- Contractors or suppliers who wish to secure their claims.
- Legal representatives facilitating transactions involving potential liens.
Instructions for completing this form
- Identify and enter the names of the Principal and Obligee.
- Specify the amount of the bond and lien number.
- Provide the details of the lien claim, including property description and date.
- Sign and date the form where indicated, ensuring all parties acknowledge their agreement.
- File the bond with the appropriate local authorities as necessary.
Does this document require notarization?
This form does not typically require notarization unless specified by local law. However, it's advisable to consult legal counsel to ensure compliance with any applicable requirements.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Mistakes to watch out for
- Failing to accurately identify all parties involved in the bond.
- Leaving out crucial information about the lien or property.
- Not obtaining all required signatures before submission.
- Overlooking the need to file the bond with the proper authority.
Benefits of completing this form online
- Convenience of instant download and accessibility.
- Editable templates that allow customization to meet specific needs.
- Reliability with forms prepared by licensed attorneys.
Looking for another form?

Form popularity
FAQ
A Mechanics Lien Release Surety Bond is a surety bond required if the owner's property has had a lien filed against it.The bond guarantees the contractor who placed the lien any payment that is still due to them with interest and cost should they win the case in a court of law.
The process of bonding off a mechanics lien starts after a claimant has filed a mechanics lien. After the claim is made, a general contractor or a property owner can contact a surety bond company to purchase a surety bond that replaces the value of the lien that was filed against the property.
In the event that the contract is breached and payment is not received, an affidavit for mechanics' lien may be filed to place a lien on the project.
When the lien is bonded off, the surety company (or, in the case of a general contractor bonding off the lien itself, the general contractor) is guaranteeing payment of a claim if the claimant prevails in court enforcing the claim.
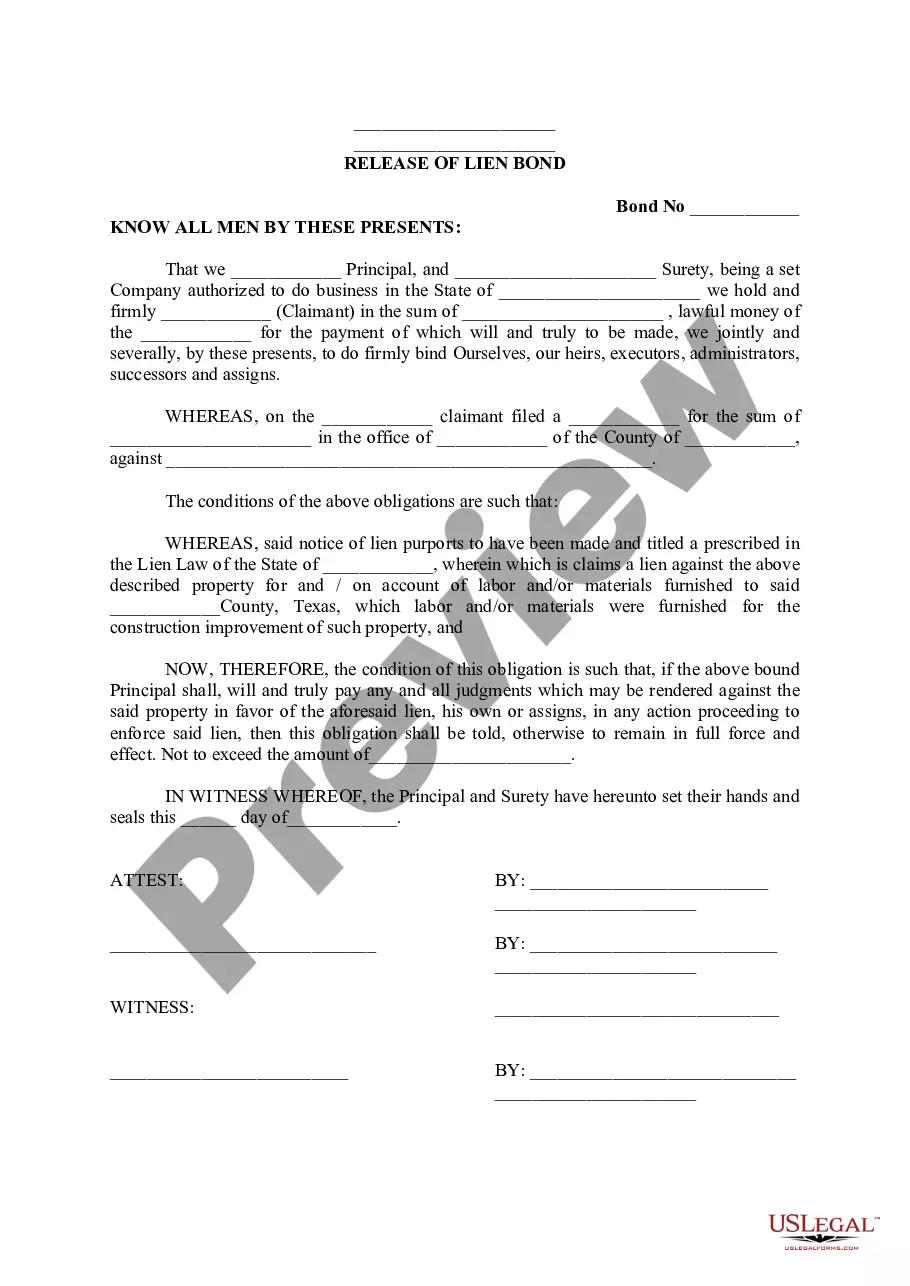
The release of lien bond allows the owner to discharge the mechanic's lien and returns the legal right to sell or deal with the property to the owner. The bond guarantees the contractor who placed the lien any payment that is still due to them with interest and cost should they win the case in a court of law.
The simplest way to prevent liens and ensure that subcontractors and suppliers are paid is to pay with joint checks. This is when both parties endorse the check. Compare the contractor's materials or labor bill to the schedule of payments in your contract and the Preliminary Notices.
A Release of Mechanic's Lien Bond is a type of surety bond that clears the mechanic's lien from the property. These bonds can also be called a Discharge of Mechanic's Lien Bond. By clearing the lien, the owner is free to sell or use the property for other purposes.