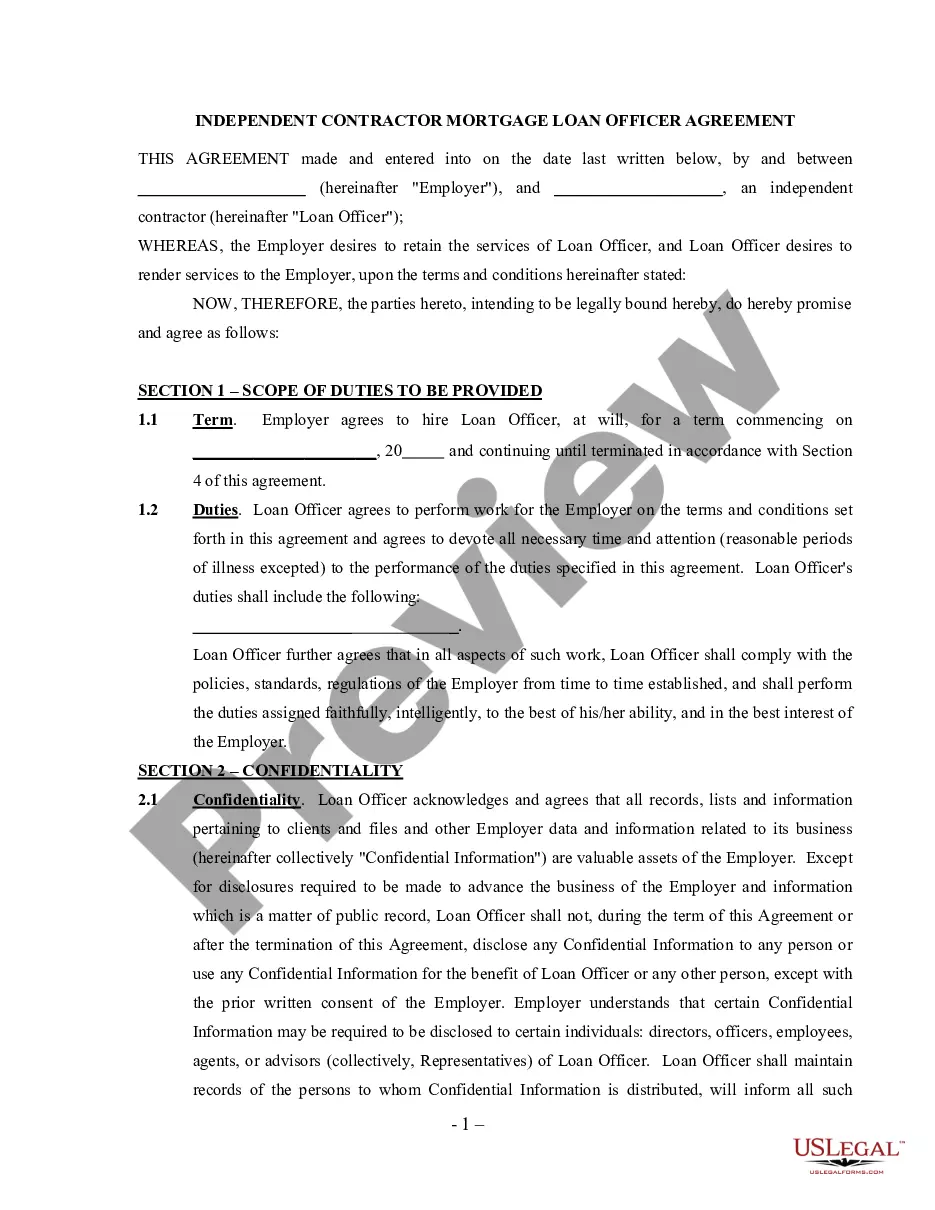
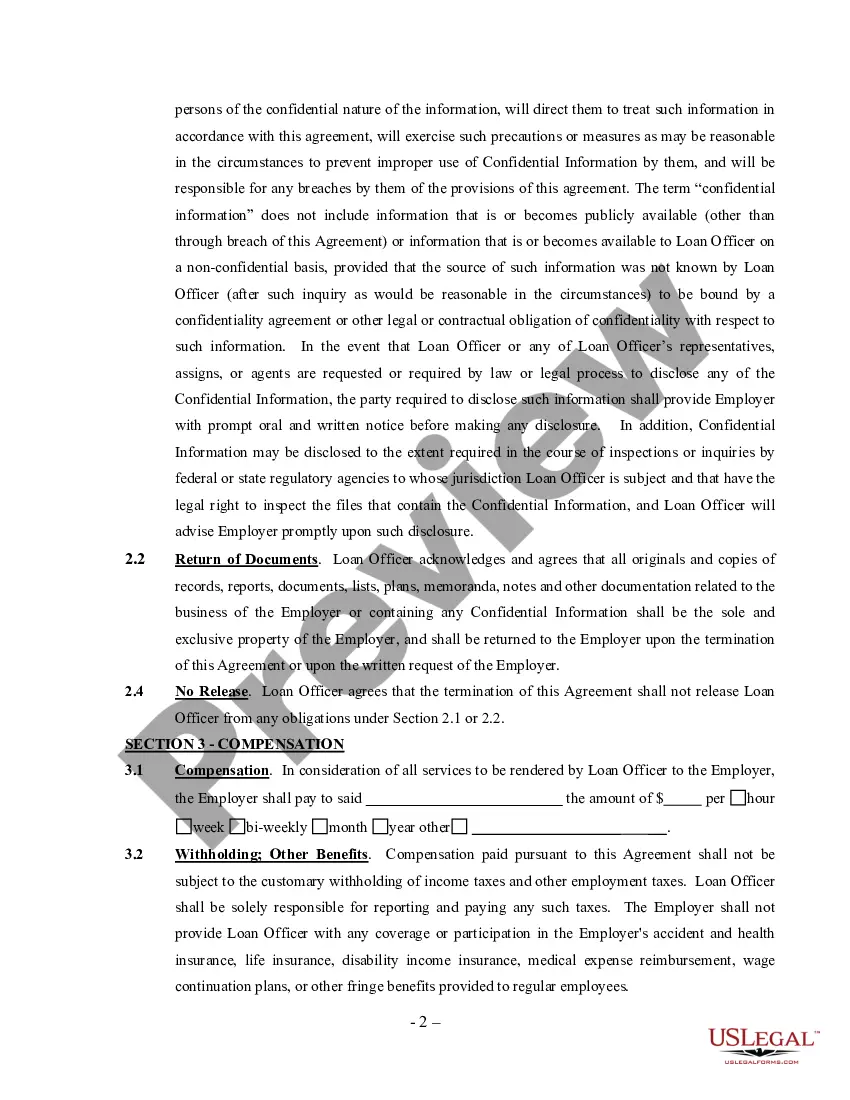
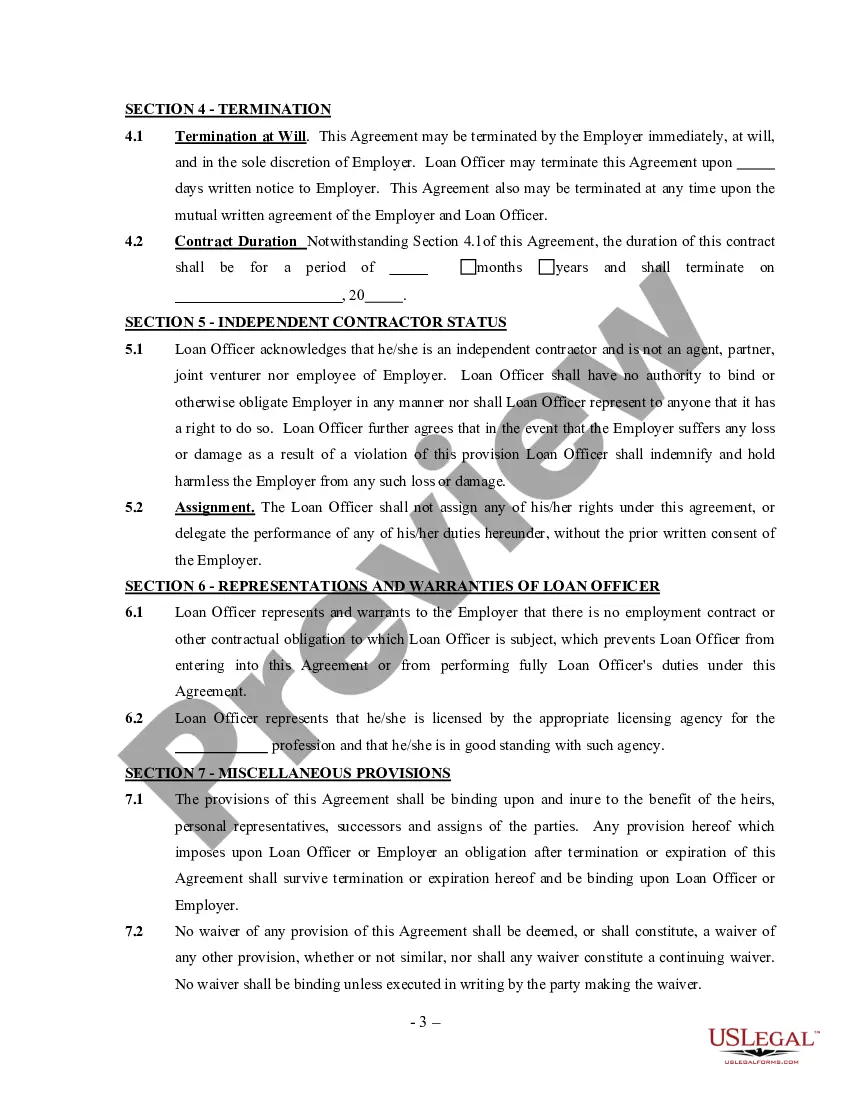
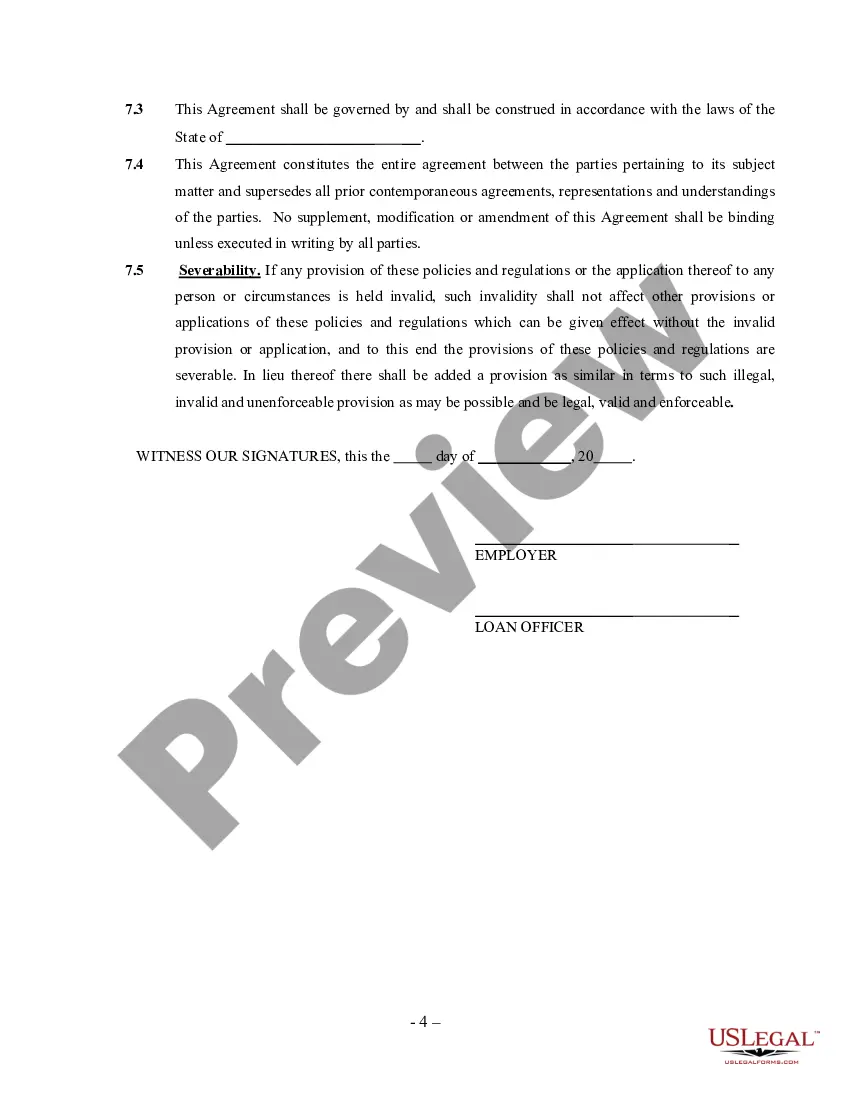
Employer contracts with a mortgage loan officer for hire as an independent contractor to provide services for customers and clients of employer.
Pennsylvania Mortgage Loan Officer Agreement - Self-Employed Independent Contractor
State:
Multi-State
Control #:
US-INDC-145
Format:
Word;
Rich Text
170 downloads
Description
Free preview
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Built-in online Word editor
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Export easily
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
E-sign your document
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
Notarize online 24/7
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
Store your document securely
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
How to fill out Mortgage Loan Officer Agreement - Self-Employed Independent Contractor?
It is possible to invest time on the Internet searching for the authorized papers design that suits the federal and state specifications you need. US Legal Forms gives a large number of authorized forms which can be examined by professionals. It is simple to acquire or printing the Pennsylvania Mortgage Loan Officer Agreement - Self-Employed Independent Contractor from your services.
If you already have a US Legal Forms account, you are able to log in and then click the Obtain option. Afterward, you are able to comprehensive, edit, printing, or indicator the Pennsylvania Mortgage Loan Officer Agreement - Self-Employed Independent Contractor. Each authorized papers design you acquire is the one you have eternally. To obtain one more copy associated with a purchased type, go to the My Forms tab and then click the corresponding option.
Should you use the US Legal Forms website the first time, stick to the easy instructions under:
- Initially, be sure that you have selected the correct papers design for the county/area of your choice. See the type explanation to make sure you have selected the right type. If accessible, make use of the Preview option to check through the papers design also.
- If you would like get one more model of your type, make use of the Lookup industry to get the design that suits you and specifications.
- After you have located the design you want, simply click Get now to continue.
- Select the prices strategy you want, key in your references, and register for a free account on US Legal Forms.
- Total the transaction. You should use your Visa or Mastercard or PayPal account to cover the authorized type.
- Select the file format of your papers and acquire it for your system.
- Make modifications for your papers if necessary. It is possible to comprehensive, edit and indicator and printing Pennsylvania Mortgage Loan Officer Agreement - Self-Employed Independent Contractor.
Obtain and printing a large number of papers themes while using US Legal Forms website, that provides the most important selection of authorized forms. Use expert and condition-distinct themes to deal with your organization or individual requirements.
Form popularity
FAQ
How to Write a Contractor Agreement Outline Services Provided. The contractor agreement should list all services the contractor will provide. ... Document Duration of the Work. Specify the duration of the working relationship. ... Outline Payment Terms. ... Outline Confidentiality Agreement. ... Consult with a Lawyer.
Without a regular paycheck or W-2 statement, it can be harder to prove how much you make, and how reliably you make it. That's why most lenders have stricter rules for self-employed borrowers. Just because you work for yourself doesn't mean you're guaranteed to have a hard time getting a mortgage, however.
At a Glance: 1099 workers can qualify for mortgages, but the process is more complex. Prequalification is the first step, providing an estimate of how much you can borrow. Required documents include immigration documentation, tax returns, proof of income, business financial statements, and more.
If there is no consistent two-year history of doing extra work outside the employer, it won't likely be used. However, if there is a two-year history of both regular employment and working as an independent contractor, the additional 1099 income can be used to help qualify for an FHA loan.
1099 Mortgage Loan Requirements Include: The last six months of 1099 income, less if 1099 income is from most recent employer. Documentation of year-to-date income. 680 minimum credit score. Minimum 10% down with mortgage insurance approval.
Employees (and employers) are all subject to federal and state wage hour rules. The CFPB refers to Mortgagee Letter 2006-30 and affirms it will follow HUD's rule, which is to say that Mortgage Brokers and Mortgage lenders must pay their loan officers W-2 and that 1099 is illegal under HUD/CFPB Guidelines.
Since 1099 mortgage loans are perceived as riskier for the lending institutions than traditional mortgages, lenders often require would-be borrowers to have higher credit scores (at least 620 and over) and lower debt-to-income ratios than typical mortgages (typically 50% or less DTI.)
To calculate your self-employment income for a mortgage application, follow these simple steps: Find your net income from Schedule C on your tax returns for the two most recent years. Add the two figures together. Divide the result by 24.