Maine Clerk's Certificate of Foreclosure
About this form
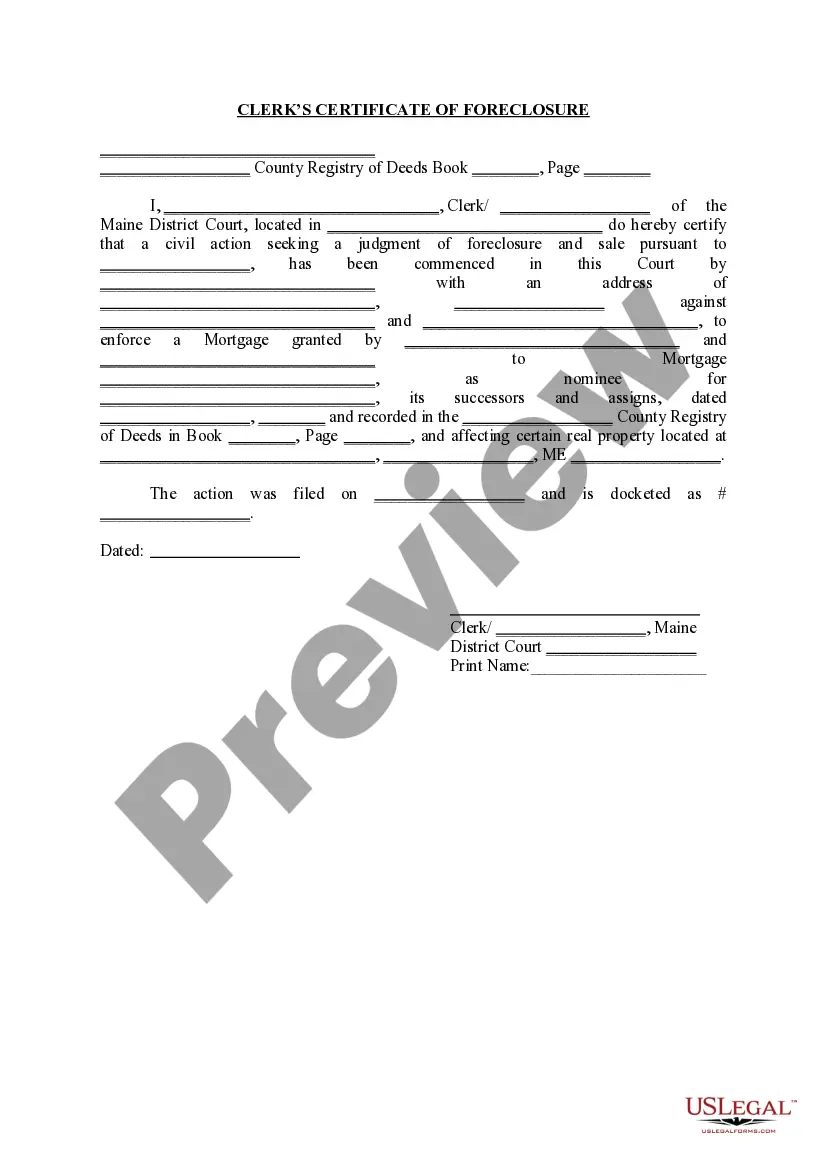
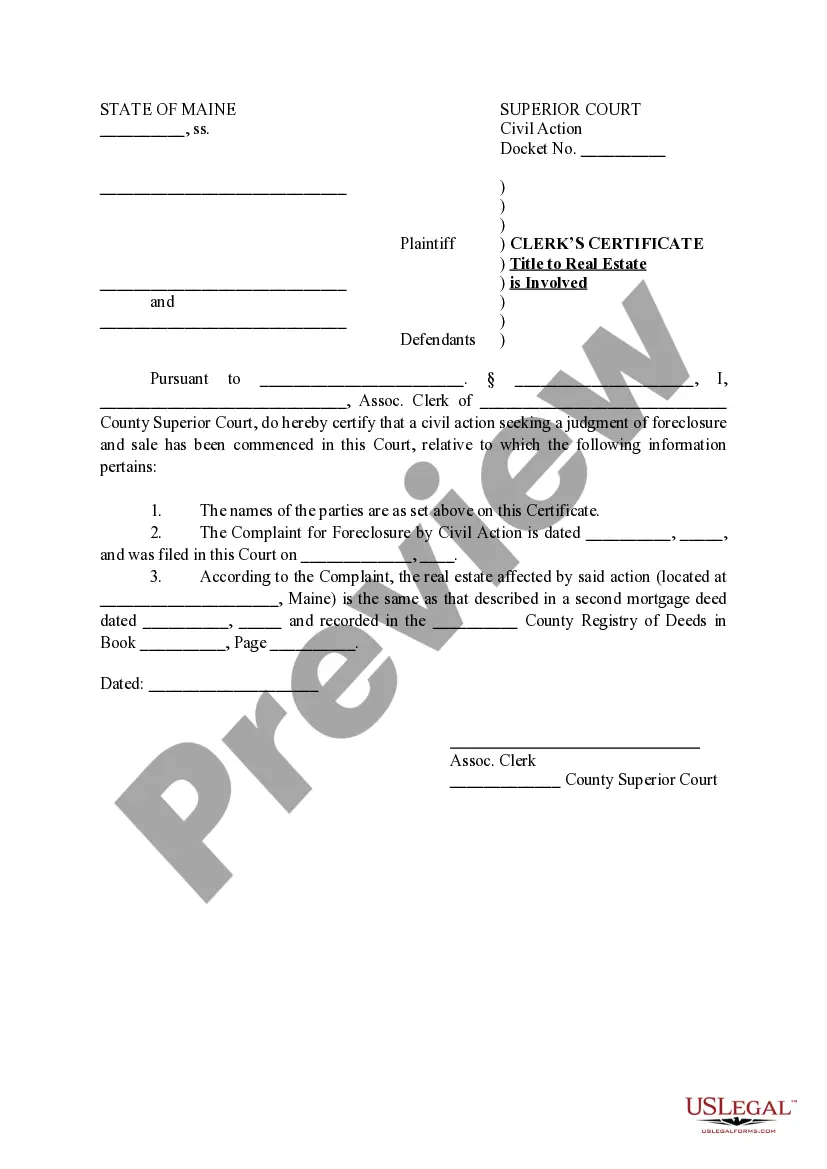
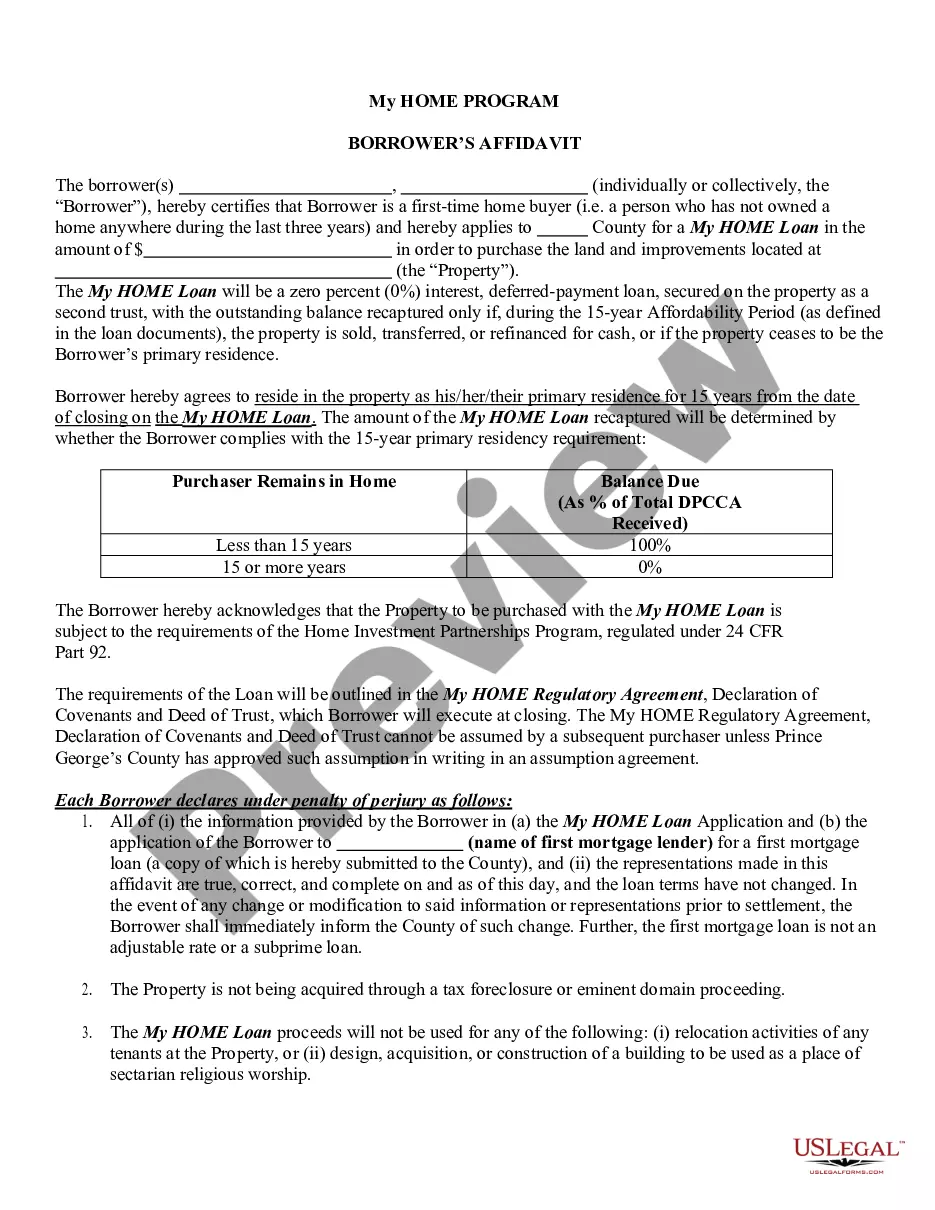
The Clerk's Certificate of Foreclosure is an official document issued by the clerk of court, certifying that a court action for foreclosure has been filed. This form is essential for legal proceedings related to property foreclosure and serves as proof of the filing status, differentiating it from other documents related to mortgage actions.
Main sections of this form
- Clerk's certification of the civil action seeking foreclosure and sale.
- Case details including docket number and filing date.
- Information about the mortgage parties and property affected.
- Specifications of the mortgage details, such as dates and registry information.
- Signature and name of the court clerk certifying the information.
When to use this form
This form is used in situations where a lender initiates foreclosure proceedings against a property owner. It is required to document the initiation of legal action in court and serves as a formal notice of the filing to all parties involved. Use this form when you need to prove that a foreclosure case has been filed in order to proceed with legal actions pertaining to the property.
Intended users of this form
- Mortgage lenders initiating foreclosure proceedings.
- Property owners facing foreclosure who need to verify the court filing.
- Attorneys representing either party in foreclosure cases.
- Real estate professionals involved in the foreclosure process.
How to prepare this document
- Identify the relevant court jurisdiction and fill in the county name.
- Provide the names and addresses of the parties involved in the foreclosure.
- Enter the details of the mortgage, including dates, book, and page number in the registry.
- Include the docket number and filing date of the court action.
- Sign and print your name in the designated section as the clerk of court.
Does this document require notarization?
This form does not typically require notarization unless specified by local law. Always verify local regulations to ensure compliance.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Typical mistakes to avoid
- Failing to include accurate information regarding the parties involved.
- Omitting the docket number or filing date of the court action.
- Not providing complete mortgage details, such as book and page numbers from the registry.
- Incorrectly identifying the court jurisdiction, leading to legal complications.
Why use this form online
- Convenient access to the form for quick download and completion.
- Editable fields for easier customization to your specific situation.
- Reliable templates created by licensed attorneys to ensure legal compliance.
- Secure storage and retrieval options to keep your documents organized.
Quick recap
- The Clerk's Certificate of Foreclosure certifies the initiation of a foreclosure action.
- Accurate completion is crucial to avoid legal issues.
- This form is essential for both lenders and property owners involved in foreclosure cases.
- Available for download with easy-to-follow instructions online.
Looking for another form?

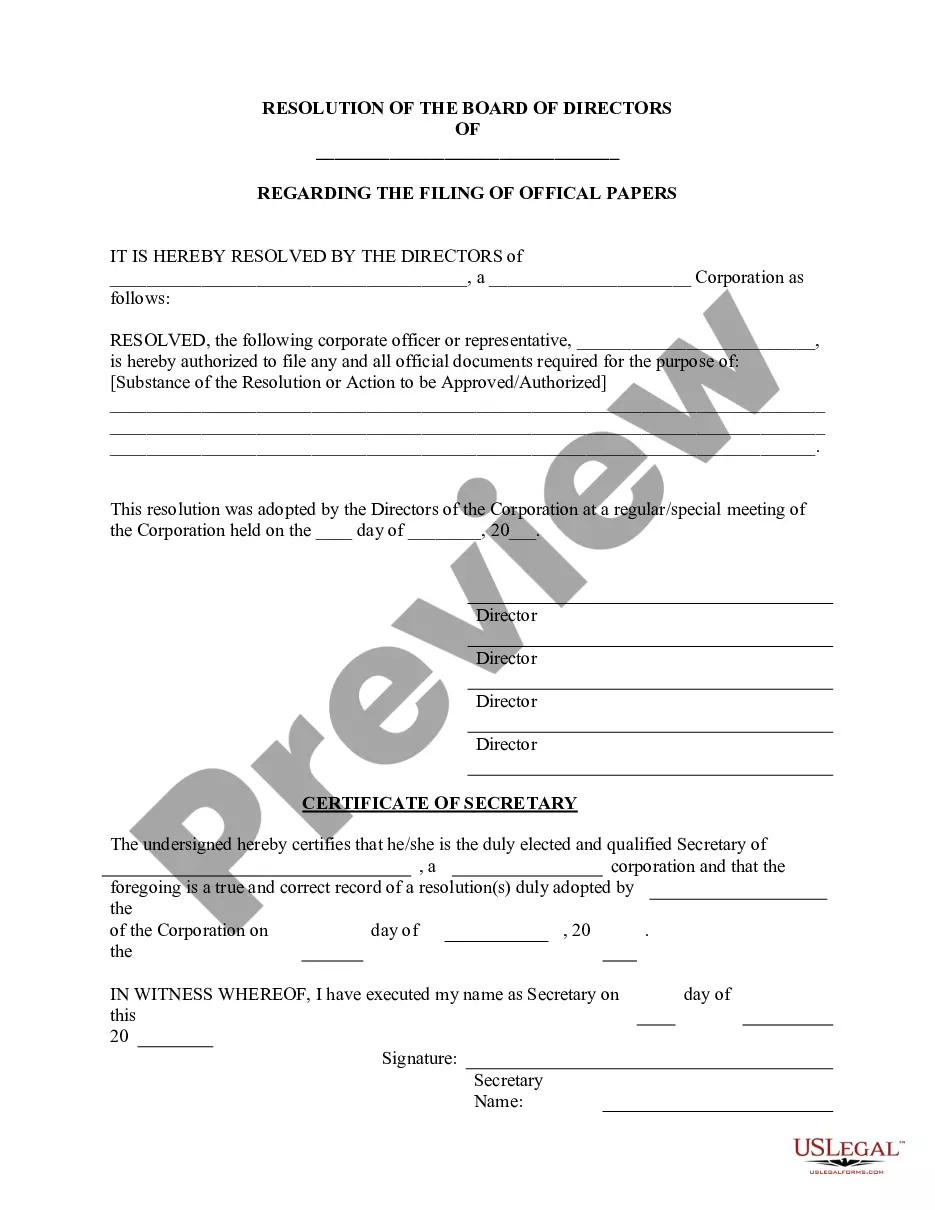
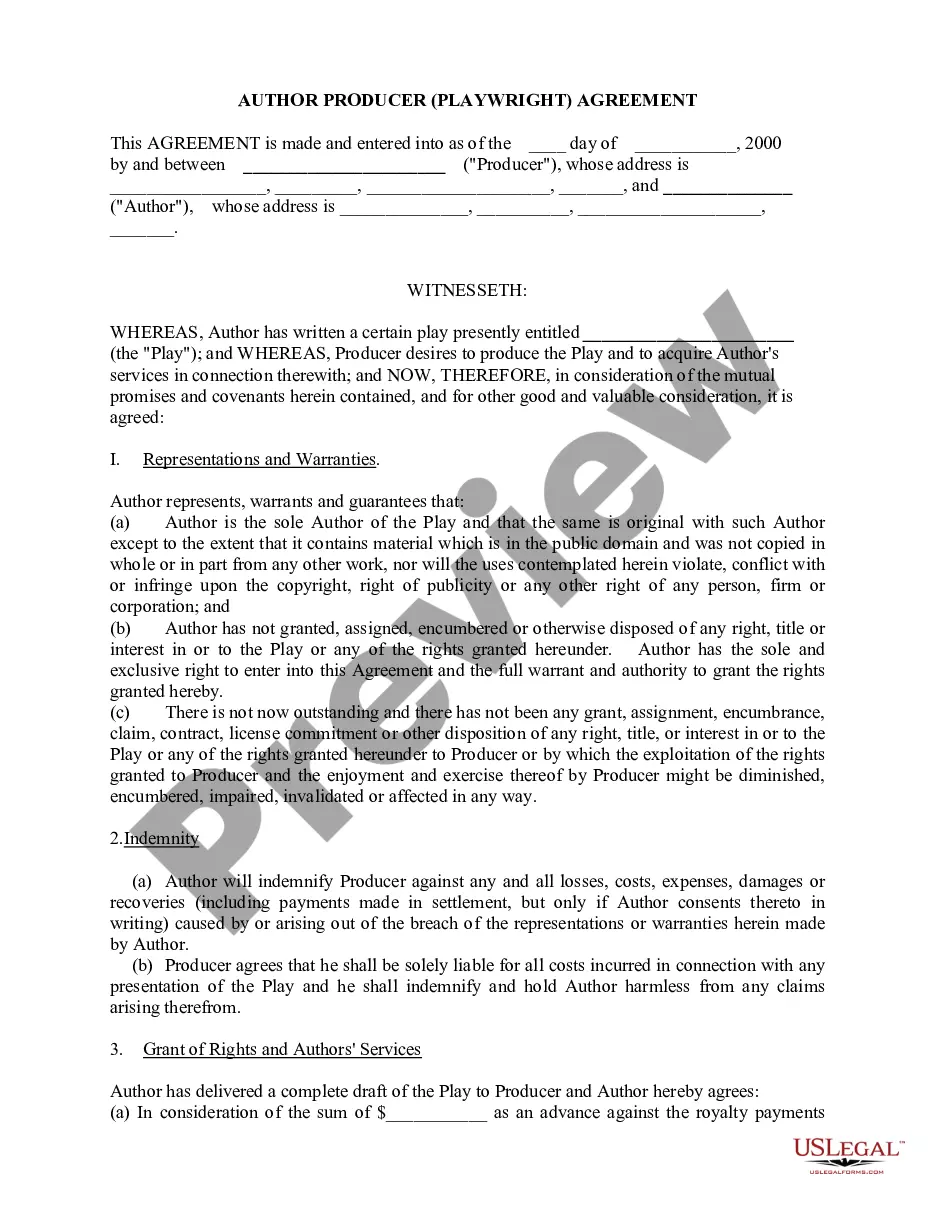
Form popularity
FAQ
It takes a minimum of 120 days to complete a foreclosure in California; in other states, twelve or more months may pass before you're required to leave your home.
Foreclosures are generally judicial in the following states: Connecticut, Delaware, District of Columbia (sometimes), Florida, Hawaii, Illinois, Indiana, Iowa, Kansas, Kentucky, Louisiana (executory proceeding), Maine, Nebraska (sometimes), New Jersey, New Mexico, New York, North Dakota, Ohio, Oklahoma (if the
The auction notice, or Notice of Sale, is your final notice that the lender intends to sell the property at auction. The county prints the location, time and date of the trustee's auction on the Notice of Sale. It also contains the name and contact information for the trustee in charge of the sale.
In Maine, lenders may foreclose on mortgages in default by using either a judicial or strict foreclosure process. Although Maine allows lenders to pursue foreclosure by judicial methods, which involves filing a lawsuit to obtain a court order to foreclose, it is only used in special circumstances.
Judicial foreclosure involves filing a lawsuit to get a court order to sell the home (foreclose). It is used when there is no power-of-sale clause in the mortgage or deed of trust. Generally, after the court orders the sale of your home, it will be auctioned off to the highest bidder.
You can stop the foreclosure process by informing your lender that you will pay off the default amount and extra fees. Your lender would prefer to have the money much more than they would have your home, so unless there are extenuating circumstances, this should work.
Foreclosures can take a long time because lenders and servicers must comply with the requirements under these laws. Mediation laws. Some states, cities, and municipalities have passed foreclosure mediation laws that can delay the foreclosure process. Mortgage servicing laws changed in 2014.
Generally, a homeowner has to be at least 120 days delinquent before a mortgage servicer starts a foreclosure. Applying for a foreclosure avoidance option, called loss mitigation, might delay the start date even further.
The Notice of Default starts the official foreclosure process. This notice is issued 30 days after the fourth missed monthly payment. From this point onwards, the borrower will have 2 to 3 months, depending on state law, to reinstate the loan and stop the foreclosure process.