Life Insurance Trust Have With Diabetes
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
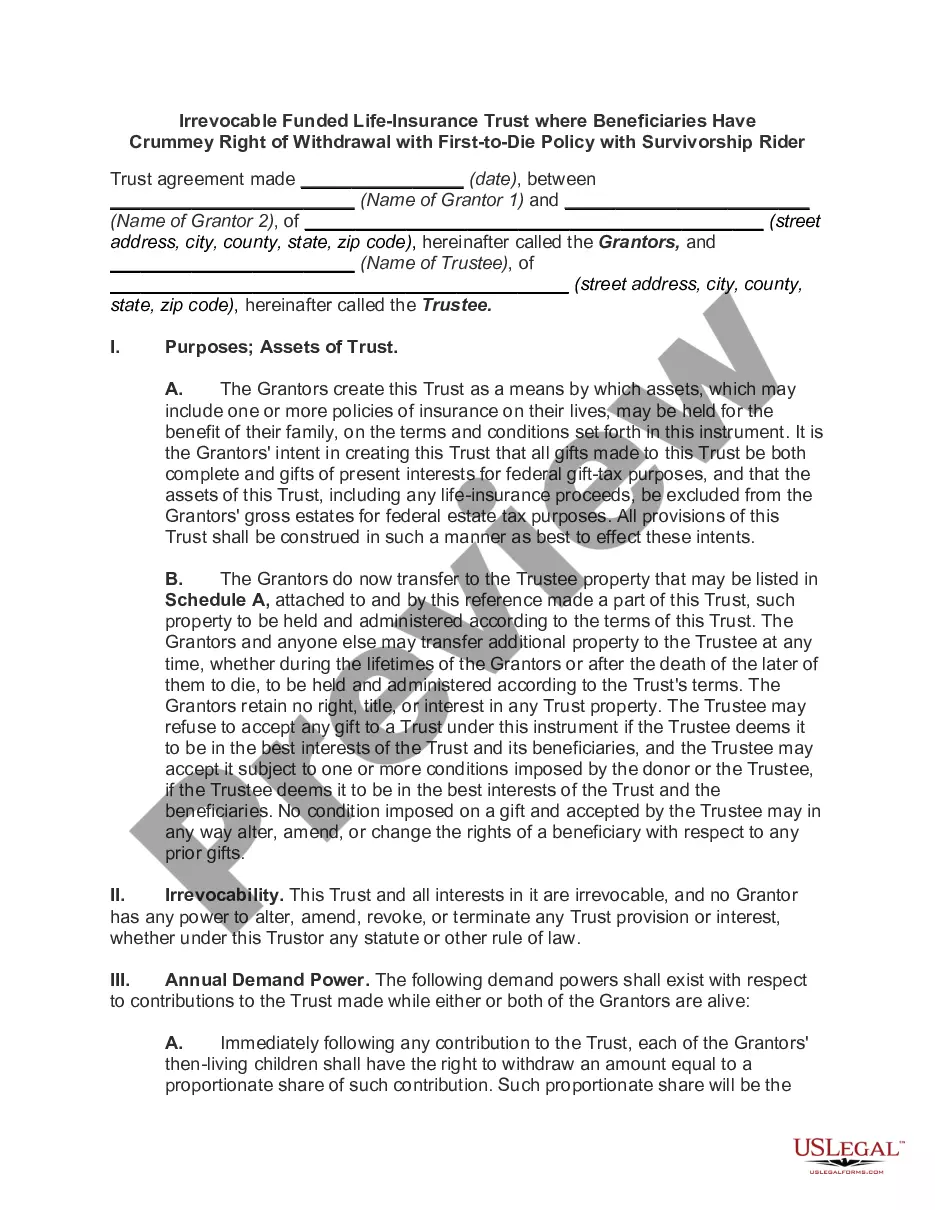
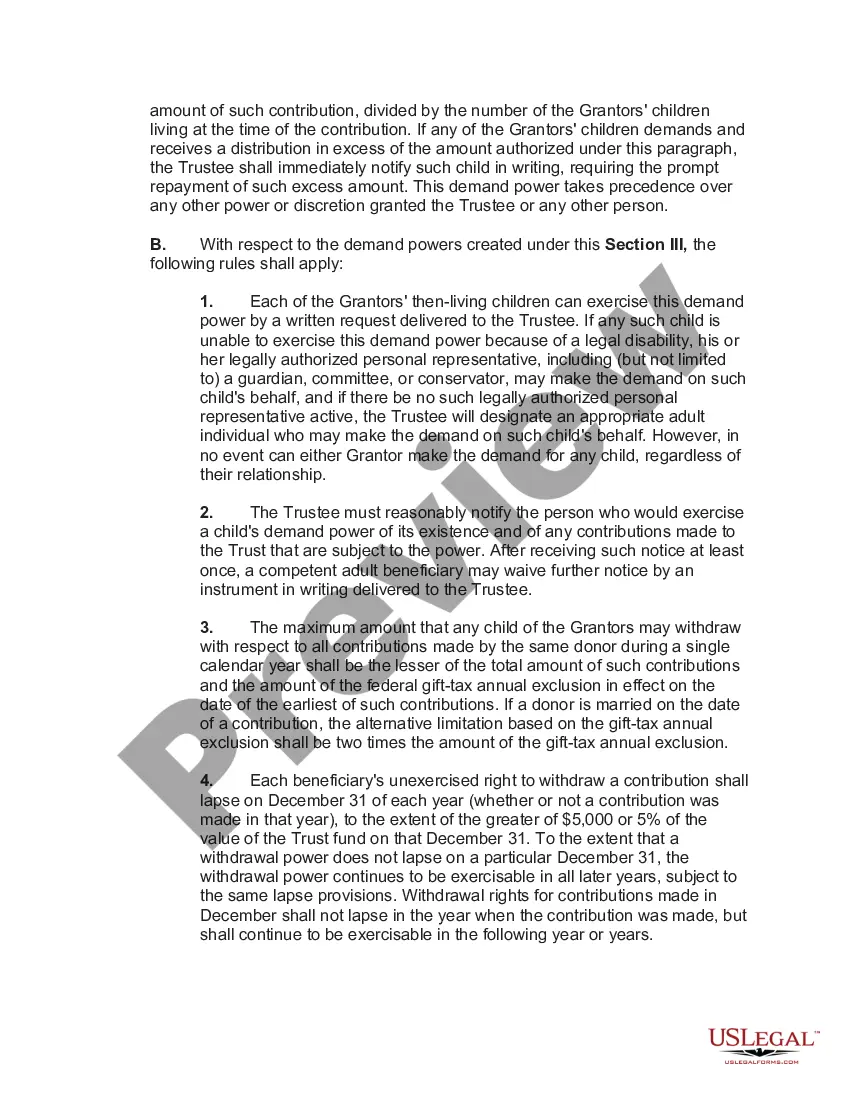
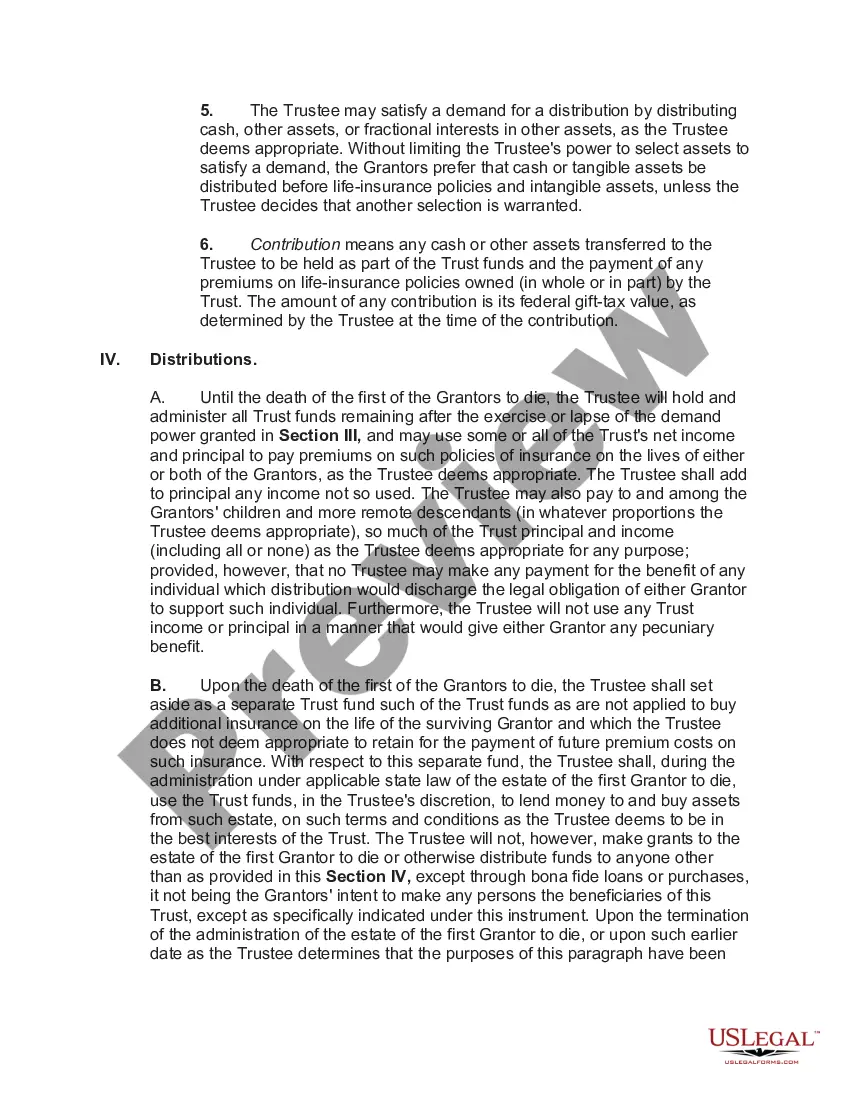
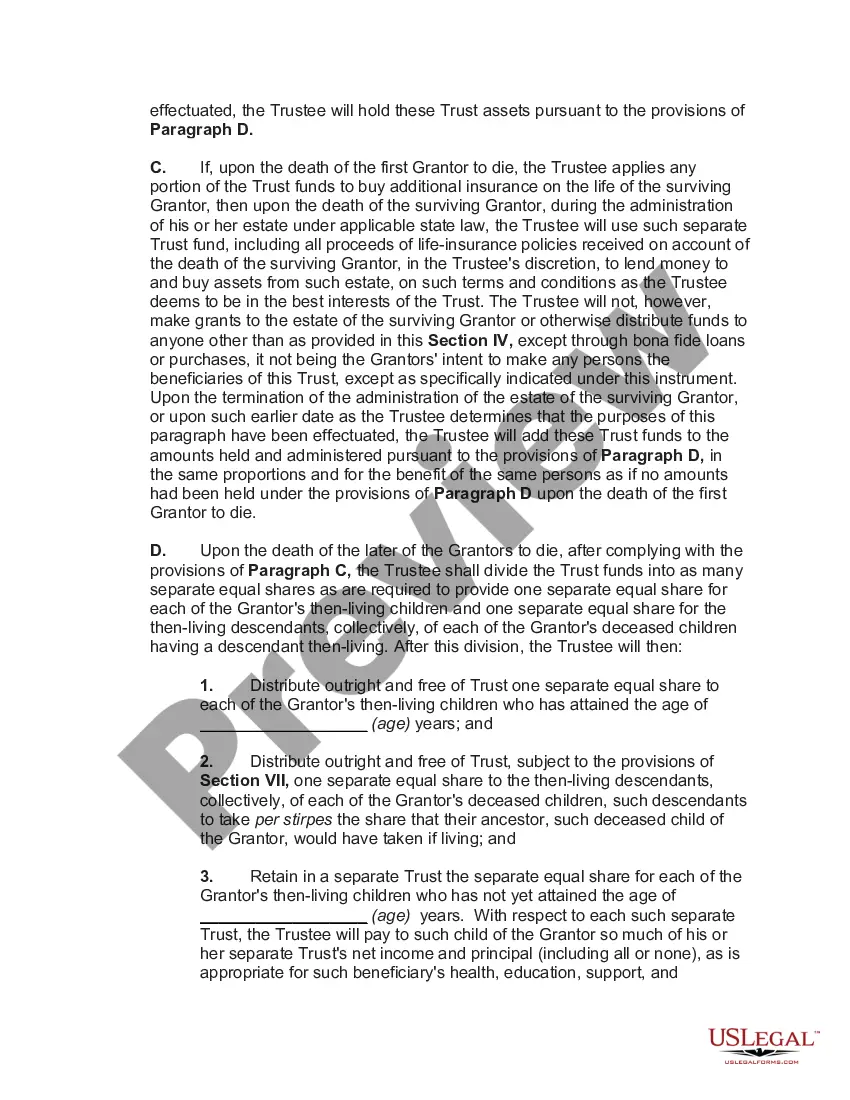
How to fill out Irrevocable Funded Life Insurance Trust Where Beneficiaries Have Crummey Right Of Withdrawal With First To Die Policy With Survivorship Rider?
It’s clear that you cannot become a legal specialist instantly, nor can you comprehend how to swiftly draft a Life Insurance Trust Have With Diabetes without possessing a specialized education.
Compiling legal documents is a lengthy process that necessitates specific training and abilities. Therefore, why not entrust the preparation of the Life Insurance Trust Have With Diabetes to the professionals.
With US Legal Forms, one of the most comprehensive legal document libraries, you can discover everything from court documents to templates for in-office correspondence. We understand the importance of compliance and adherence to federal and state laws and regulations.
You can access your forms again from the My documents tab at any time. If you’re an existing client, you can simply Log In, and find and download the template from the same tab.
Regardless of the intent of your forms—whether they are financial and legal or personal—our website has everything you need. Try US Legal Forms today!
- Begin your search with the search bar located at the top of the webpage.
- Preview it (if this feature is available) and read the accompanying description to determine if Life Insurance Trust Have With Diabetes is what you’re looking for.
- Start your search again if you require another form.
- Create a free account and select a subscription plan to acquire the template.
- Select Buy now. Once the payment is finalized, you can obtain the Life Insurance Trust Have With Diabetes, complete it, print it, and send or submit it by post to the relevant individuals or entities.
Form popularity
FAQ
Yes, you can obtain life insurance even with diabetes. Many companies offer policies designed specifically for individuals managing this condition. While it might be beneficial to work with an agent knowledgeable about diabetes-related underwriting, a life insurance trust can play a key role in safeguarding your family's future. Understanding your options will empower you to secure the coverage you need.
Yes, many life insurance policies cover diabetes. Insurers assess your health history, including diabetes management, to determine coverage options. They consider your treatment regimen, compliance, and overall health when evaluating your application. Therefore, a life insurance trust can be beneficial for those with diabetes, as it may help ensure financial security for your loved ones.
Yes, many people with diabetes can qualify for life insurance. For people with well-managed conditions who are generally healthy, it's even possible to find affordable life insurance for diabetics.
People with diabetes can take out most types of life insurance policies; their policies may just cost more. When applying for life insurance as a diabetic, there are two big things to consider: the type of life insurance policy and the type of insurance underwriting.
Diabetics can qualify for a whole life insurance policy, but the type of coverage and the cost will depend on the individual's overall health, the management of their illness, and other factors. In general, diabetics can expect to pay more than a health individual for a whole life insurance policy.
If you've been diagnosed with Type 1 or Type 2 diabetes, you should tell the insurer during the application. They'll use this information to help calculate your quote. People with diabetes often pay more for life insurance. This is because it is a pre-existing condition and poses a wide variety of health risks.
If your A1C is above 9.0, unfortunately, fully underwritten term life insurance is unavailable. Life insurance companies will postpone or decline your application until your A1C falls below the 9.0 mark. See the chart below for average blood sugar to A1C comparisons.