Termination Lease Form Agreement With Equipment
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
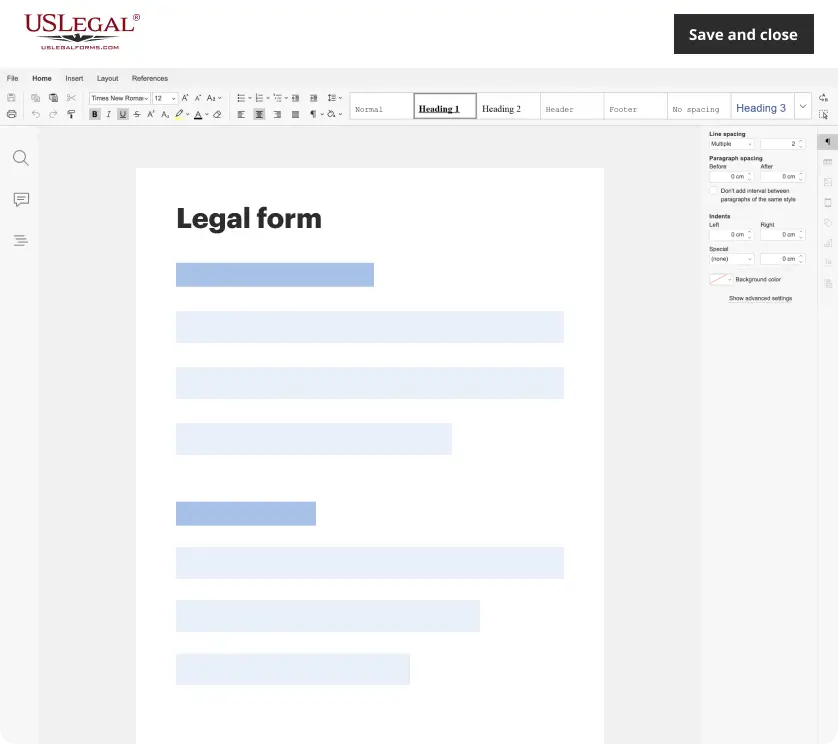
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
How to fill out Sample Letter For Termination Of Lease From Landlord To Tenant?
- Log in to your US Legal Forms account if you're a returning user. Check your subscription status and ensure it’s currently valid to access the templates.
- If you're new to the service, start by previewing the available forms. Compare options to find a termination lease form agreement that meets your needs and complies with local legal requirements.
- If the first form doesn’t suit your needs, use the search feature to explore other templates until you find the right one.
- Once you identify the suitable document, click the Buy Now button and select a subscription plan that best fits your preferences.
- Complete your purchase by entering your payment information. You can opt to use a credit card or your PayPal account.
- After payment, download your form and save it to your device. You can access this document anytime through the My Forms section of your account.
By following these simple steps, you ensure that your termination lease form agreement is available at your fingertips and ready for use.
When you choose US Legal Forms, you're not only gaining access to thousands of legal documents but also benefiting from expert assistance for accurate completion. Start your legal processes the easy way today!
Form popularity
FAQ
The journal entry for a lease typically involves recognizing the leased asset and corresponding liability when the lease begins. The termination lease form agreement with equipment will guide you in determining the amounts to record. As payments are made, you'll create entries to reflect lease expenses and reduce the liability incrementally.
A lease is generally both an asset and a liability. The equipment leased is considered an asset on your balance sheet, while the obligation to make future payments represents a liability. Understanding how to manage these through a termination lease form agreement with equipment is crucial for accurate financial reporting.
Recording a lease on equipment involves identifying the asset value at the start of the lease. Then, recognize the lease liability based on future payments outlined in the termination lease form agreement with equipment. Regularly update your accounts to show the asset depreciation and expense recognition as you use the equipment.
To record an equipment lease in accounting, recognize the leased asset and corresponding liability on your balance sheet. Use the termination lease form agreement with equipment to determine the lease obligation's present value. Make routine journal entries to reflect rent expenses throughout the lease term accurately.
To write a lease agreement for equipment, start by outlining the parties involved and the equipment being leased. Include the lease duration, payment terms, and maintenance responsibilities. Clearly articulate the terms regarding the termination lease form agreement with equipment to avoid misunderstandings down the line.
In a finance lease, the lessor retains ownership of the equipment during the lease term, as specified in your termination lease form agreement with equipment. However, you, as the lessee, gain control of the asset and can utilize it as if you own it. At the end of the lease, you typically have the option to buy the equipment, which can be a beneficial arrangement for your business.
Yes, depreciating leased equipment generally depends on the type of lease outlined in your termination lease form agreement with equipment. In a finance lease, you may be able to claim depreciation as though you own the asset, which can provide tax benefits. However, in an operating lease, you typically do not record depreciation, as the equipment does not appear on your balance sheet.
A termination clause in a termination lease form agreement with equipment outlines the conditions under which either party can terminate the lease early. For example, a clause may specify that termination can occur if one party fails to meet payment obligations or if the equipment is deemed unusable. This clause can provide both parties with a clear understanding of their rights and responsibilities regarding the lease.
When you enter into a termination lease form agreement with equipment, the way you account for the leased equipment may depend on various factors, including the lease type. In general, operating leases may not show the equipment as an asset on your balance sheet, while finance leases typically require capitalization of the asset. It's important to consult with your accounting professional to understand how this impacts your financial statements.
To write off leased equipment effectively, refer to your termination lease form agreement with equipment for guidance. You usually have the option to deduct monthly payment amounts as they occur. Keeping accurate records of your lease payments and related expenses is key to aligning with tax requirements. A user-friendly platform like uslegalforms can simplify the process, helping you to manage your documents efficiently.