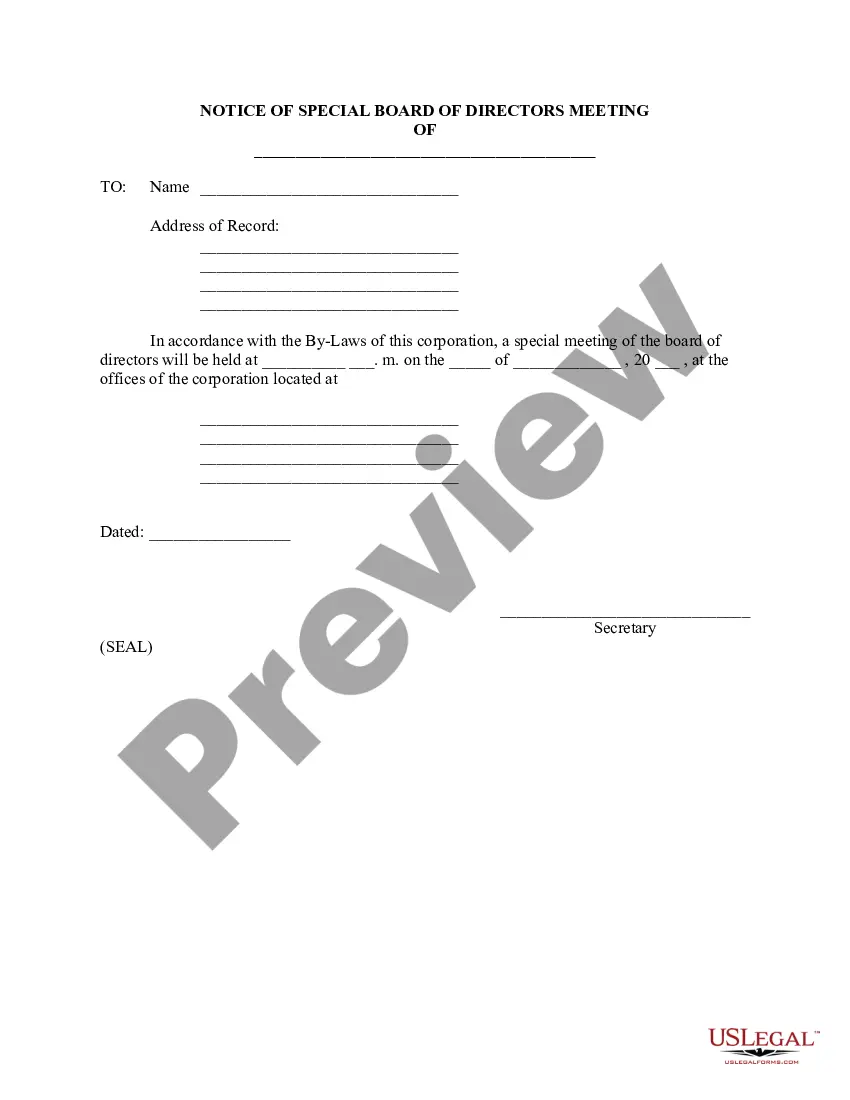
Sell Of Partnership Interest In Chicago
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
Examples of Partner's Interest in a Partnership For example, if the partnership earns $100,000 in profit, each partner receives $50,000. Variable Interest: In Smith & Co. v. Johnson, Partner A has a 60% interest and Partner B has a 40% interest based on their initial capital contributions.
Gain Realized Generally, a partner selling his partnership interest recognizes capital gain or loss on the sale. The amount of the gain or loss recognized is the difference between the amount realized and the partner's adjusted tax basis in his partnership interest.
If a partnership holds IRC 751(a) property at the time of the sale, the partner recognizes gain or loss from its share of IRC 751(a) assets. The ordinary gain or loss is subtracted from the total gain or loss. The result is the partner's capital gain or loss from the sale.
The best way to sell your limited partnership interest may lie in finding an experienced broker or advisor who can help you to identify potential buyers and guide you through any negotiations that may arise.
If a partnership holds IRC 751(a) property at the time of the sale, the partner recognizes gain or loss from its share of IRC 751(a) assets. The ordinary gain or loss is subtracted from the total gain or loss. The result is the partner's capital gain or loss from the sale.
The best way to sell your limited partnership interest may lie in finding an experienced broker or advisor who can help you to identify potential buyers and guide you through any negotiations that may arise.
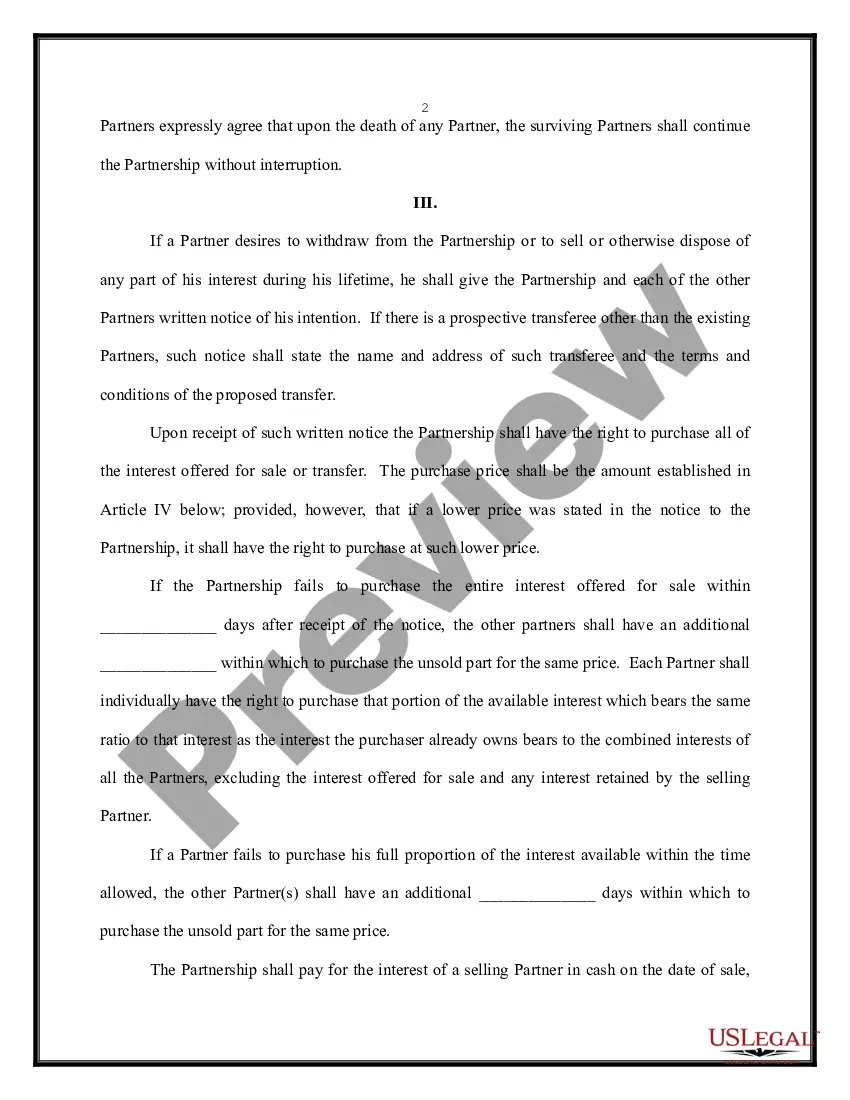
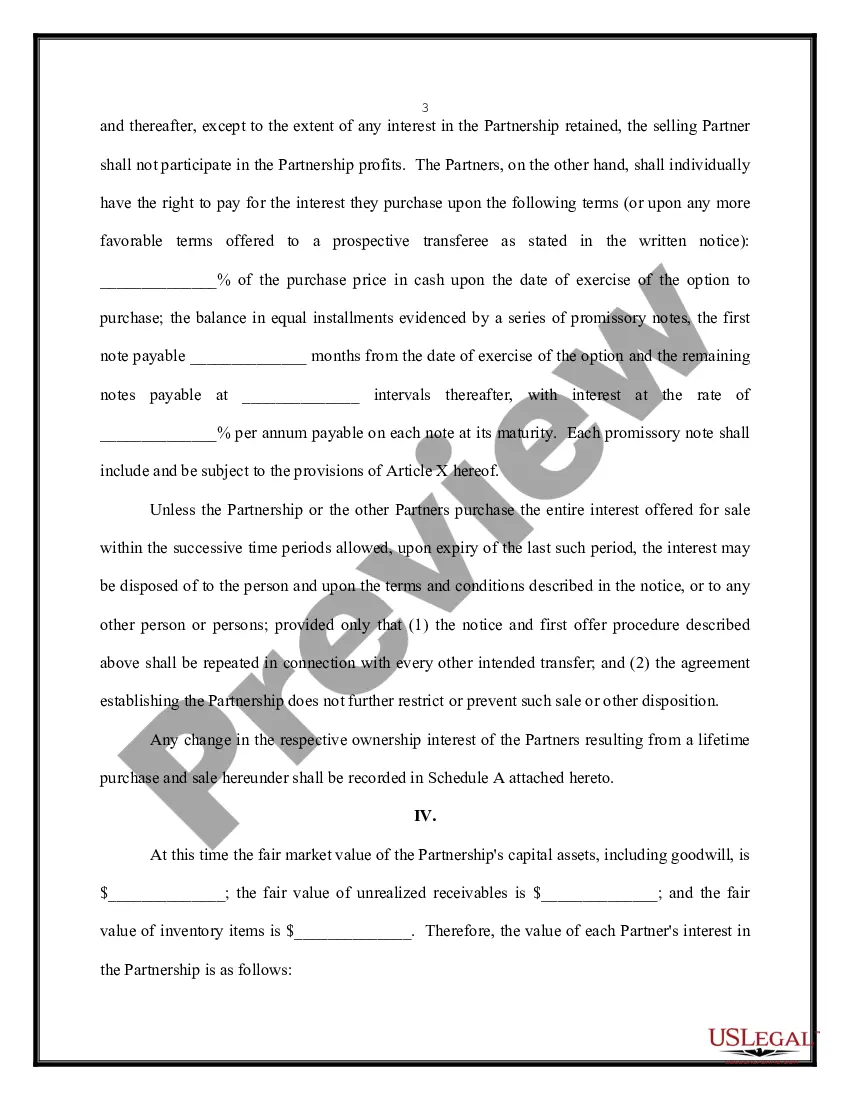
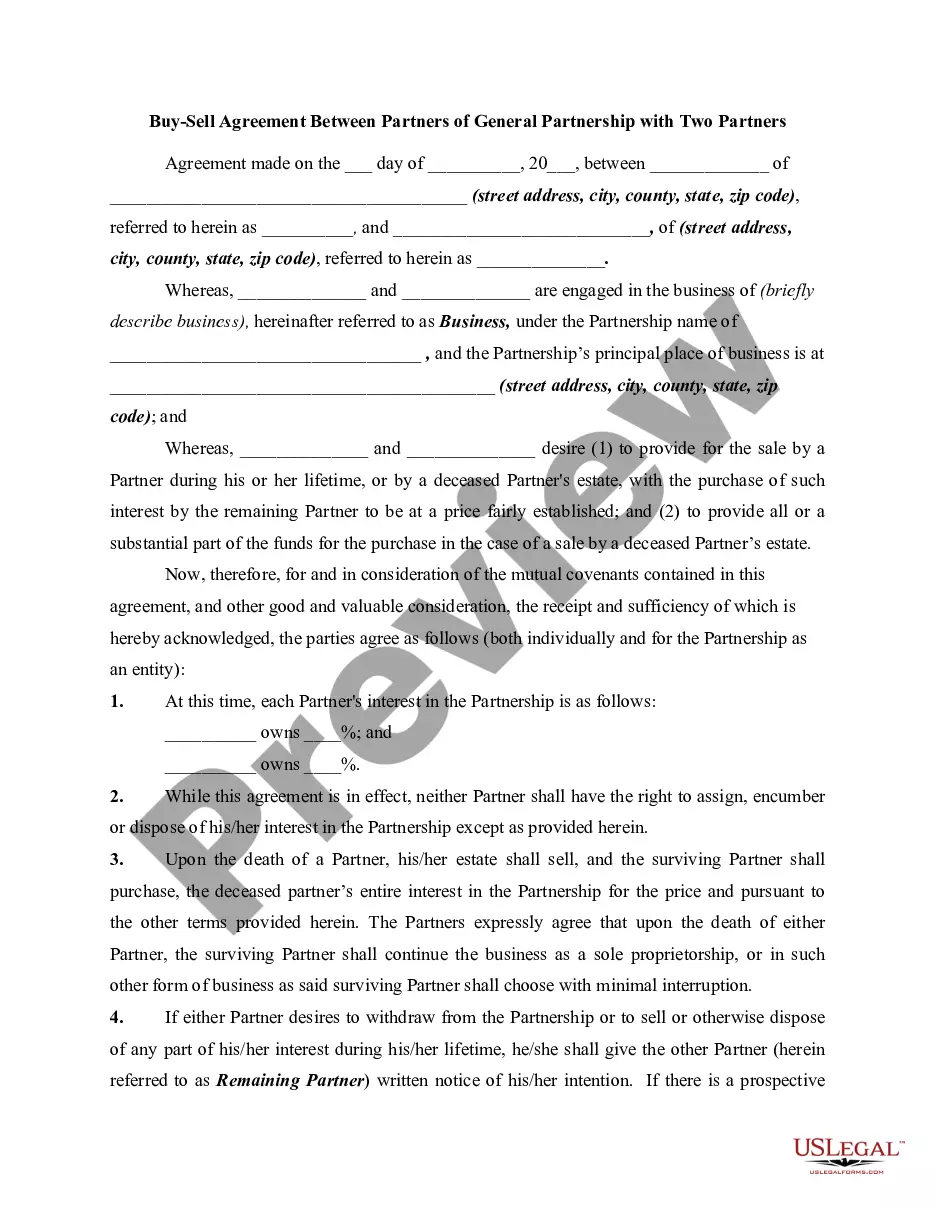
The Partnership Buyout Agreement Your path to an ownership sale will be simpler if you created a clear and thorough partnership buyout agreement when you started your company. The agreement should discuss what might lead to one of the partners wanting to sell her share and state the terms and timing that would apply.
Sale of a partnership interest generally gives the selling partner capital gain. Section 751, however, recharacterizes a portion of the amount realized as ordinary income to the partner, at times even in the absence of realized gain.
The best way to sell your limited partnership interest may lie in finding an experienced broker or advisor who can help you to identify potential buyers and guide you through any negotiations that may arise.