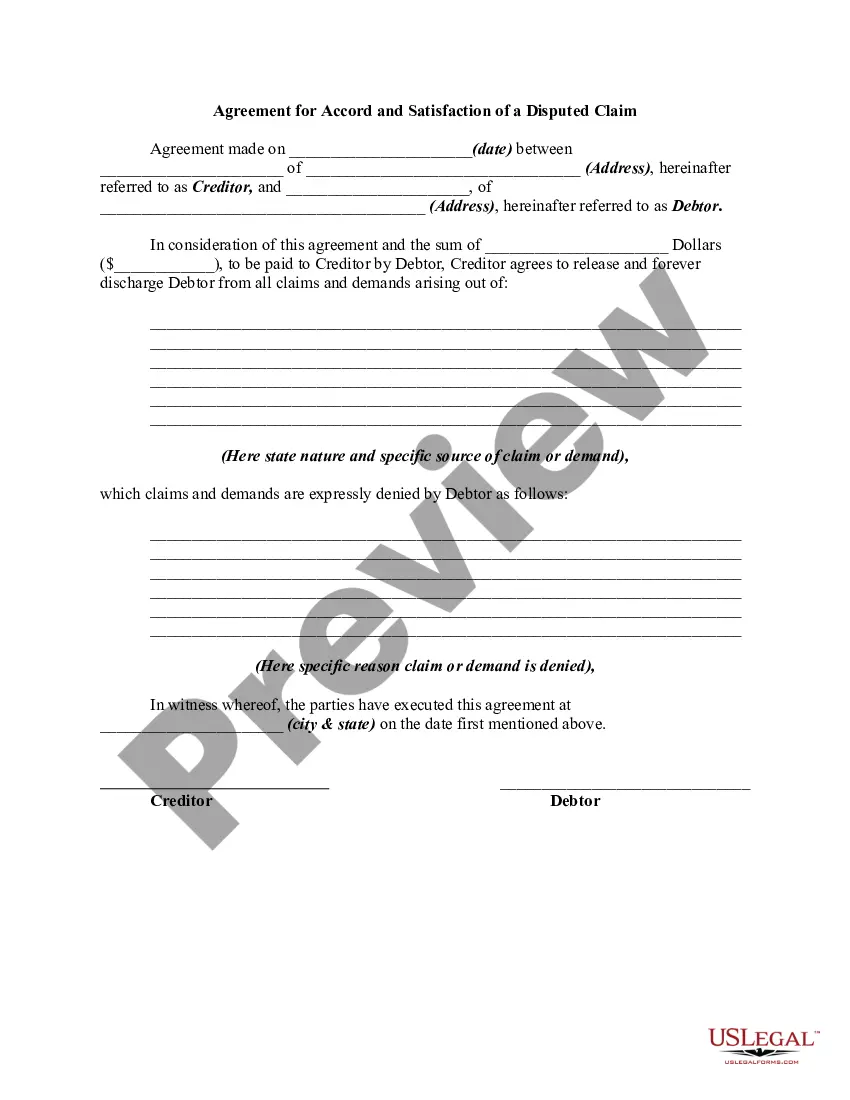
Denied Claim Agreement For Service In San Jose
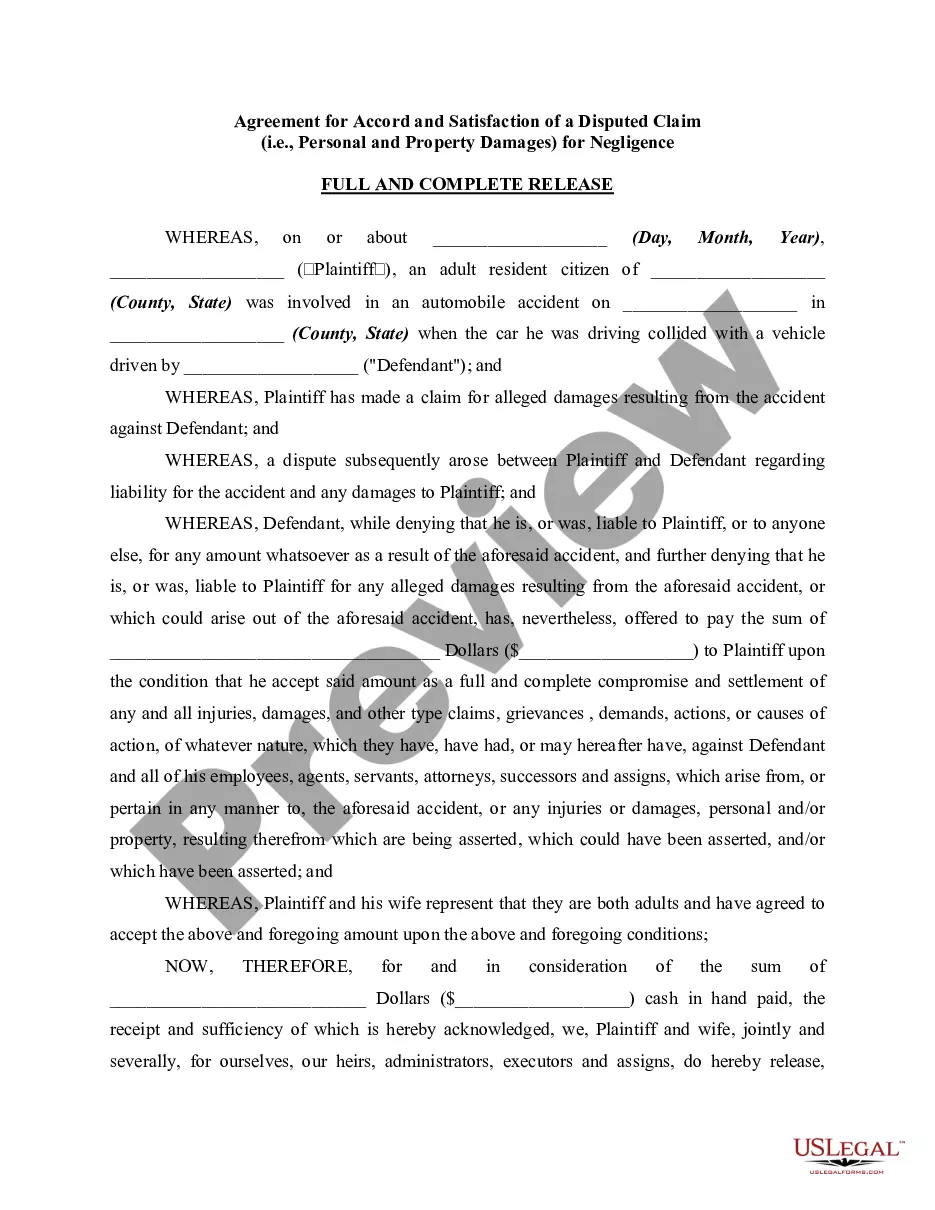
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
If an insurance company denies a request or claim for medical treatment, insureds have the right to appeal to the company and also to then ask the Department of Insurance to review the denial. These actions often succeed in obtaining needed medical treatment, so a denial by an insurer is not the final word.
Step 1: Find out the reason for the denial of your claim. Step 2: Once you know why your claim was rejected, make the necessary amends if possible. Step 3: File the health insurance claim again after confirming with the insurer that the additional information provided is adequate.
Be persistent Your appeal should include an explanation of your reconsideration request, along with any necessary supporting documentation, such as a copy of the claim in question and copies of earlier communication to the company about the matter.
If an insurance company denies a request or claim for medical treatment, insureds have the right to appeal to the company and also to then ask the Department of Insurance to review the denial. These actions often succeed in obtaining needed medical treatment, so a denial by an insurer is not the final word.
Step 1: Find out the reason for the denial of your claim. Step 2: Once you know why your claim was rejected, make the necessary amends if possible. Step 3: File the health insurance claim again after confirming with the insurer that the additional information provided is adequate.
Submit a formal complaint to your insurer's internal dispute resolution department. The Financial Advisory and Intermediary Services Act 37 of 2002 (FAIS Act) obliges insurers to have a complaints resolution process in place.
Nationwide, high-volume insurers with higher in-network denial rates across HealthCare states included Blue Cross Blue Shield of Alabama (35% for its 12 plans in that state), UnitedHealth Group (33% across 274 plans in 20 states), Health Care Service Corporation (29% across 915 plans in four states), Molina ...
In medical billing, a timely filing limit is the timeframe within which a claim must be submitted to a payer. Different payers will have different timely filing limits; some payers allow 90 days for a claim to be filed, while others will allow as much as a year.
Claims and payment timelines The timely filing guideline for HPSJ claims is three hundred and sixty-five (365) days from the date of service.
Molina Medicaid and Marketplace claims must be submitted by to Molina within six (6) months after the discharge for inpatient services or the date of service for outpatient services.