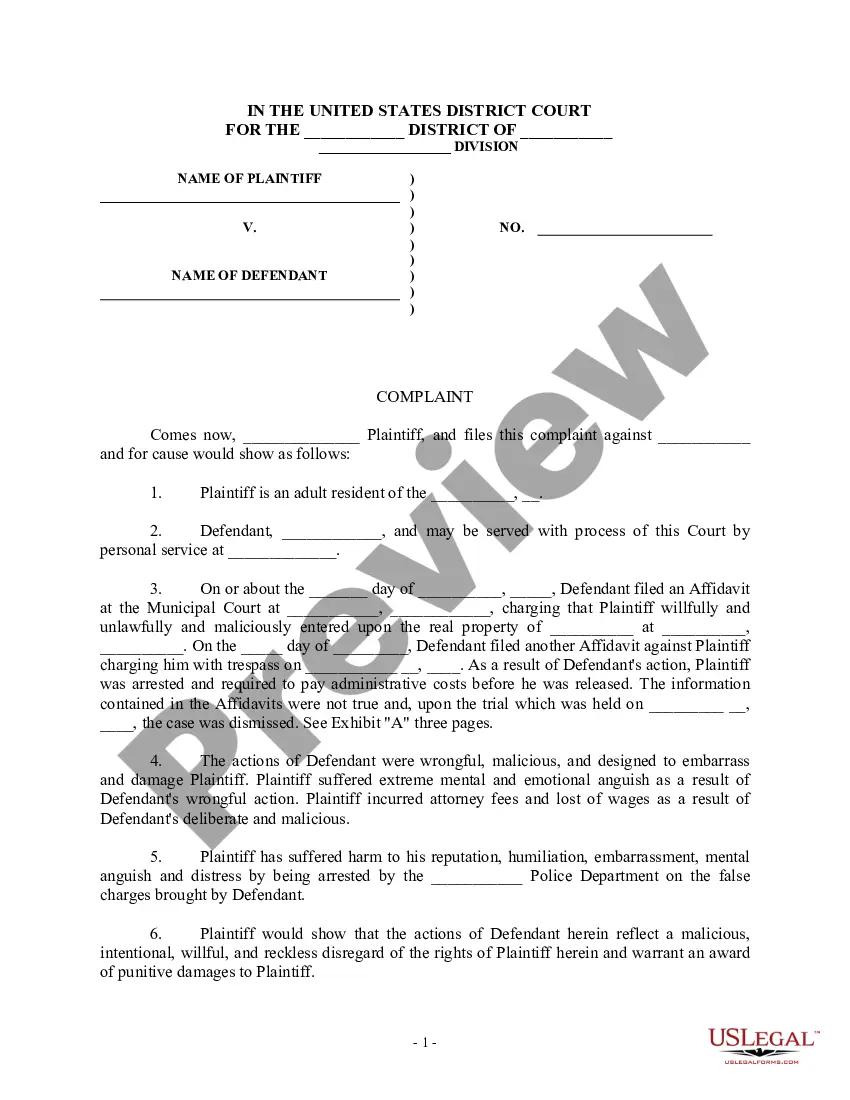
Account Estate Bank Foreclosure In Virginia
Description
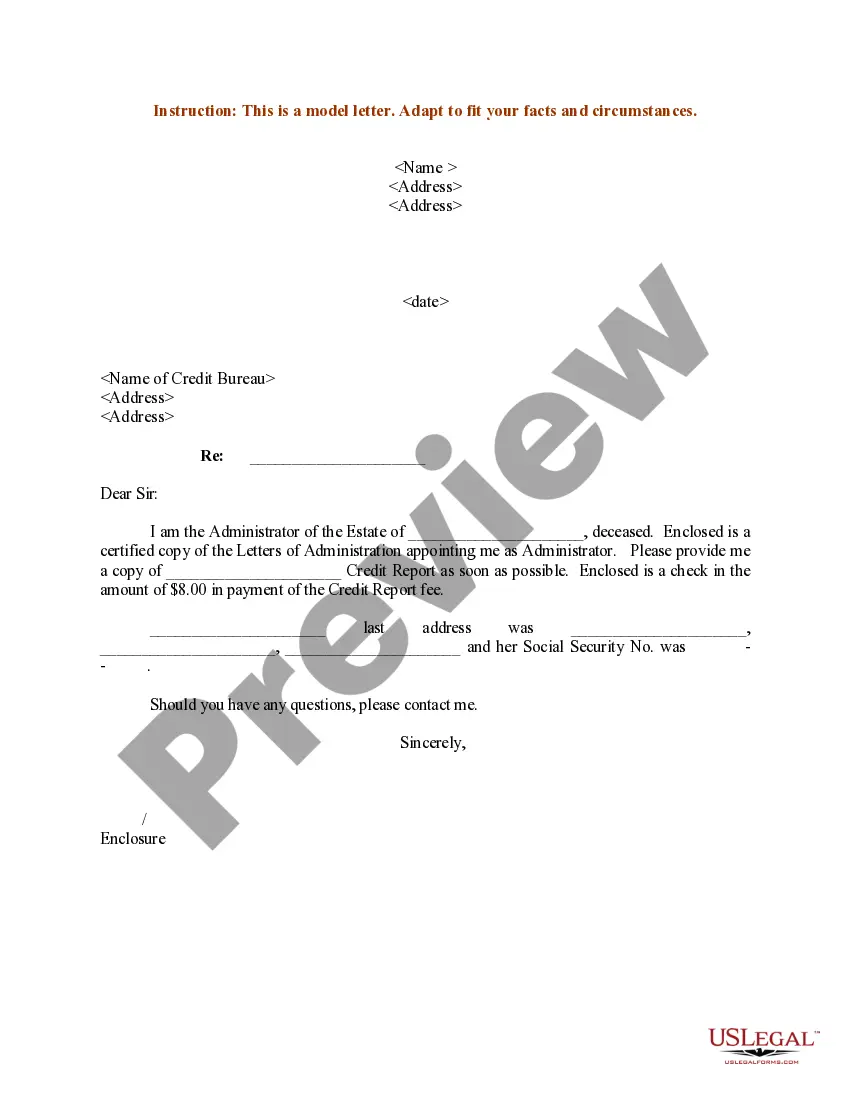
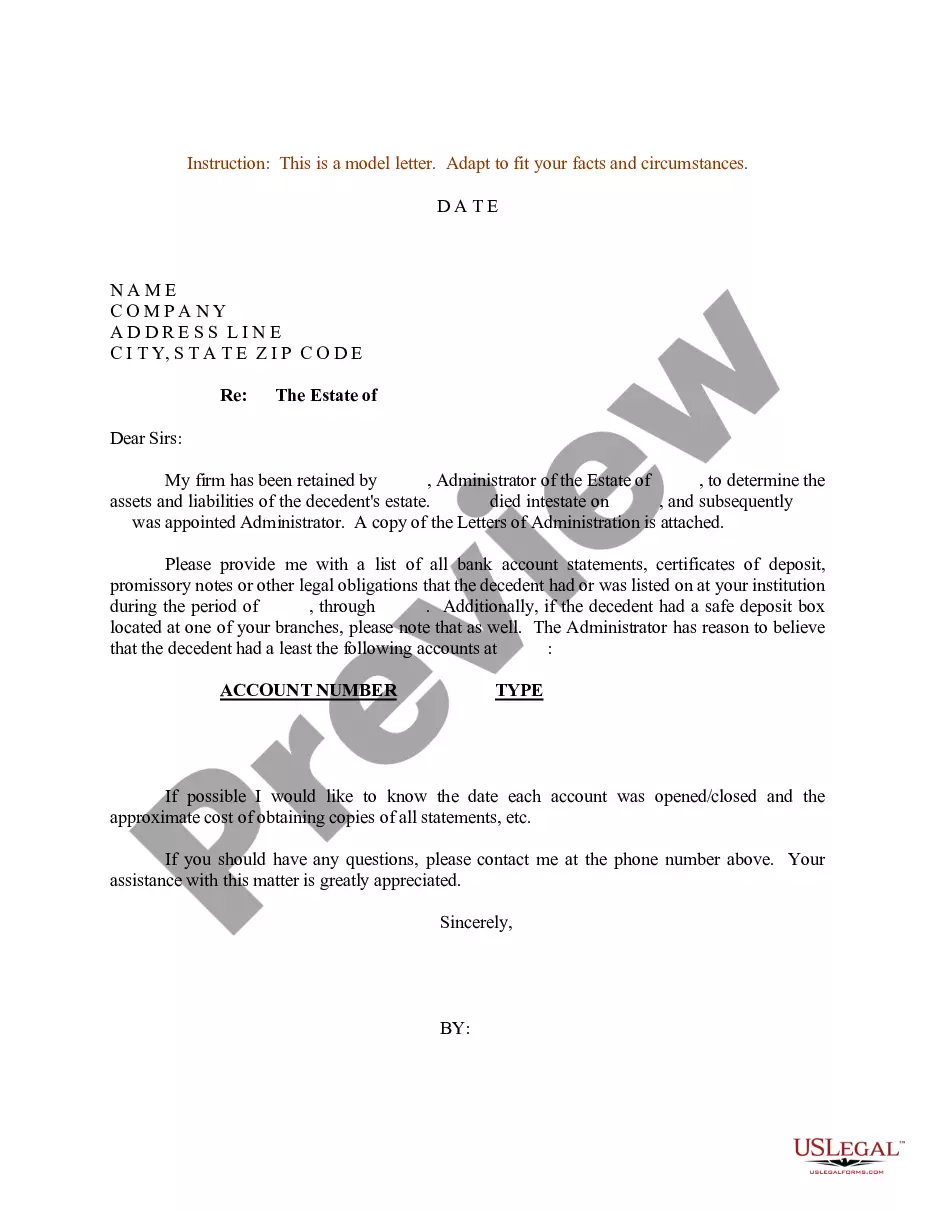
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
MLS: Most lenders list their REO properties on a Multiple Listing Service (MLS), so any real estate agent can help you identify REO offerings in your area. Bank websites: Some banks and credit unions have an entire department set up to sell REOs, and sections of their websites are dedicated to their listings.
Homeowners can typically claim surplus funds by filing a petition with the court that oversaw the foreclosure sale. It's advisable to seek legal assistance to navigate the process effectively.
The Consumer Financial Protection Bureau (CFPB), which is a federal agency, has set forth rules that say there can't be a foreclosure on some mortgages until the borrower is at least 120 days behind in payments.
A property can be foreclosed in Virginia in as little as 60 days if it foreclosed through the non judicial foreclosure process and the borrower does not contest or stall the proceedings. Judicial foreclosures vary in length depending on the court schedule and rulings.
Borrowers are entitled to loss mitigation evaluations under the new rules, even if they applied for and were rejected for loss mitigation before the new rules took effect, provided they file their complete applications more than 37 days before a scheduled foreclosure sale.