Decedent Account Bank With Or In Michigan
Description
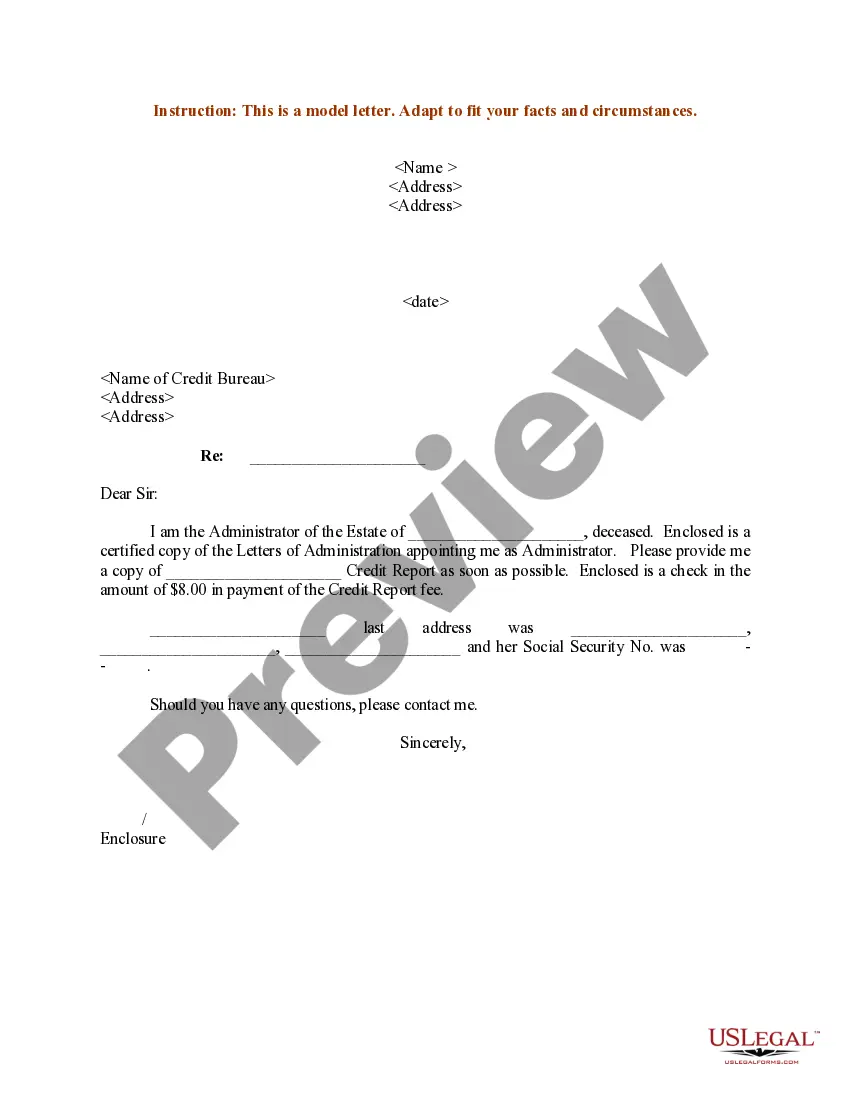
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
Rule: (a) Upon the death of an accountholder, the FDIC will insure the deceased owner's accounts as if he or she were still alive for six months after his or her death.
Some banks or building societies will allow the executors or administrators to access the account of someone who has died without a Grant of Probate.
Visit Banks in Their Area You will need to provide documentation to prove both that the account holder died and you have the legal authority (as a designated beneficiary, joint account holder or executor/administrator) to access the account.
In these cases, simply visit the bank with a valid ID and a certified copy of the death certificate. You will then have access to the account, allowing you to withdraw the funds as needed.
How to open an estate account Step 1: Begin the probate process. The steps for beginning this process depend on the state in which the deceased person resided. Step 2: Obtain a tax ID number for the estate account. Step 3: Bring all required documents to the bank. Step 4: Open the estate account.
If the account becomes part of the owner's estate, the legally designated executor can collect the funds and place them into an estate account. The joint owner, beneficiary or executor must provide a copy of the death certificate when taking action on the owner's account.
Any bank can handle an estate account. It isn't exactly rocket science, the main difference being the signer on the account was court-approved. Pick your favorite bank and go there.
DEATH OF AN ACCOUNT OWNER (12 C.F.R. § 330.3(j)) To ensure that families dealing with the death of a family member have adequate time to review and restructure their accounts if necessary, the FDIC will insure the deceased owner's accounts as if he or she were still alive for six months after his or her death.
No Beneficiary on Bank Account If there is no beneficiary listed on the bank account, the account typically goes through probate, and the funds will be distributed ing to the deceased's will or state laws if there is no will.
If you die without a will, some assets may go directly to co-owners or beneficiaries, including: Life insurance policy proceeds with a designated beneficiary. Retirement accounts with a designated beneficiary. Joint bank accounts or bank accounts payable on your death.