Issued Shares For Cash Journal Entry In Nevada
Description
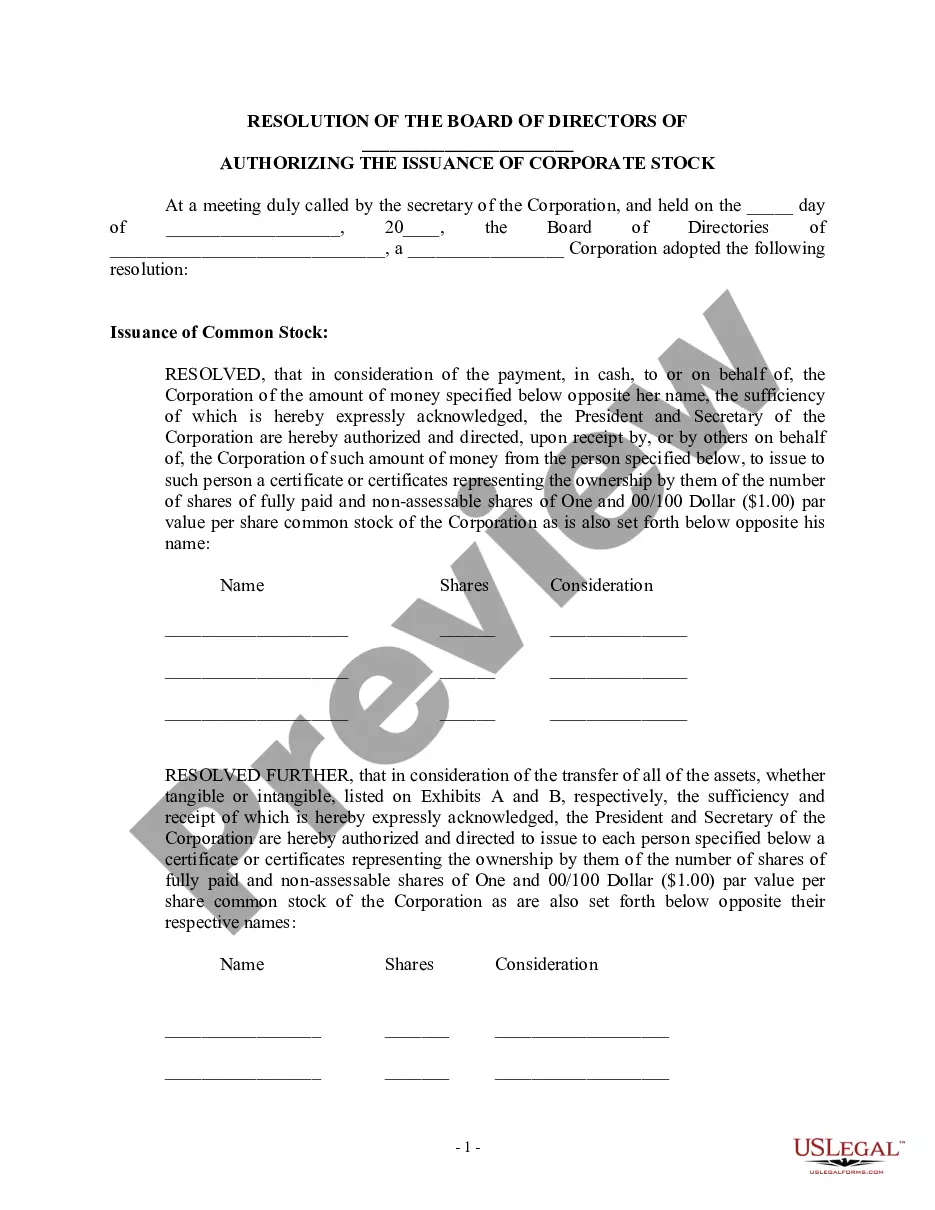
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
The accounting treatment of rights share is the same as that of issue of ordinary shares and the following journal entry will be made: Bank A/c To Equity shares capital A/c Dr. Bank A/c To Equity Share Capital A/c To Securities Premium A/c Dr.
Discount on the issue of shares should not be mixed with the share capital. Instead, it should be debited to a separate account known as a share discount account. It is shown as a separate item on the asset side of the balance sheet.
When shares are issued at a discount, the amount of such discount is debited to 'Discount on Issue of Shares Account', which is the nature of a capital loss for the company. For example, when a share of the nominal value of Rs. 100 is issued at Rs. 98, it is said to have been issued at a discount of Rs.
Issue of Share at Discount is always below the nominal value of shares. It is debited to separate account called 'Discount on Issue of Share' Account and is treated as Capital loss which means the loss incurred when a capital asset, such as an investment or real estate, decreases in value.
On the other hand we credit common stock to record the increase in the company's Equity. This meansMoreOn the other hand we credit common stock to record the increase in the company's Equity. This means that the company now has more funds available to invest in its operations.
Debit : Closing Stock a/c Assets are represented by real accounts. They carry a debit balance. By recording the journal entry for bringing the value of closing stock into books, we create the asset by name Closing Stock a/c. For this we have to debit the Closing Stock a/c.
Accounting for issue of shares depends upon the type of subscription. Whenever a company decides to issue shares to public, it invites applications for subscription by issuing a prospectus. It is not necessary that company receives applications for the number of shares to be issued by it.
The number of issued shares is recorded on a company's balance sheet as capital stock or owners' equity, while the shares outstanding (issued shares minus any shares in the treasury) are listed on the company's quarterly filings with the Securities and Exchange Commission.
