1031 Exchange Agreement Form For Uk In Cuyahoga
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
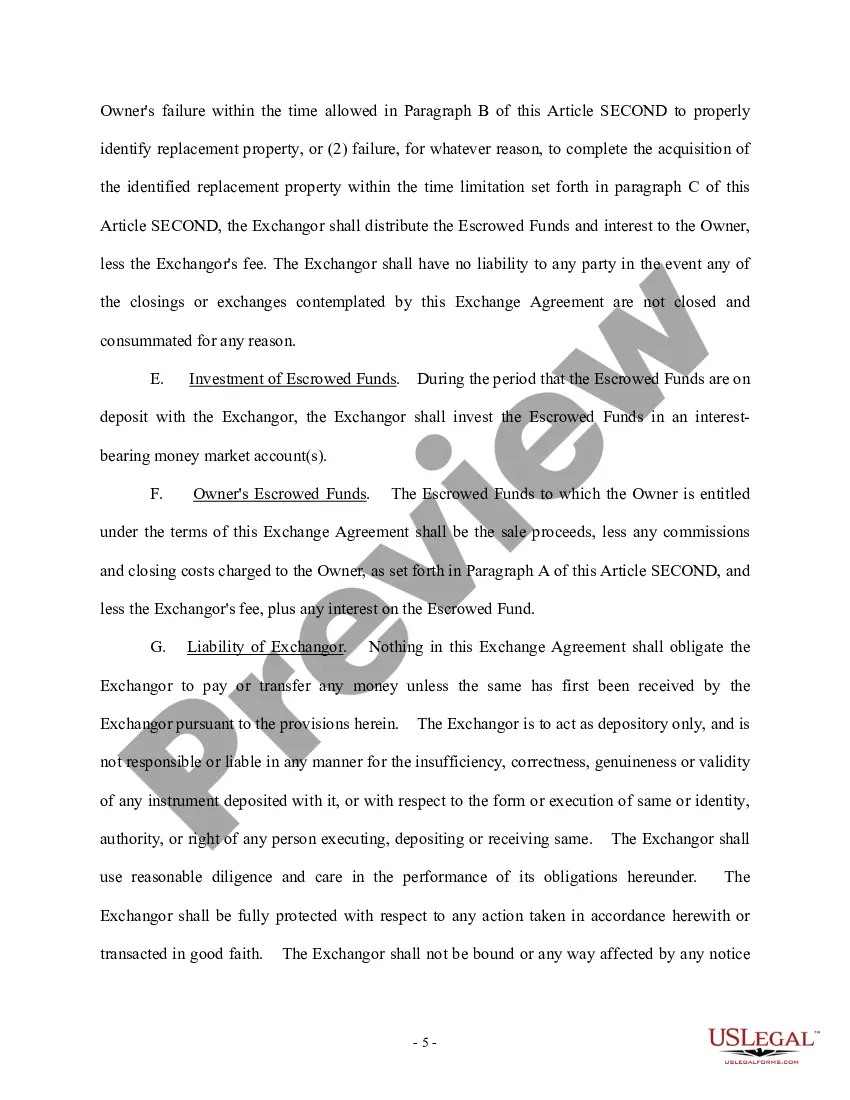
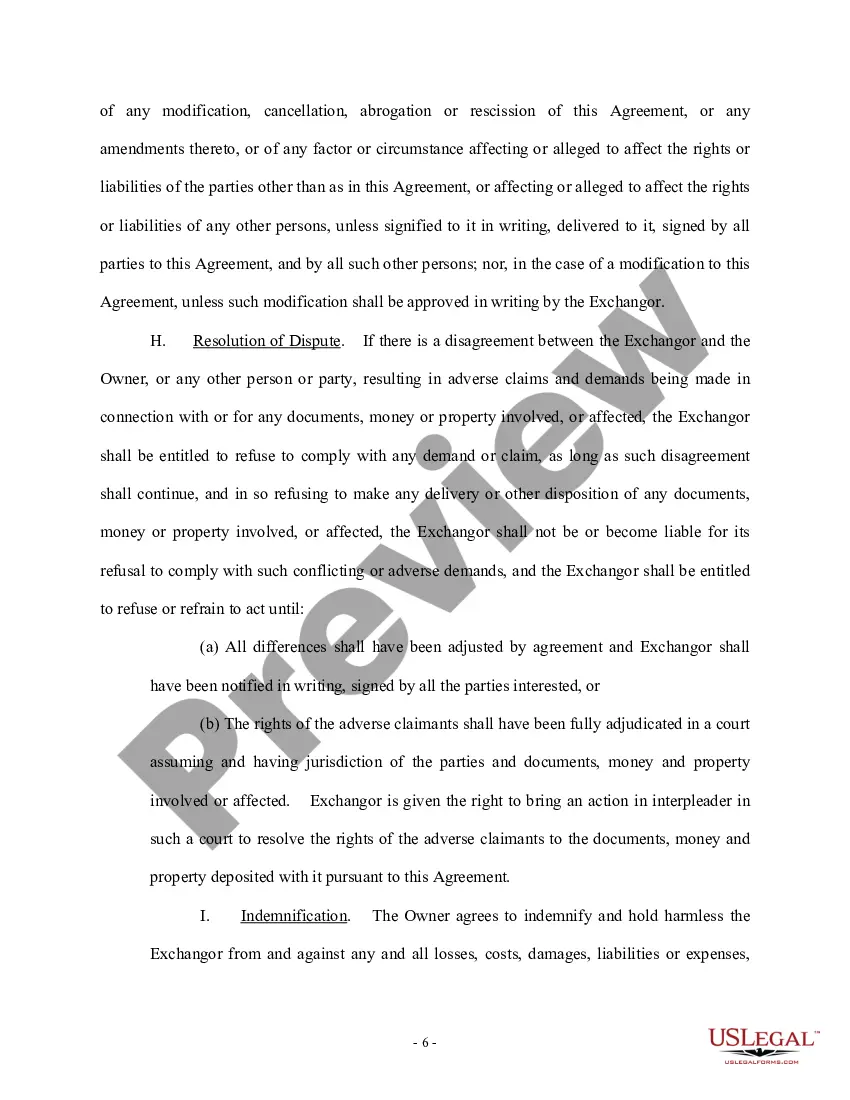
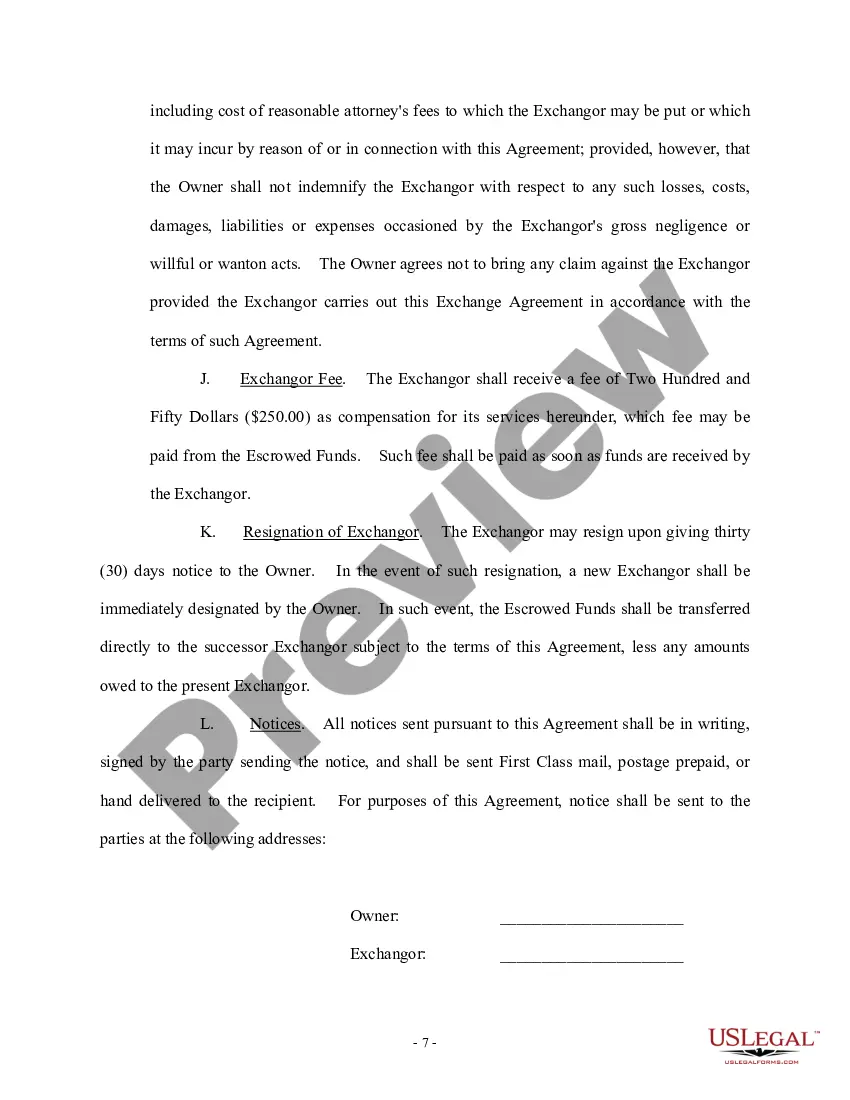
A Practice Note discussing Section 1031 like-kind exchanges of real estate, which is an important tax planning tool that allows real property owners to defer gains on the sale of real estate by investing the proceeds into replacement property.
While foreign property is not of a like kind with domestic property, foreign properties are considered like-kind with one another. You can perform a 1031 exchange with foreign properties, so long as your relinquished and replacement properties are both located outside the United States.
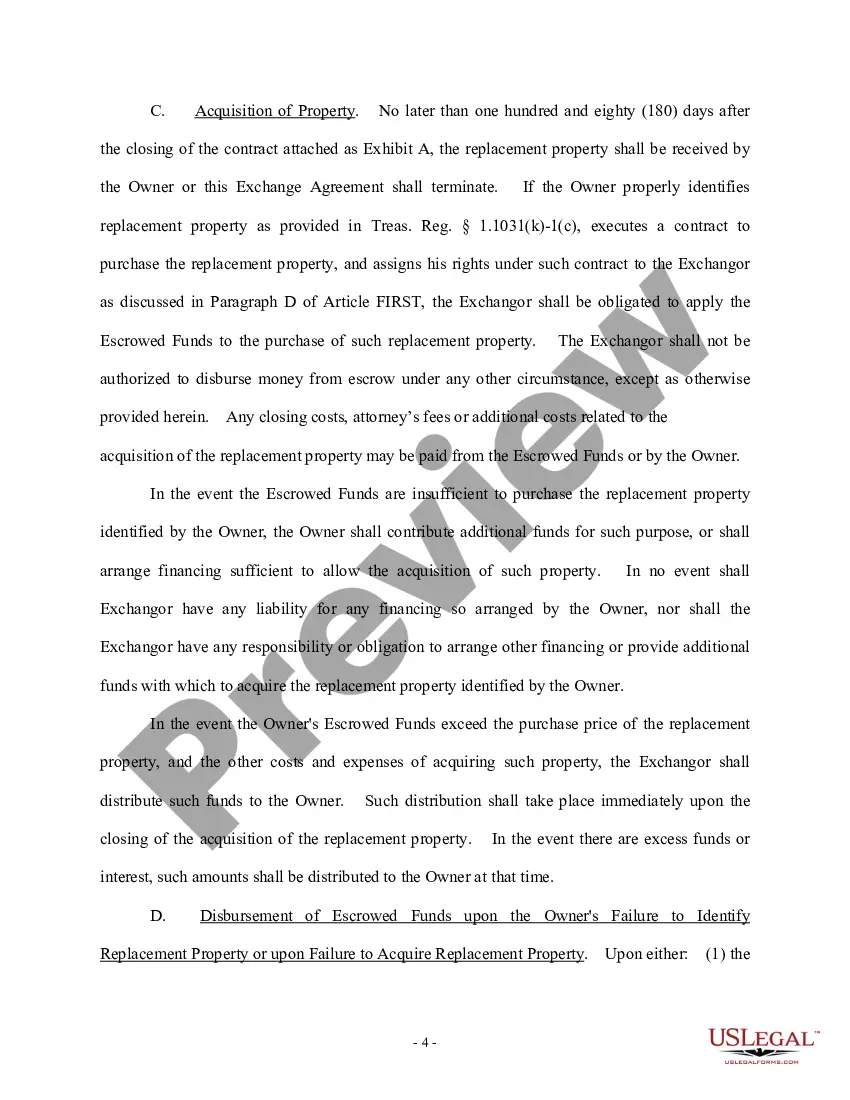
For a 1031 exchange in Ohio, an investor must identify a replacement property within 45 days from the sale of the relinquished property. Furthermore, the transaction must be completed by acquiring the replacement property within 180 days of the sale or by the tax filing deadline, whichever comes first.
This means that you cannot perform a 1031 exchange between a U.S. property and a non-U.S. property. If your relinquished property is located within the United States, then your replacement property must also be located within the United States (or certain U.S. territories) to qualify for 1031 tax deferral.