Letter For Recovery Debt In Minnesota
Description
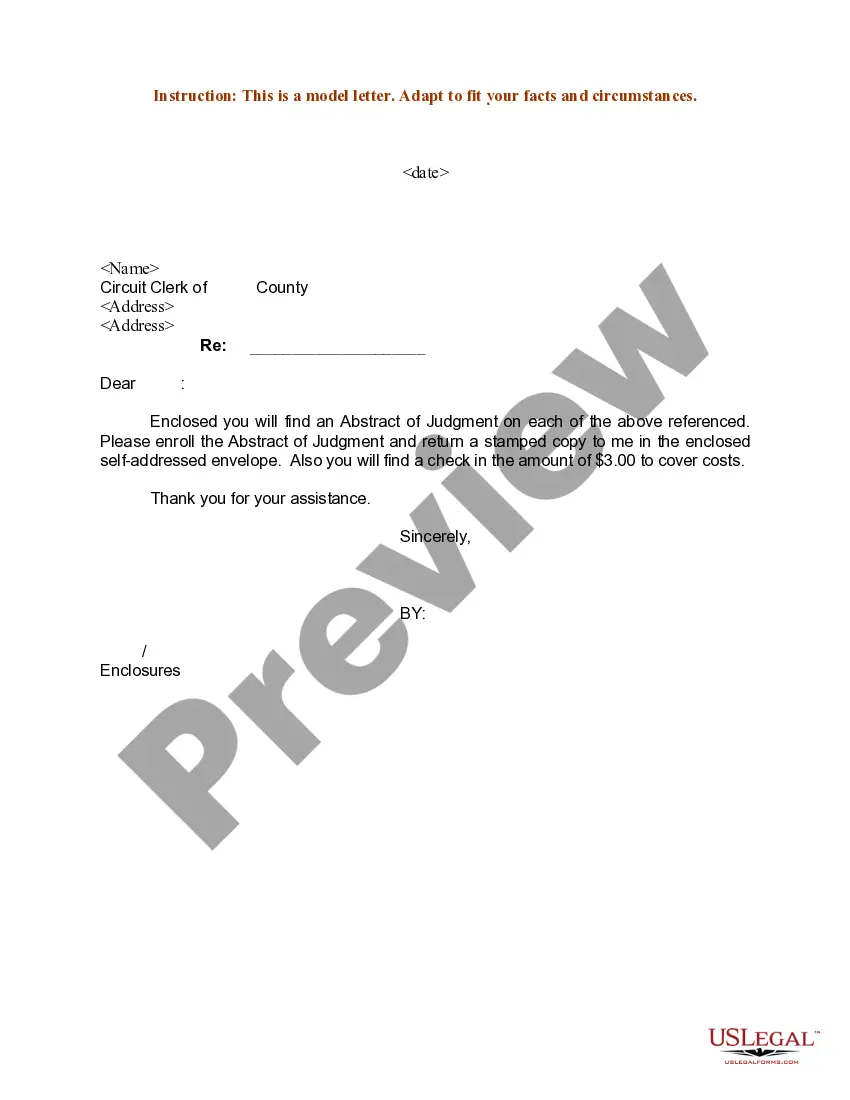
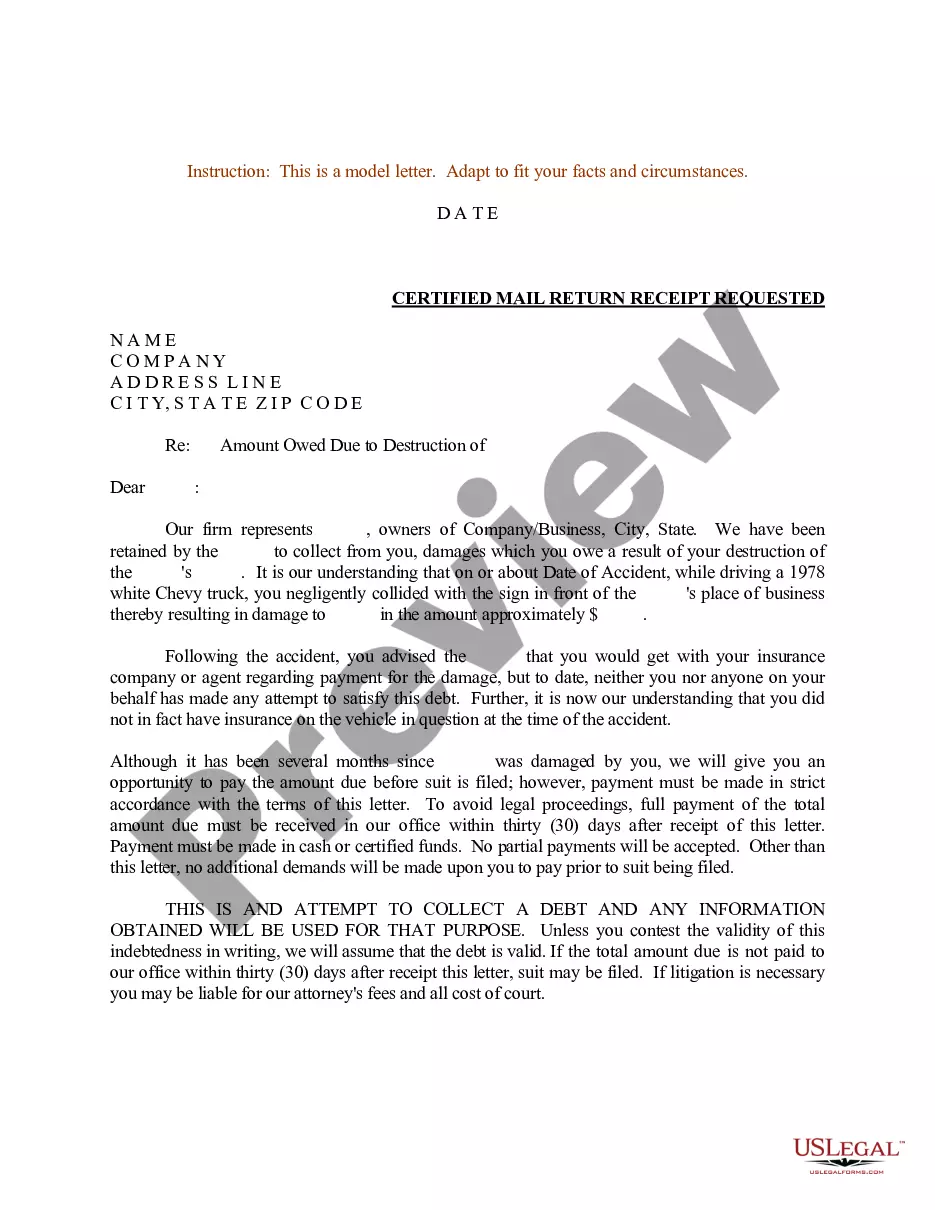
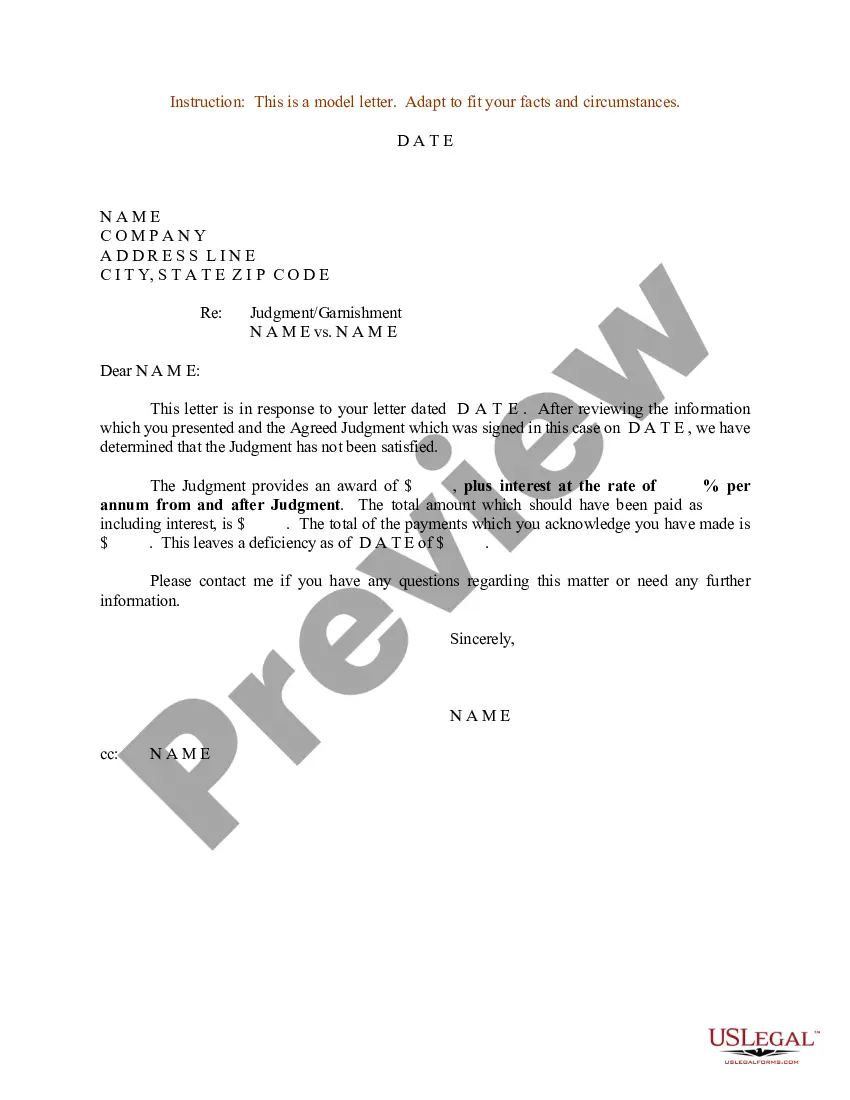
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
Specifically, the rule states that a debt collector cannot: Make more than seven calls within a seven-day period to a consumer regarding a specific debt. Call a consumer within seven days after having a telephone conversation about that debt.
Here are the steps you can take: Send a written request: Draft a formal letter to the debt collector requesting debt verification. Include your name, address, and account number associated with the debt. Clearly state your intention to verify the debt and request all relevant information and documentation.
Yes it does actually work. Collectors rarely actually validate the debt because most of the debts in fact are not valid. Some just back off because receiving a well worded debt validation letter means you have consulted the FDCPA (or at least a good debt/credit forum) and know what you're doing.
Most states or jurisdictions have statutes of limitations between three and six years for debts, but some may be longer. This may also vary depending, for instance, on the: Type of debt.
While smaller debts are less likely to result in legal action, there are no guarantees. In many cases, though, debt collectors will prioritize larger debts, as they offer a higher return on the time and legal fees associated with a lawsuit.
If you do not respond, you will lose certain rights, but it is not a legal admission, usable in court, that you owe the debt. If there is no response, or if the letter goes back to the collection agency undelivered or marked moved, deceased, in jail, etc., the collection agency can still due you.
If you don't respond within the 10 days after a credit reporting agency requests a notarized dispute letter, the CRA will likely close the dispute without further investigation. This means the disputed information may remain on your credit report as originally reported.
Dear Creditor: Please provide me with verification of the debt which you state I owe. Please provide me with any records which are in your possession, including, but not limited to, all statements of each account, invoices, and any other documentation which I may have signed.
Include your full name, company name, and mailing address. Address the letter to your client by their full name. State the problem: Specify and provide proof of the debt in question. Reference the original contract or agreement that states the services the client owes you for.
These letters often include details like the amount owed, the due date, and any applicable interest or late fees. It's important to note that debt collection letters should adhere to legal regulations and guidelines, such as those outlined by the Fair Debt Collection Practices Act (FDCPA) in the United States.