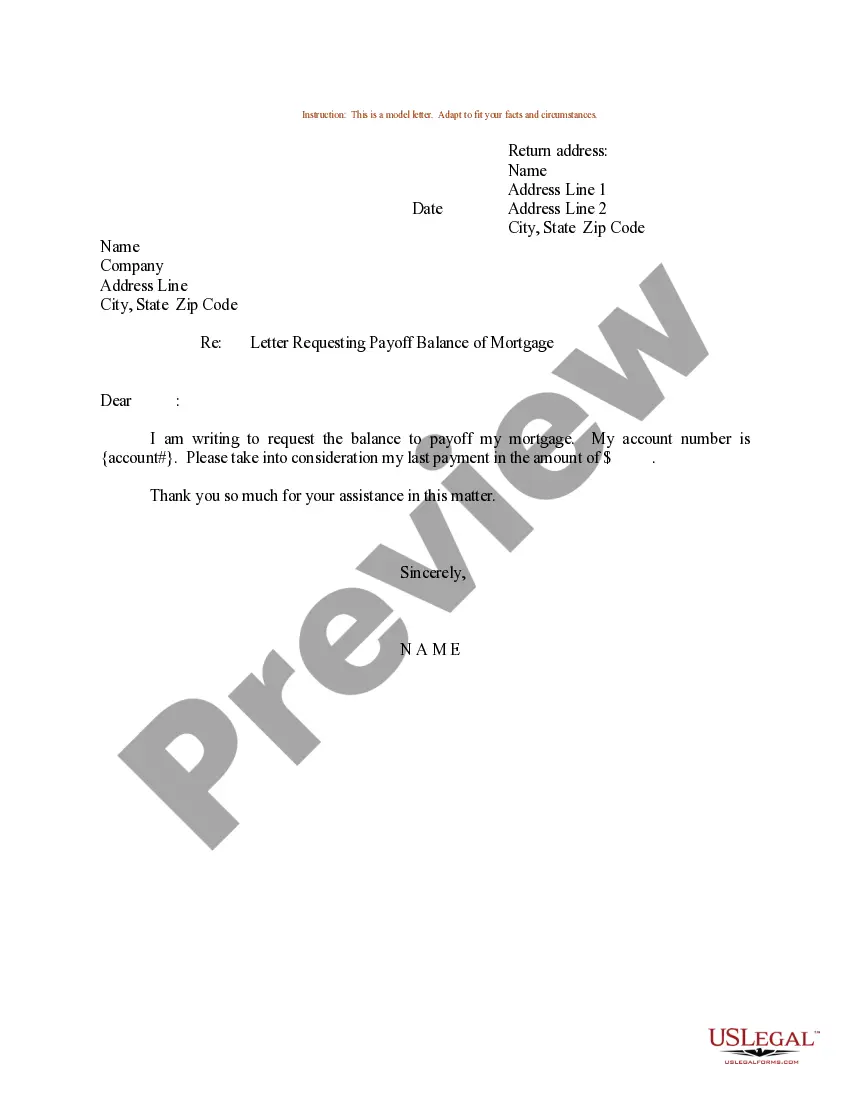
Payoff Mortgage Form Sample With Credit Card In Santa Clara
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?



Form popularity
FAQ
If you open the credit card now, your lender will likely postpone that closing to run it back through underwriting at minimum. Many times they'll pull credit right before closing. The home is the main goal and you certainly don't want to do anything to delay or derail that process.
The general rule of thumb is not to screw with your credit 6 months prior to applying for a mortgage unless absolutely necessary. If they choose to up you limit on their own they can and it will not impact your credit through an inquiry.
Your credit card application is unlikely to impact your mortgage application unless you had a fairly poor credit score to start.