Secured Debt Shall For Bad Credit In Hillsborough
Description
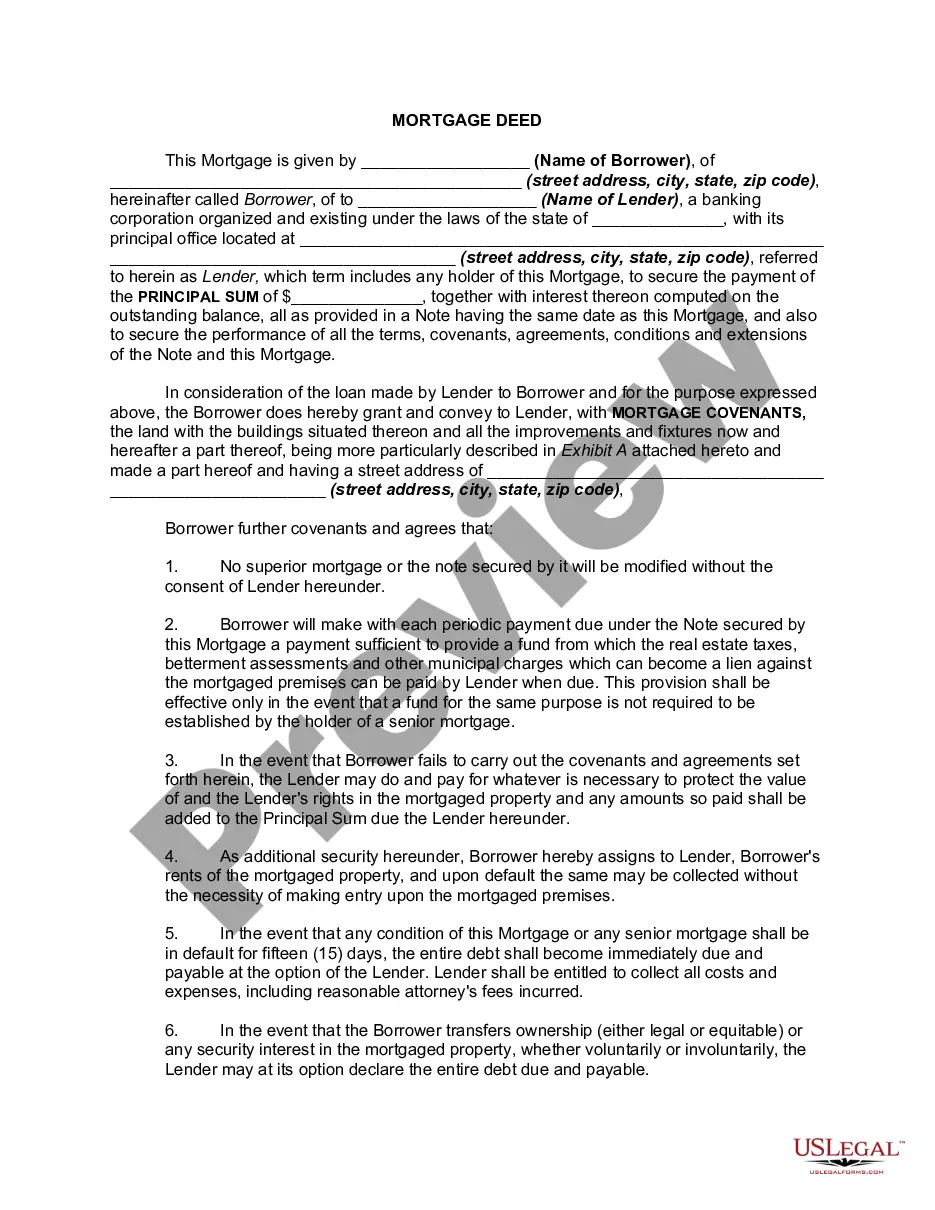
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?




Form popularity
FAQ
In many cases, a bankruptcy discharge can eliminate your personal responsibility for secured debt, so the lender can't sue you for unpaid amounts. However, the lien on the property doesn't automatically go away. The lender can still take back the collateral if you stop making payments.
If the debtor's disposable income, projected for a five-year period, is more than 25 percent of the total unsecured debt, the debtor will likely be denied a Chapter 7 filing. If the percentage is less than 25 percent, the debtor will most likely survive the means test and be allowed to continue with a Chapter 7 filing.
When it comes to credit card debt relief, it's important to dispel a common misconception: There are no government-sponsored programs specifically designed to eliminate credit card debt. So, you should be wary of any offers claiming to represent such government initiatives, as they may be misleading or fraudulent.
The court may deny a chapter 7 discharge for any of the reasons described in section 727(a) of the Bankruptcy Code, including failure to provide requested tax documents; failure to complete a course on personal financial management; transfer or concealment of property with intent to hinder, delay, or defraud creditors; ...
Here are strategies and tips for getting out of debt faster. Add Up All Your Debt. Adjust Your Budget. Use a Debt Repayment Strategy. Look for Additional Income. Consider Credit Counseling. Consider Consolidating Your Debt. Don't Forget About Debt in Collections. Stay Accountable.
Contrary to popular belief, there is no specific minimum amount of debt required to file for Chapter 7 bankruptcy.
Contrary to popular belief, there is no specific minimum amount of debt required to file for Chapter 7 bankruptcy.
An individual cannot file under chapter 7 or any other chapter, however, if during the preceding 180 days a prior bankruptcy petition was dismissed due to the debtor's willful failure to appear before the court or comply with orders of the court, or the debtor voluntarily dismissed the previous case after creditors ...
Yes, debt consolidation with bad credit is possible, but it may be more difficult to obtain than if you had good credit. With bad credit, you may have limited options for debt consolidation, as lenders may view you as a higher risk borrower.
When it comes to credit card debt relief, it's important to dispel a common misconception: There are no government-sponsored programs specifically designed to eliminate credit card debt. So, you should be wary of any offers claiming to represent such government initiatives, as they may be misleading or fraudulent.