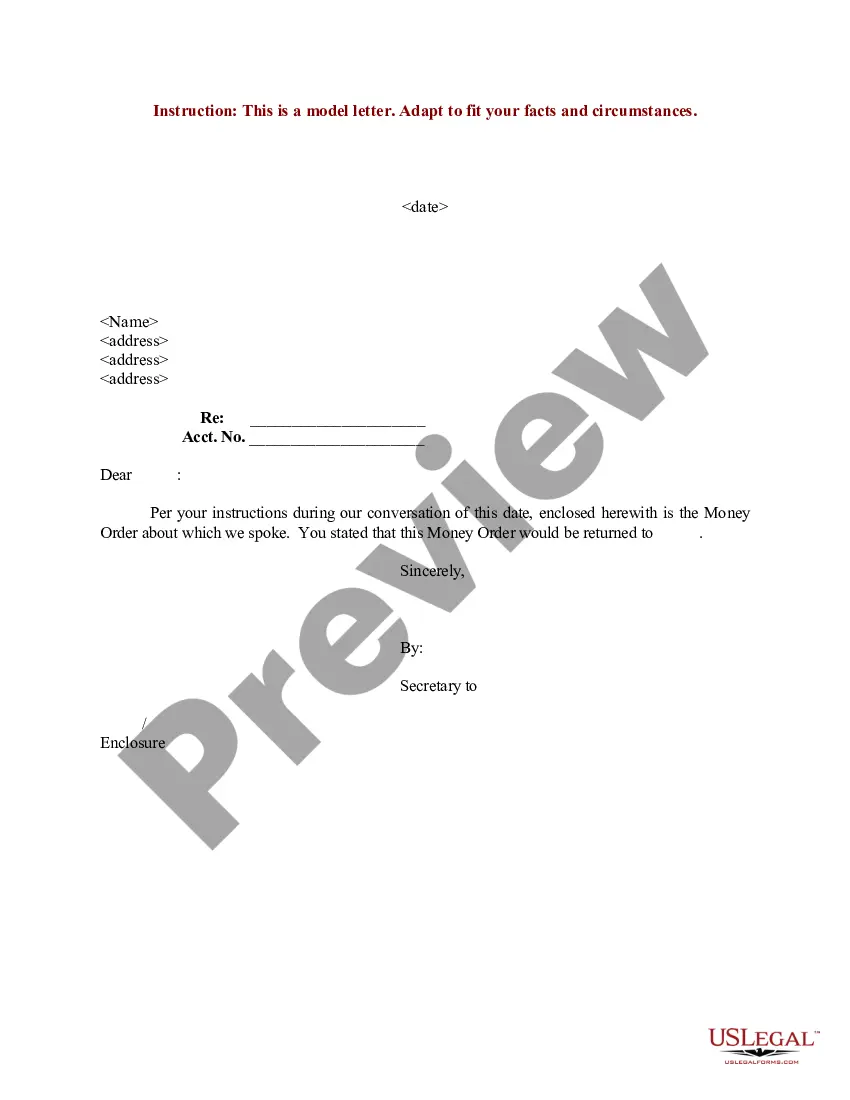
Letter For Money Lending In California
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
A mortgage commitment letter is not the same as final approval, but it shows that you're in a good position to buy a home. Once you make an offer on a home and the seller accepts it, you can move on to the full application process, which involves a more in-depth review of your finances and the property you want to buy.
Employers may offer letters of commitment during job offer negotiations. This letter may include salary, benefits, and bonuses. By signing the letter, the employee agrees to accept the company's job offer for the specified terms and compensation.
The CRMLA was enacted as an alternative to the existing laws licensing lenders under the Real Estate Law and the California Finance Lenders Law, in order to provide mortgage bankers with a licensing law specifically intended to regulate their primary functions of originating and servicing residential mortgage loans.
The California Financing Law requires the licensing and regulation of finance lenders and brokers making and brokering consumer and commercial loans. Through licensing, regulation, and oversight of these lenders, DFPI supports a healthy and trusted financial marketplace.
An application for a license under the California Financing Law must be filed through the Nationwide Multistate Licensing System (NMLS). A company must complete an NMLS Company Form (MU1) for a main license before applying for a branch license on the NMLS Branch Form (MU3).
General Overview: The CFLL applies to lenders who make consumer or commercial loans, whether unsecured or secured by real or personal property or both, to consumers for use primarily for personal, family, or household purposes. The CFLL is regulated by the Department of Corporations (DOC).
An application for a license under the California Financing Law must be filed through the Nationwide Multistate Licensing System (NMLS). A company must complete an NMLS Company Form (MU1) for a main license before applying for a branch license on the NMLS Branch Form (MU3).