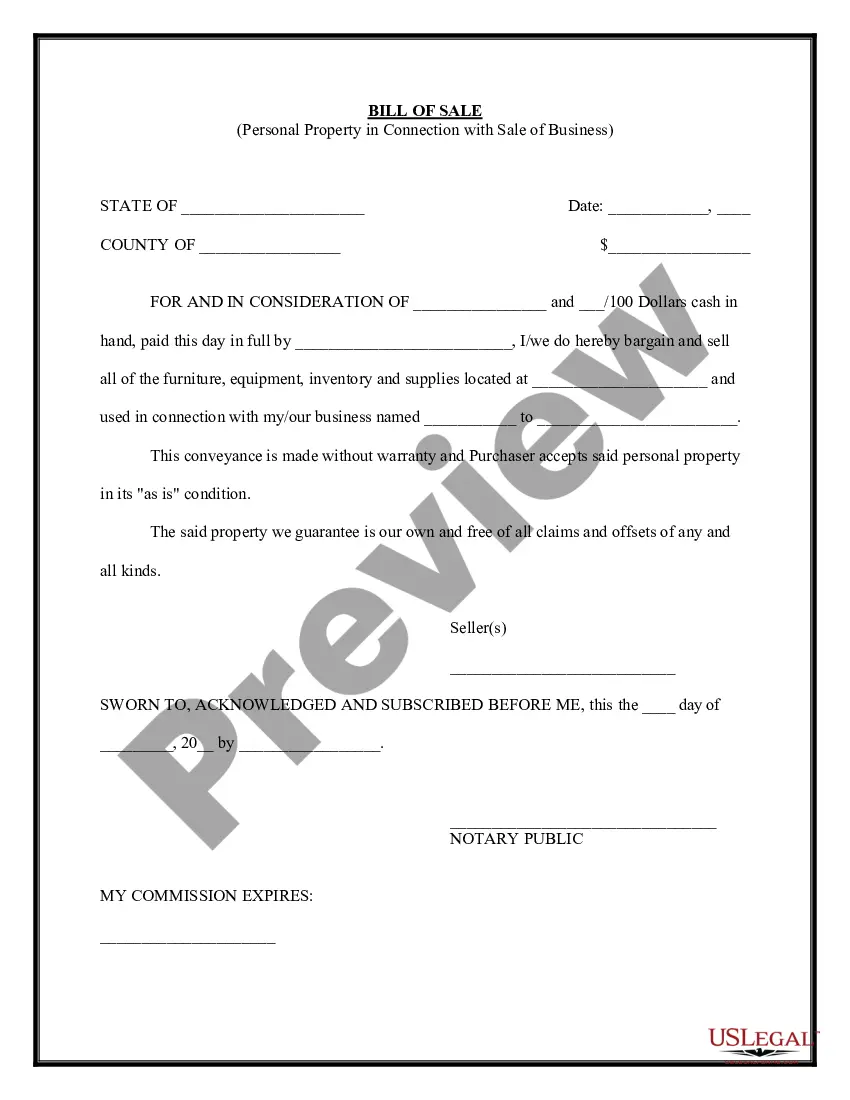
Printable Bill Of Sale Form For Mobile Home In Orange
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
The Utah Bill of Sale impacts tax obligations for both the buyer and the seller. For instance, when selling a vehicle, the buyer must present the Bill of Sale to the Utah Division of Motor Vehicles (DMV).
Getting a bill of sale notarized isn't always required, but it's often worth the effort. Notarization provides solid proof of agreement and can protect you in legal disputes. Always check local DMV requirements for specific transactions to avoid potential issues.
You will need to fill out several forms to complete a title transform, such as: Bill of sale. California Multi-Purpose Transfer Form. Original title. County tax clearance certificate.
For regular homeowners, HO-1 and HO-2 are named-peril policies, while the HO-3 is the all-perils policy. The HO-4 covers apartment renters, but condo owners are best served by an HO-6. Mobile homes are covered under the HO-7, but only when they're stationary; motor homes aren't covered.
Targeted for manufactured homes that are 20 years old or newer, our HO-3 Homeowners policy includes dwelling coverage, personal liability, personal property, additional living expense, other structures, and third-party medical payments.
Mobile home form: HO-7 A typical mobile home insurance policy is an HO-7 form. It helps protect the personal property and physical structure of the home. This type of policy form is a modified version of an HO-2. The perils covered by an HO-7 may be different than those covered by a standard HO-2.
The HO-7 policy is an insurance policy for mobile home owners. It covers the dwelling and other structures, personal property, personal liability, loss of use, and medical expenses of others for mobile homes, RVs, sectional homes, modular homes, and trailers while stationary.
Get a bill of sale from a regulatory agency. Many government agencies, like the Department of Motor Vehicles, for instance, offer bill of sale forms for public use. Using a form directly from a government agency ensures that you have all of the information required for your state.
For HO3 policies, it's common to see open perils coverage for your home itself and named perils for your personal property. HO5 policies feature open perils coverage for both. If you're a condo owner with an HO6 policy, you're covered for everything inside the walls of your place for named perils.