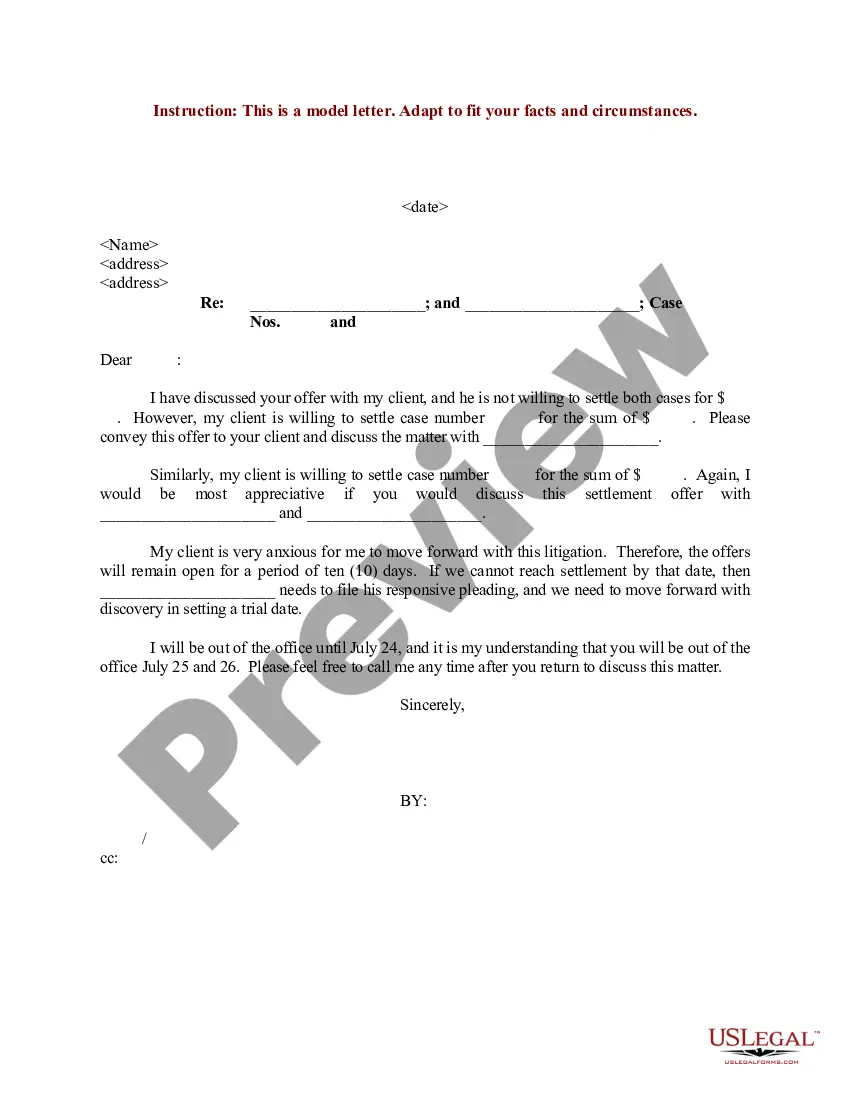
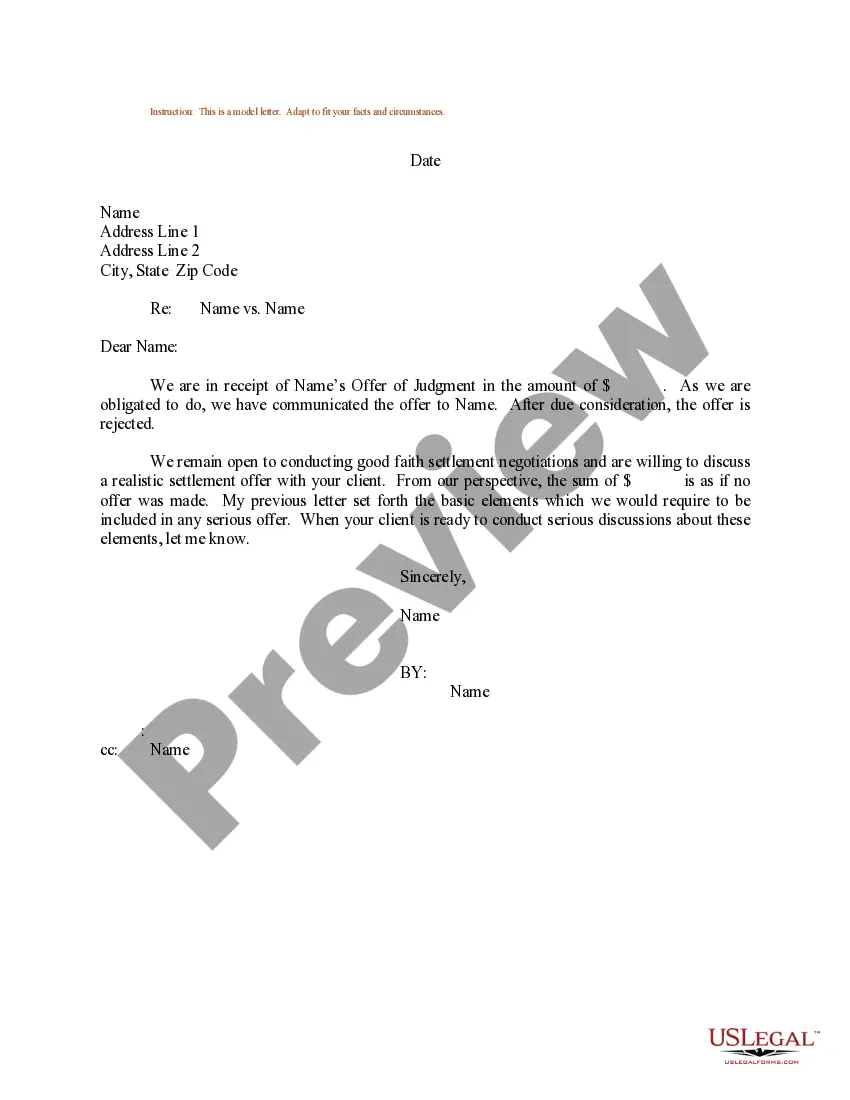
Sample Letter Rejecting Settlement Offer For Medical Bills In Alameda
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
You can choose to decline your employer's health insurance, but make sure to carefully evaluate your budget and alternative options before making a decision. Individual health plans can be significantly more expensive than employer-sponsored coverage, especially if your employer contributes to premiums.
If you get a lowball settlement offer from the insurance company, you should not accept the offer right away. Instead, you should review the offer to determine whether it compensates your damages adequately. Negotiating with the insurer is one way to respond to a lowball settlement.
What happens if you reject a settlement offer? When you reject a settlement offer, it triggers negotiations between you (or your lawyer) and the insurance company. This allows you to submit a counteroffer that better reflects the value of your damages, such as medical bills, lost wages, and pain and suffering.
How do you write an insurance cancellation letter? Keep it simple : A one-page notice of cancellation will do. Include all required information : Make sure to include all required information from your insurer for cancellation notification. Be polite, but firm : Write in a polite, yet firm tone.
Consider Sending a Demand Letter Depending on the circumstances and negotiations, your personal injury lawyer may consider sending the insurance company a formal demand letter. In a demand letter, your attorney outlines the details of your claim and the desired compensation for your injuries and losses.
This offer should be rejected. It's too early in the process to understand the full impact of your injuries, and you risk under settling your claim dramatically.
Don't give recorded statements – If asked to give a recorded statement, respectfully say no until you've talked with your attorney. Providing a statement without speaking with your lawyer could hurt your case and your chance for a fair settlement.
Yes, rejecting a settlement offer is often the beginning of negotiations. After you reject, your attorney will likely present a counteroffer based on the full value of your claim, supported by evidence like medical records and financial documentation.
name of claims adjuster, I received your letter dated date of written settlement offer. I have reviewed your letter very carefully, including your settlement offer. Unfortunately, I cannot accept your offer for the reasons discussed below.
This letter should state: That you will not accept the initial settlement offer; The reasons why you feel you deserve a higher settlement amount; Each of their low-offer reasons, and your responses; The higher settlement amount that you will accept.