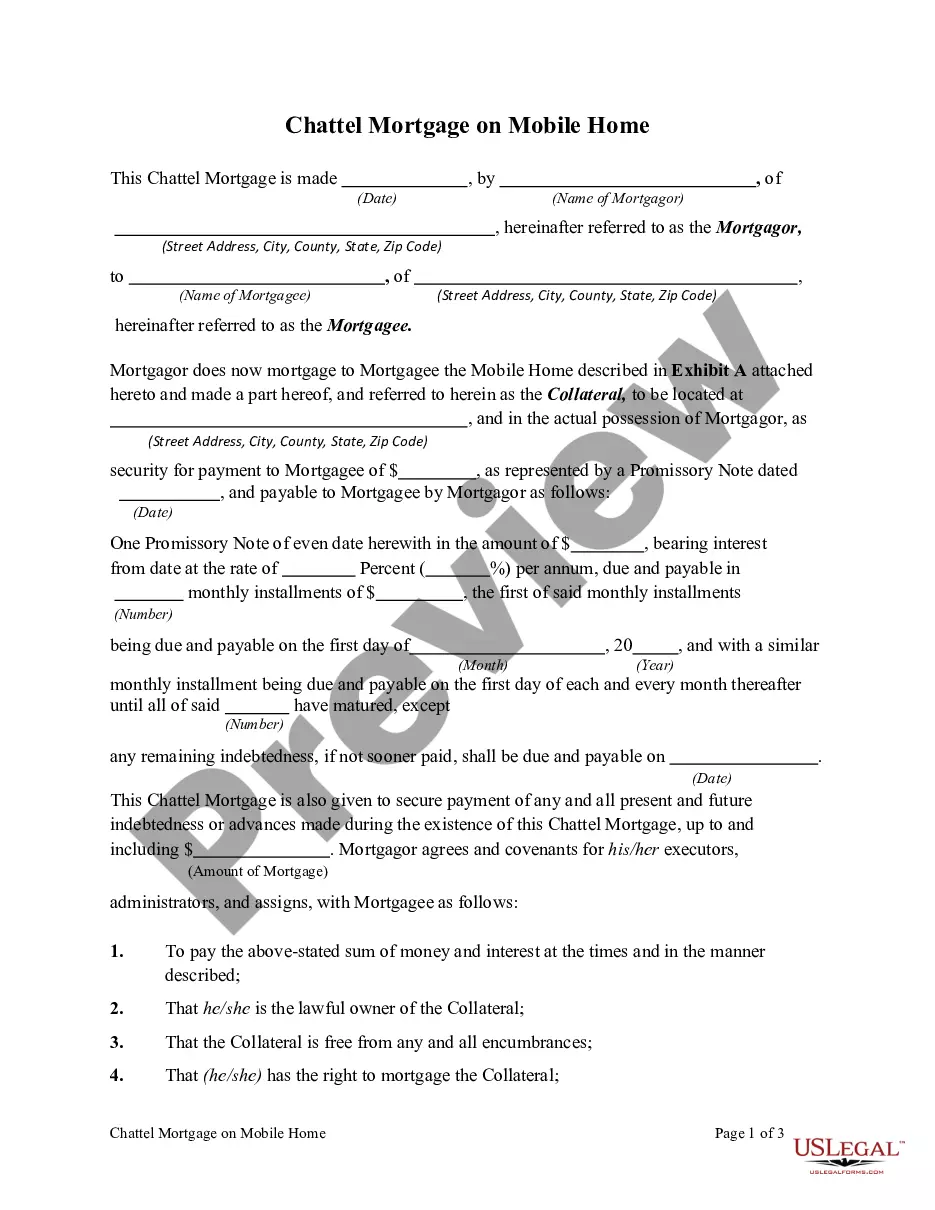
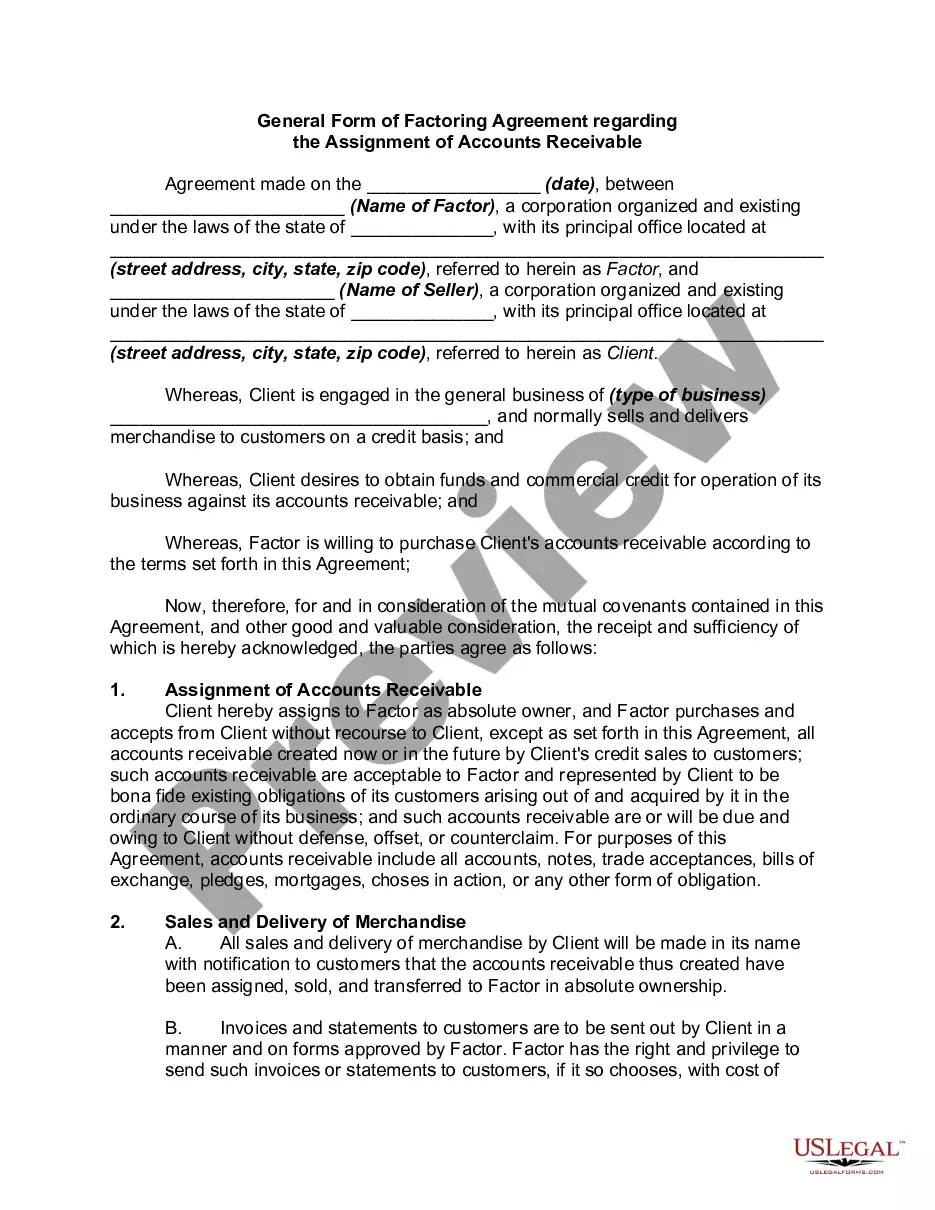
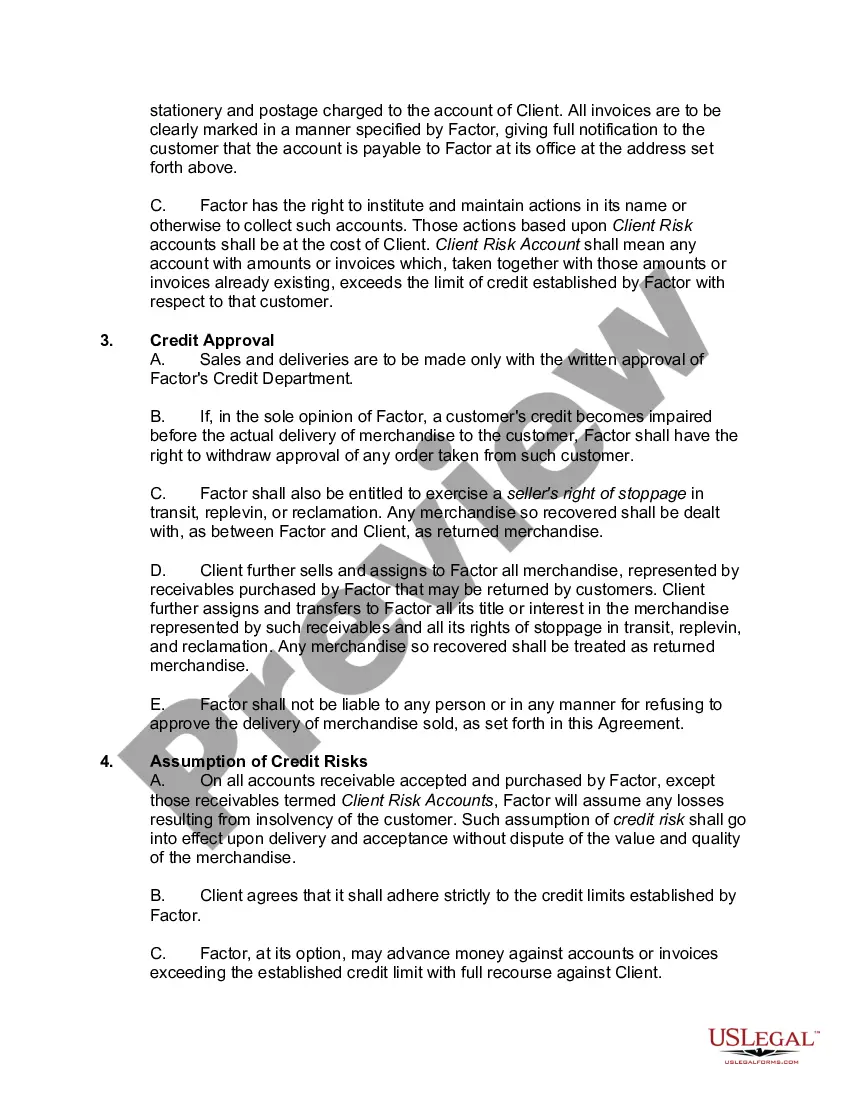
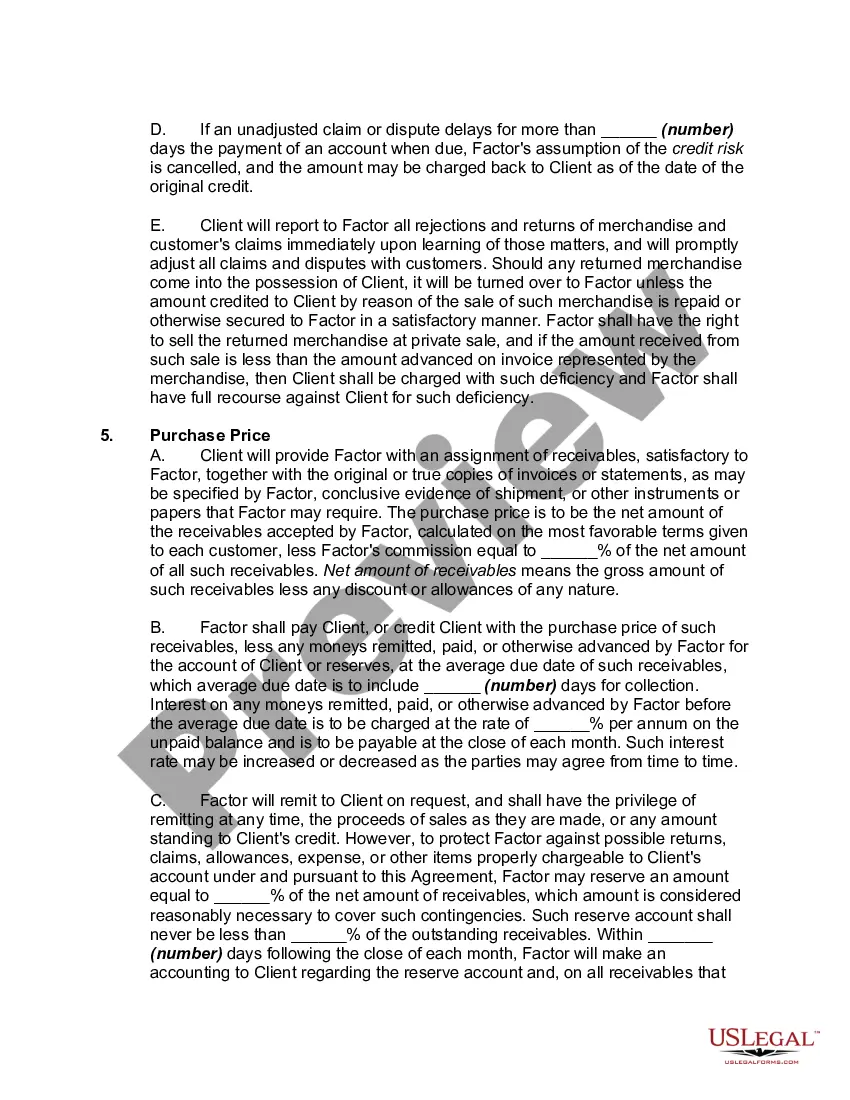
Factoring Purchase Agreement With Credit Card In Harris
Description

Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?


Form popularity
FAQ
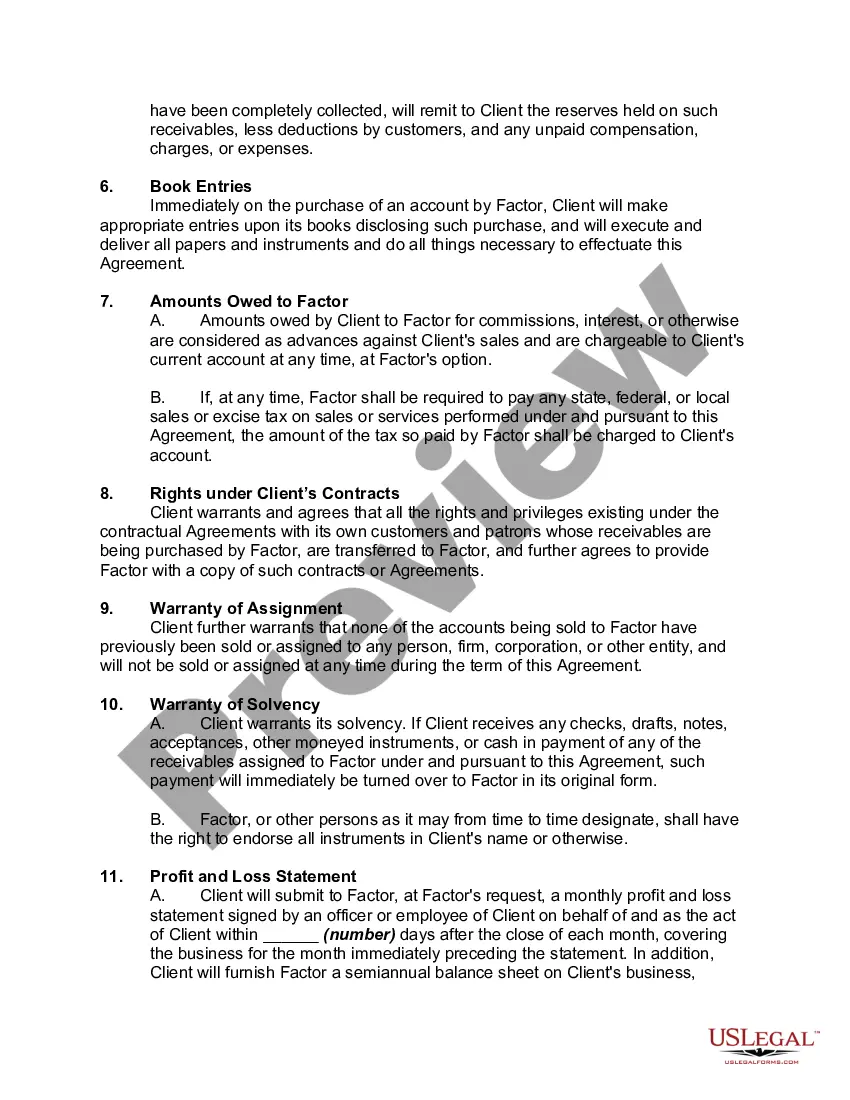
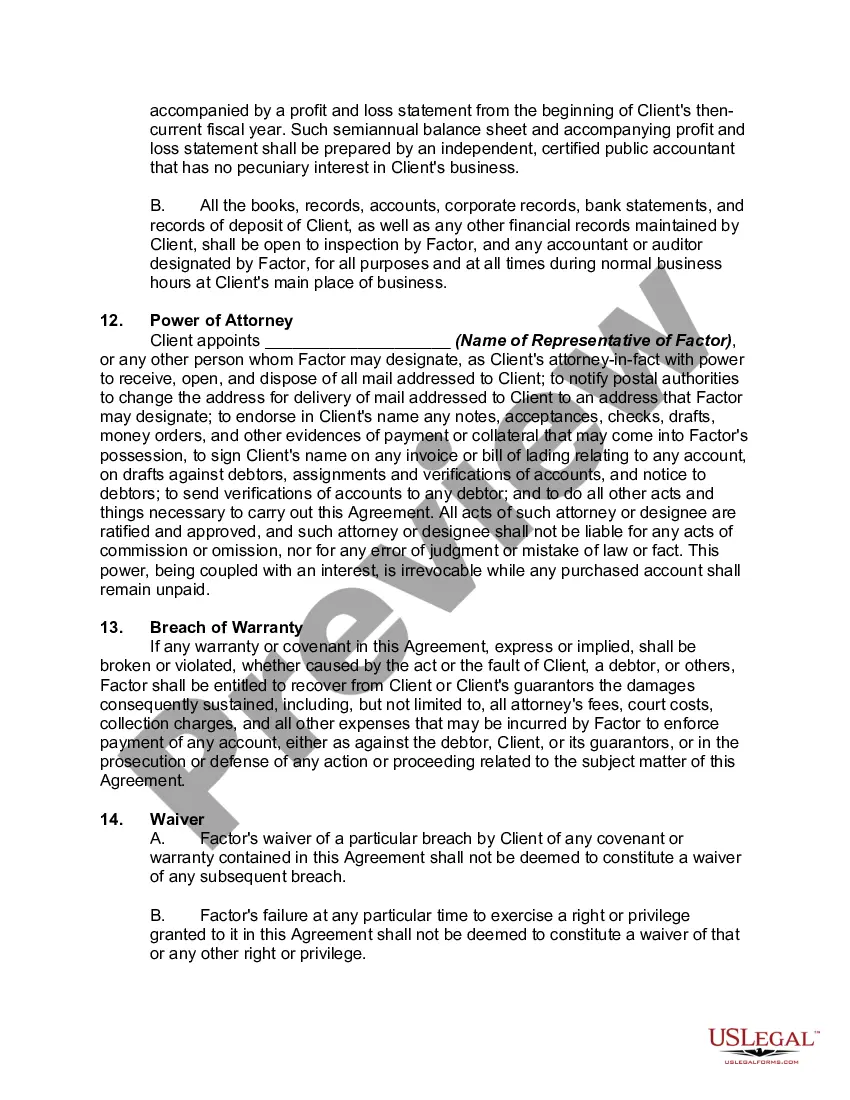
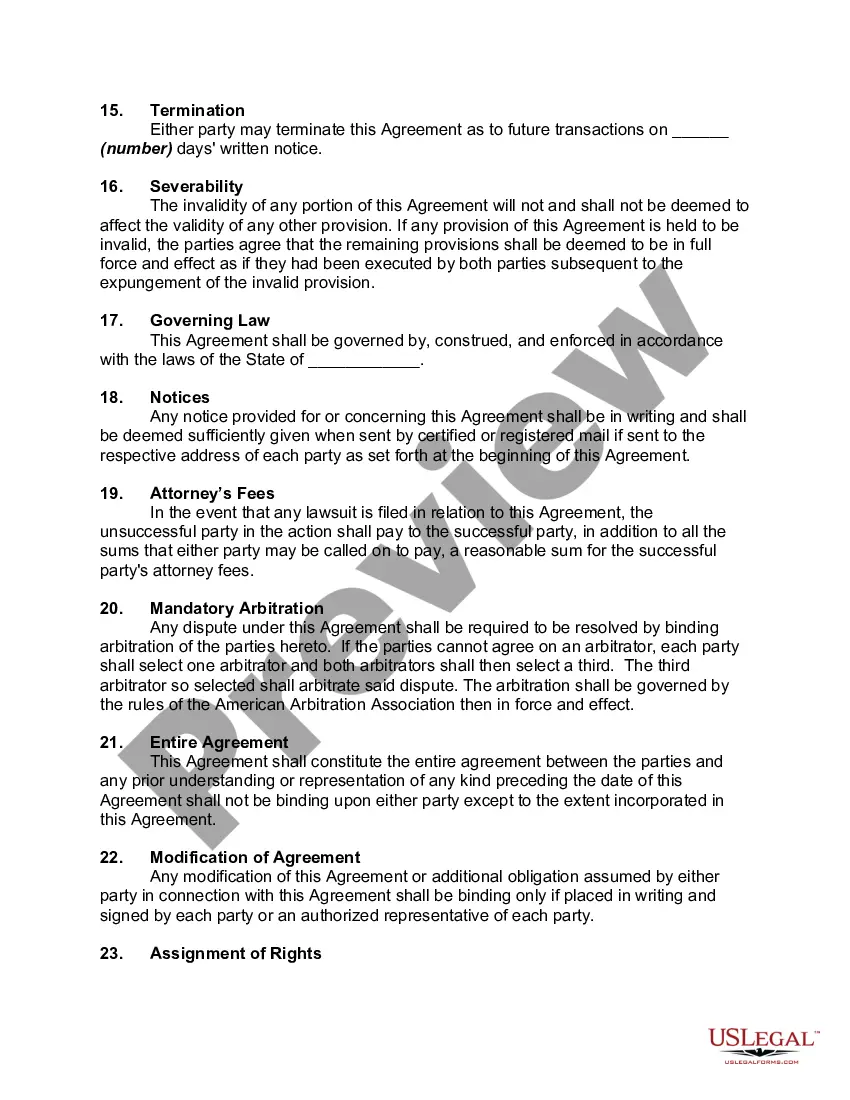
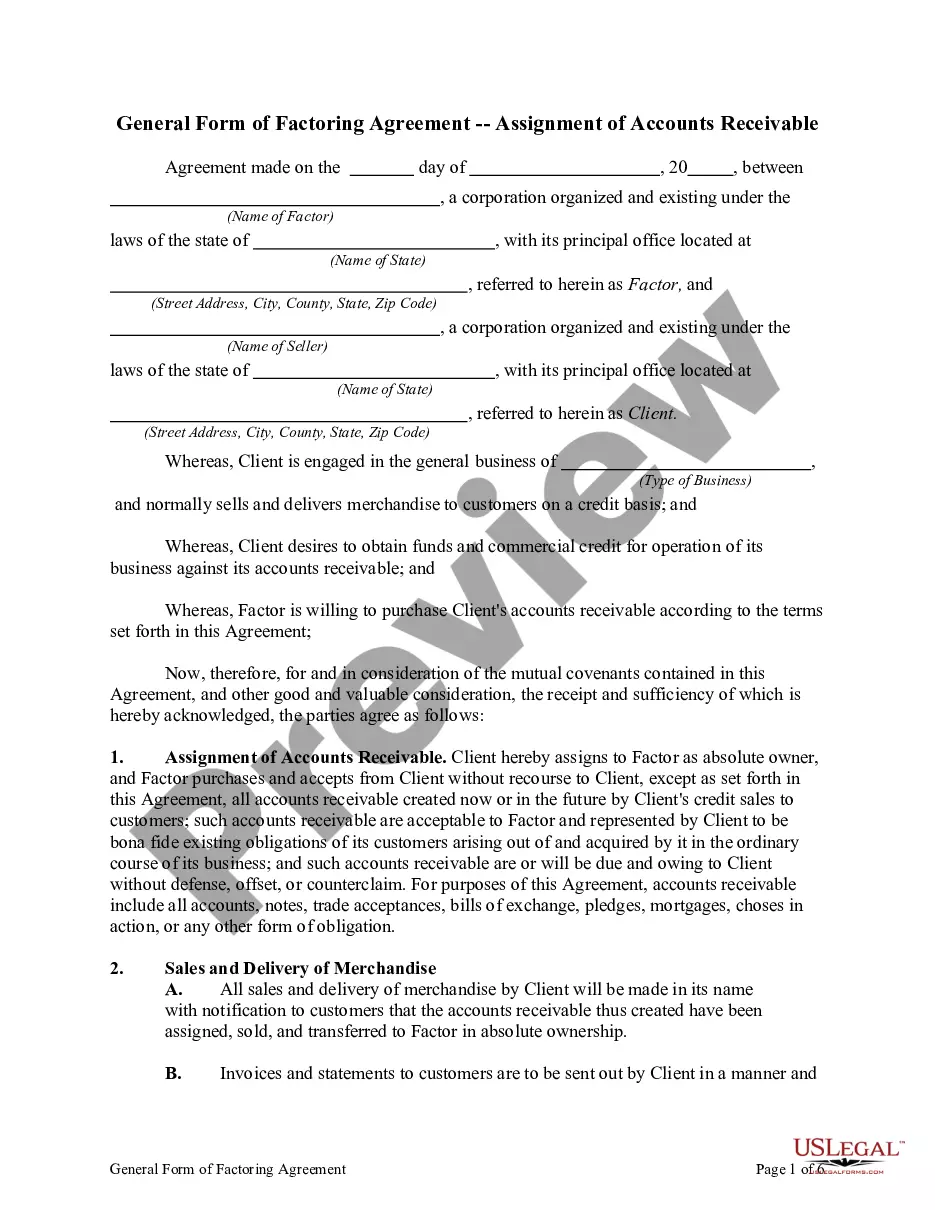
Banks may factor invoices for a number of reasons, but the main purpose is to provide financing to businesses that need working capital. For banks, funding invoices can be a way to generate income from lending to businesses without taking on the risks associated with traditional lending.
The Most Common Invoice Factoring Requirements A factoring application. An accounts receivable aging report. A copy of your Articles of Incorporation. Invoices to factor. Credit-worthy clients. A business bank account. A tax ID number. A form of personal identification.
Does Your Credit Score Matter for Invoice Factoring? No, your business credit score has no impact on the invoice factoring application and approval process. It also has no impact on the rates you will get.
Factoring companies typically DO NOT check your credit. A factor focuses on other aspects of your business, such as the number of your invoices and your customers' payment history. That's why factoring is such a great option for businesses with poor or little credit history.
Credit cards are the main example, as you'll typically have a document known as a cardholder agreement that lists details of the relationship. This is a different type of document than a promissory note, but it is important to realize it is still a legally enforceable document.
A cardholder agreement is a legal document outlining the terms under which a credit card is offered to a customer. Among other provisions, the cardholder agreement states the annual percentage rate (APR) of the card, as well as how the card's minimum payments are calculated.
FACTORING IN A CONTINUING AGREEMENT - It is an arrangement where a financing entity purchases all of the accounts receivable of a certain entity.
A cardholder agreement is a legal document outlining the terms under which a credit card is offered to a customer. Among other provisions, the cardholder agreement states the annual percentage rate (APR) of the card, as well as how the card's minimum payments are calculated.
Here's a breakdown of the basic invoice factoring requirements: Bank statements. Factoring application. Invoices you want to factor. Proof of delivery or service. Customer credit information. Accounts receivable aging report. Articles of incorporation or business registration.
Documents you will have to provide: Factoring application. Articles of Association or registered Amendments to the Articles of Association of your company. Annual report for the previous financial year. Financial report (balance sheet andf profit/loss statement) for the current year (for 3, 6 or 9 months, respectively)