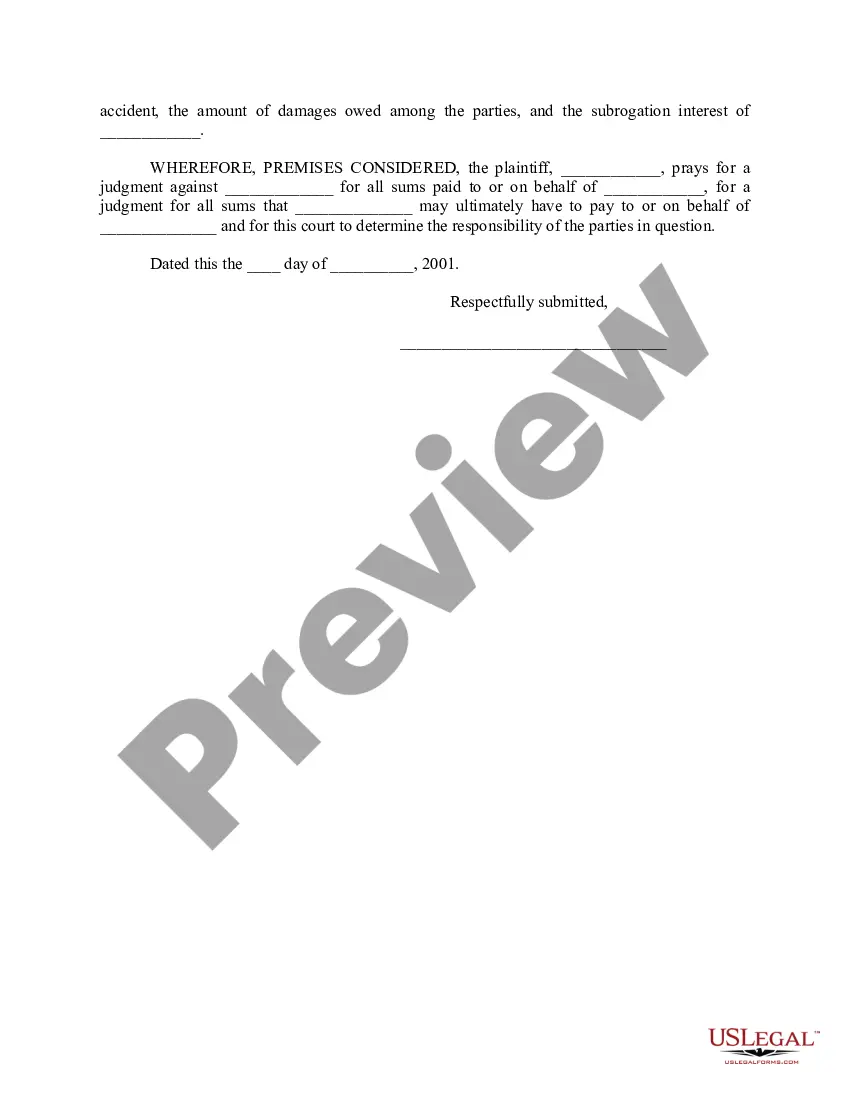
Subrogation Recovery In Michigan In Broward
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
Subrogation Limitation Statutes in Florida The statute of limitations for subrogation cases in Florida varies based on the nature of the claim. For negligence actions, House Bill 837 has reduced the statute of limitations from 4 years to 2 years.
Ways to Fight a Subrogation Claim for Property Damage Showing you are not at fault for the damage. Challenging the amount of the claim. Subrogation waiver. Technical violations of subrogation claims. Negotiate the claim.
The Anti-Subrogation Rule (“ASR”) is a common law defense to subrogation. It states that a subrogated insurance company standing in the shoes of its insured cannot bring a subrogation action against or sue its own insured.
When factoring comparative negligence and improper referrals, the recovery rate should be somewhere in the range of 85-90%. This requires adjusters properly identifying subrogation, assessing comparative negligence and pursuing only what they are entitled to.
Those states are: Arizona. Connecticut. Kansas. Missouri. New Jersey. New York. North Carolina. Virginia.
Subrogation allows your insurer to recoup costs (medical payments, repairs, etc.), including your deductible, from the at-fault driver's insurance company, if the accident wasn't your fault. A successful subrogation means a refund for you and your insurer.
When you file a claim, your insurer can try to recover costs from the person responsible for your injury or property damage. This is known as subrogation. For example: Your insurance company pays your doctor for your treatment following an auto accident that someone else caused.
When factoring comparative negligence and improper referrals, the recovery rate should be somewhere in the range of 85-90%. This requires adjusters properly identifying subrogation, assessing comparative negligence and pursuing only what they are entitled to.
Receiving a subrogation letter can seem problematic, but it does not have to be. Instead, reach out to your car accident attorney immediately to provide a copy of the letter and any information about the claims you made. If you received compensation from the insurance company, do not ignore this letter.
Subrogation recovery under the the Michigan No-Fault Act is possible, especially with a thorough understanding of this complex Act and the EXCEPTIONS it allows. These exceptions provide a treasure trove of subrogation opportunities.