Repossession Letter For Auto With Credit Card In Contra Costa
Description

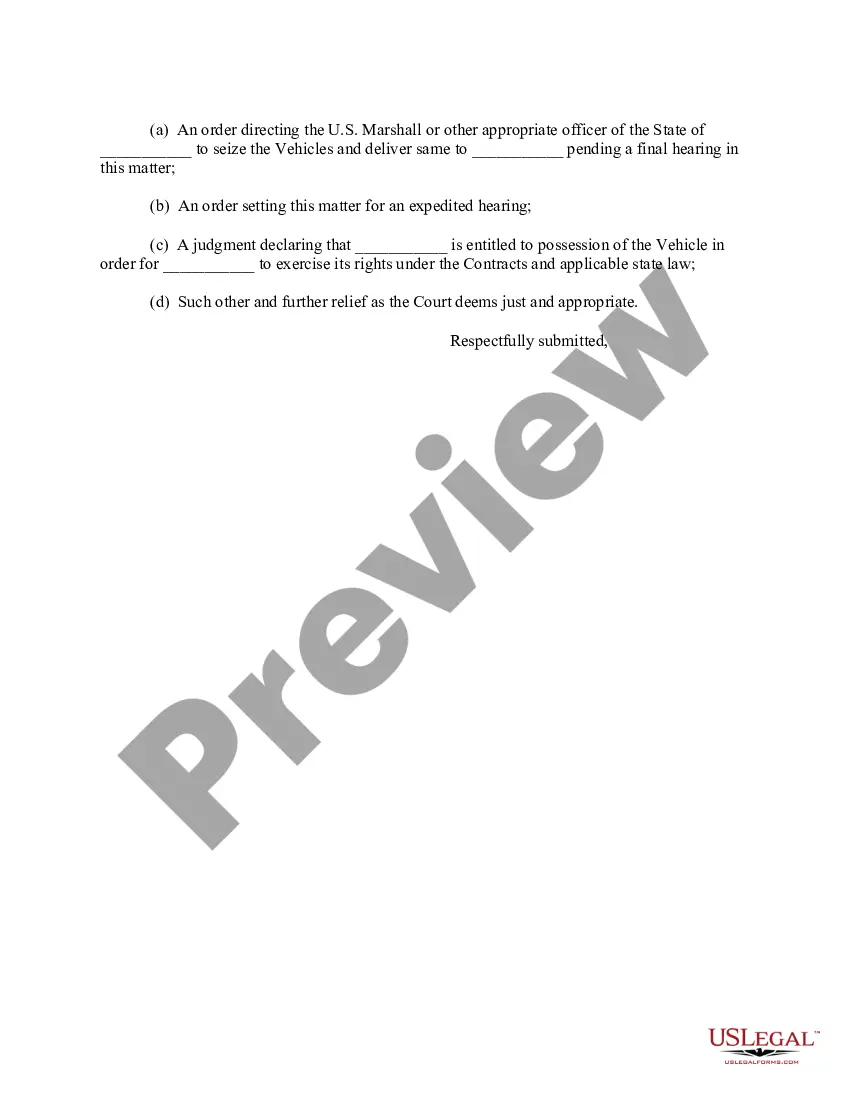
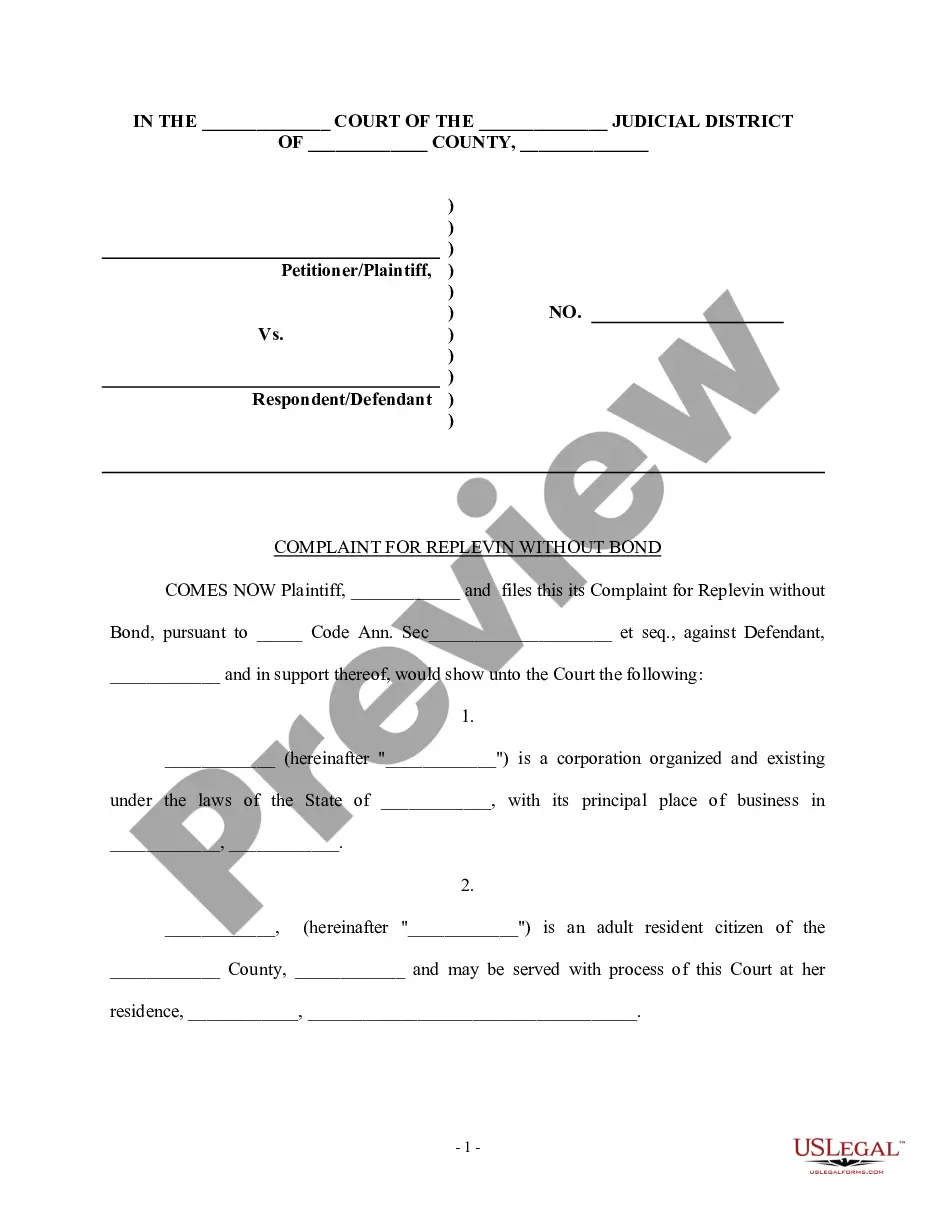
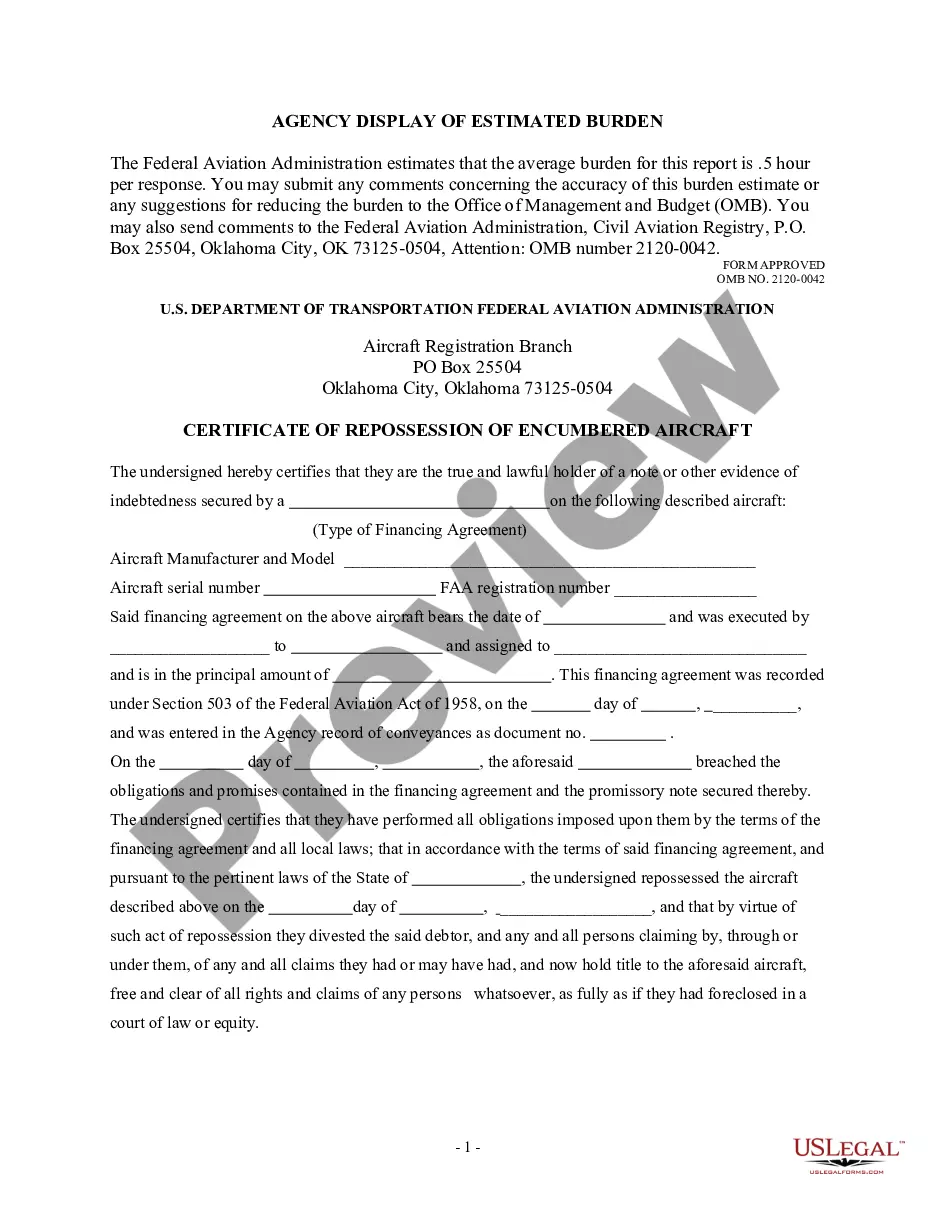
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?


Form popularity
FAQ
Debt collectors cannot repossess your possessions if the debt is unsecured, such as a credit card or student loan. In the case of secured debt, however, particularly auto loans, for which the car is collateral, failure to make payments can result in repossession of the vehicle.
How many payments you can miss before you can expect car repossession depends entirely on your lender and their leniency. Most lenders won't begin repossession until you've missed three or more payments.
Dear Borrower Name: You are hereby notified that your description of motor vehicle, year, make, model and VIN #, was lawfully repossessed on Date because you defaulted on your loan with Credit Union Name. The vehicle is being held at location address of vehicle. be sold at public sale.
In California, a consumer's vehicle can be taken from them if they miss payments on their loan or if they violate any terms of their agreement. This process is known as repossession and the creditor has the right to repossess the consumer's vehicle if it holds a valid security interest in it.
In California, a consumer's vehicle can be taken from them if they miss payments on their loan or if they violate any terms of their agreement. This process is known as repossession and the creditor has the right to repossess the consumer's vehicle if it holds a valid security interest in it.
Trying to reinstate or redeem your auto loan typically has to happen within a short time period, such as about two weeks, so you could have your car back soon after it's repossessed. You may have to wait longer, perhaps several months, if the car is sold at auction due to the time of the auction process.
Know the Repo Laws of Your State. The first thing to know about how to repo a car is you need to be aware of how repo laws stand within the jurisdictions where you will conduct business. Make Sure the Debtor Is in Default. Locate and Verify the Car. Choose the Method to Repossess. Do Not Breach the Peace.
What Happens If the Repo Agent Doesn't Find Your Car? But if you make it hard for the repo agent to get it, then the creditor may use another method to get the car back, called "replevin." Replevin can be just as costly as a repossession, if not more so.
Generally, cars are repossessed once payments are 90 days in default. Just don't expect lenders to give you a heads-up when the Repo Man will come calling. They typically contract that work out to towing services that specialize in snatching cars.
You can also use websites like Carfax, Auto Trader, Buy It Now, eBay and CarsDirect. All these websites provide information about repossessed cars.