Alimony Form For Taxes In Broward
Description
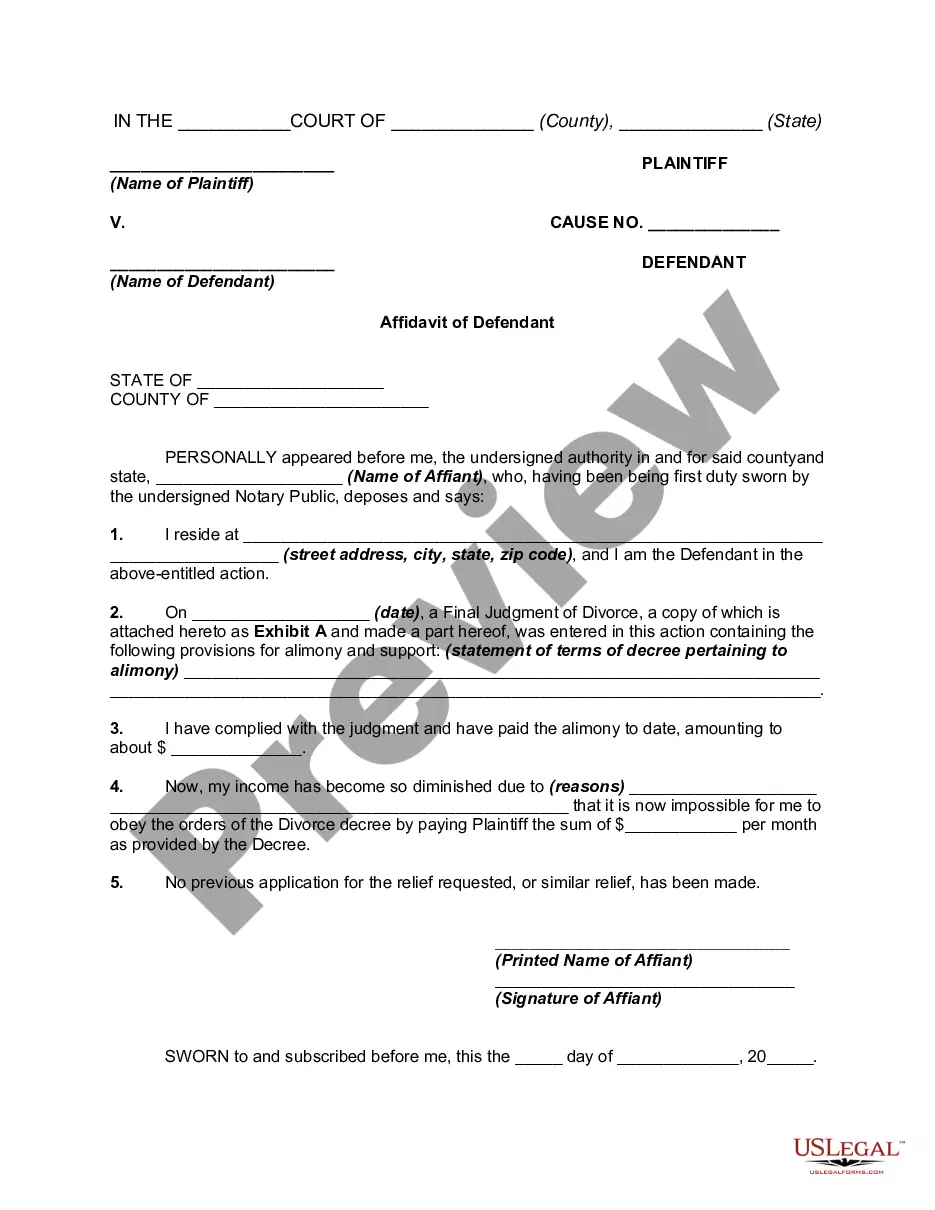
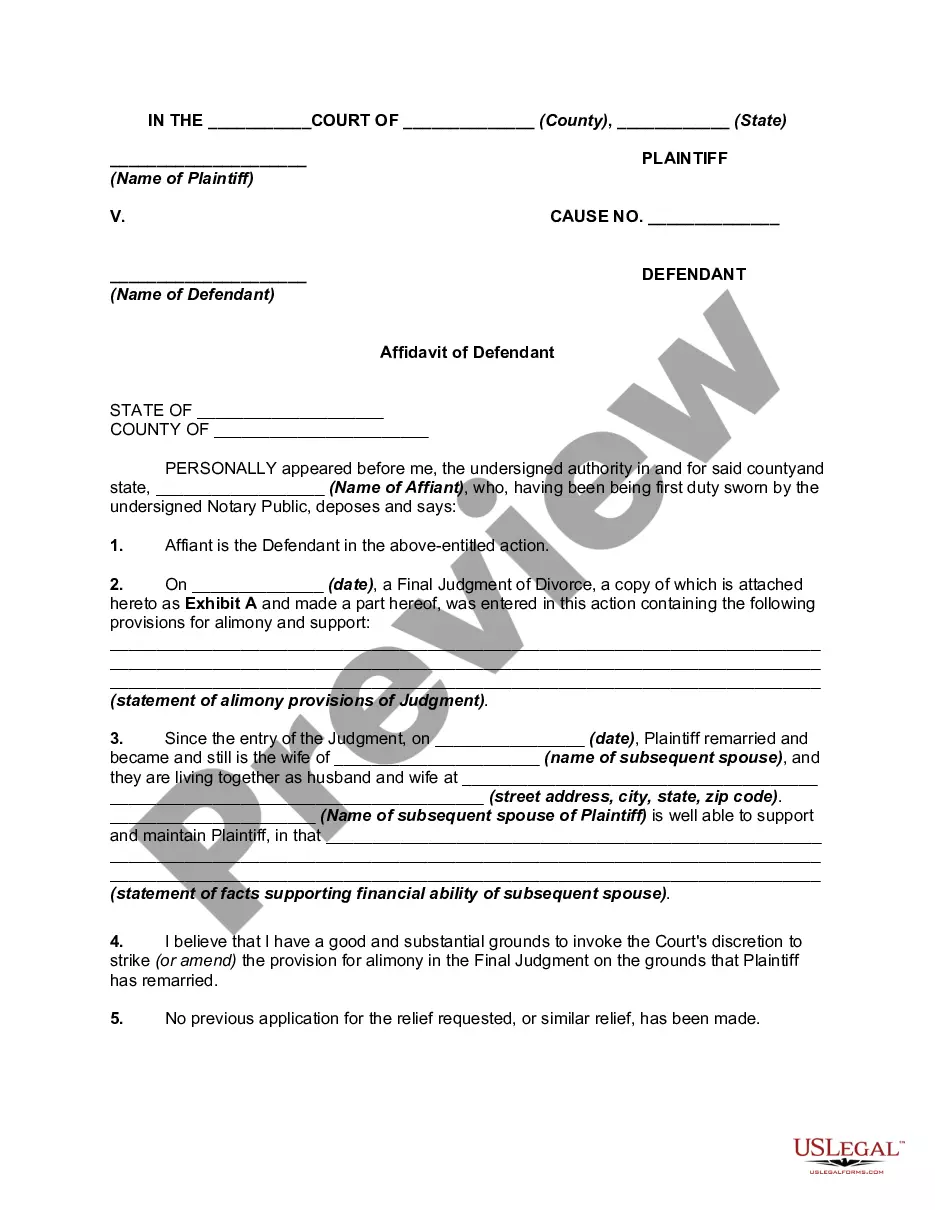
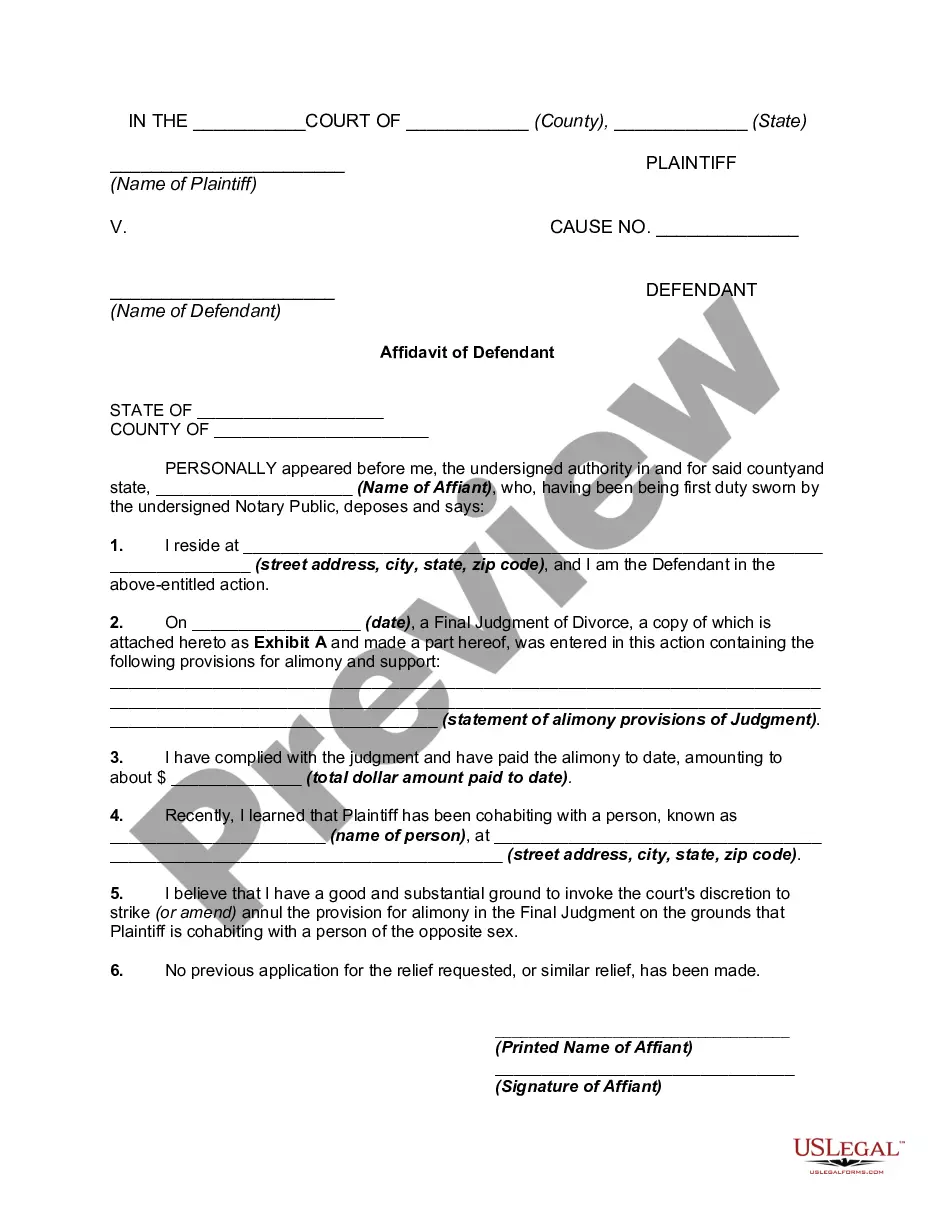
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
Reporting taxable alimony or separate maintenance Deduct alimony or separate maintenance payments on Form 1040, U.S. Individual Income Tax Return or Form 1040-SR, U.S. Tax Return for Seniors (attach Schedule 1 (Form 1040), Additional Income and Adjustments to Income PDF).
Beginning January 1, 2019, alimony or separate maintenance payments are not deductible from the income of the payer spouse, or includable in the income of the receiving spouse, if made under a divorce or separation agreement executed after December 31, 2018.
Other Above-the-Line Deductions Alimony: Payments that are not classified as child support and are made to a spouse pursuant to a divorce decree usually count as alimony. These payments are deductible from your gross income unless they are "made under a divorce or separation agreement executed after Dec.
§ 1.71-1 Alimony and separate maintenance payments; income to wife or former wife. (a) In general. Section 71 provides rules for treatment in certain cases of payments in the nature of or in lieu of alimony or an allowance for support as between spouses who are divorced or separated.
Report alimony received on Form 1040 or Form 1040-SR (attach Schedule 1 (Form 1040) PDF) or on Form 1040-NR, U.S. Nonresident Alien Income Tax Return (attach Schedule NEC (Form 1040-NR) PDF).
Bank statements or copies of checks deposited for the most recent 12 months or applicable period showing receipt of payments. Both must indicate the originating entity.
The person asking for alimony must show the court that he or she needs financial support, and that the other spouse has the ability to provide financial support.
After January 1, 2019, alimony is no longer taxable for the recipient, and the payer cannot deduct it. Tax Cuts and Jobs Act (TCJA): TCJA altered alimony taxation rules, making payments after January 1, 2019, nontaxable for recipients and nondeductible for payers, affecting agreements executed on or after that date.
Report alimony received on Form 1040 or Form 1040-SR (attach Schedule 1 (Form 1040) PDF) or on Form 1040-NR, U.S. Nonresident Alien Income Tax Return (attach Schedule NEC (Form 1040-NR) PDF).