Assumption and Amendment of Loan Documents
Understanding this form
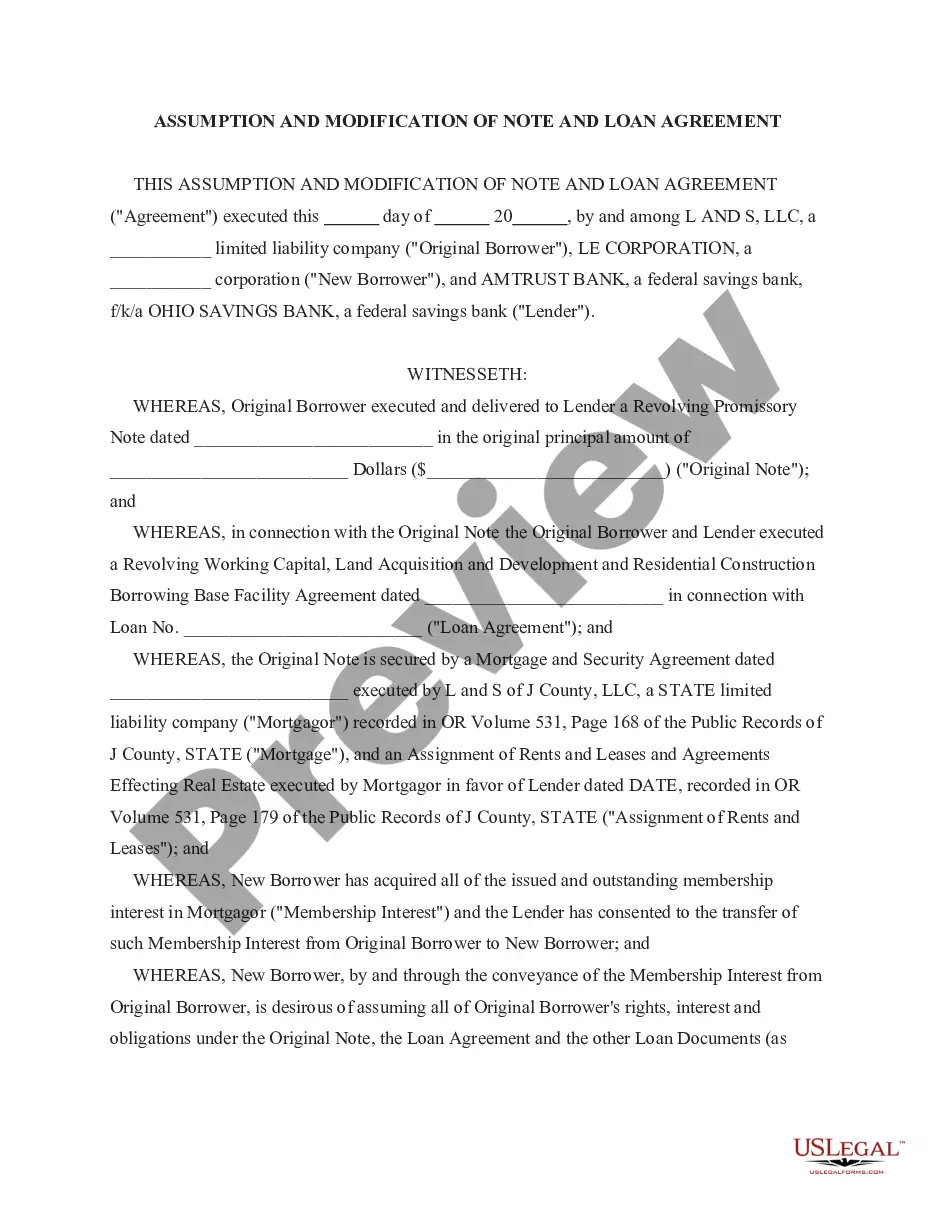
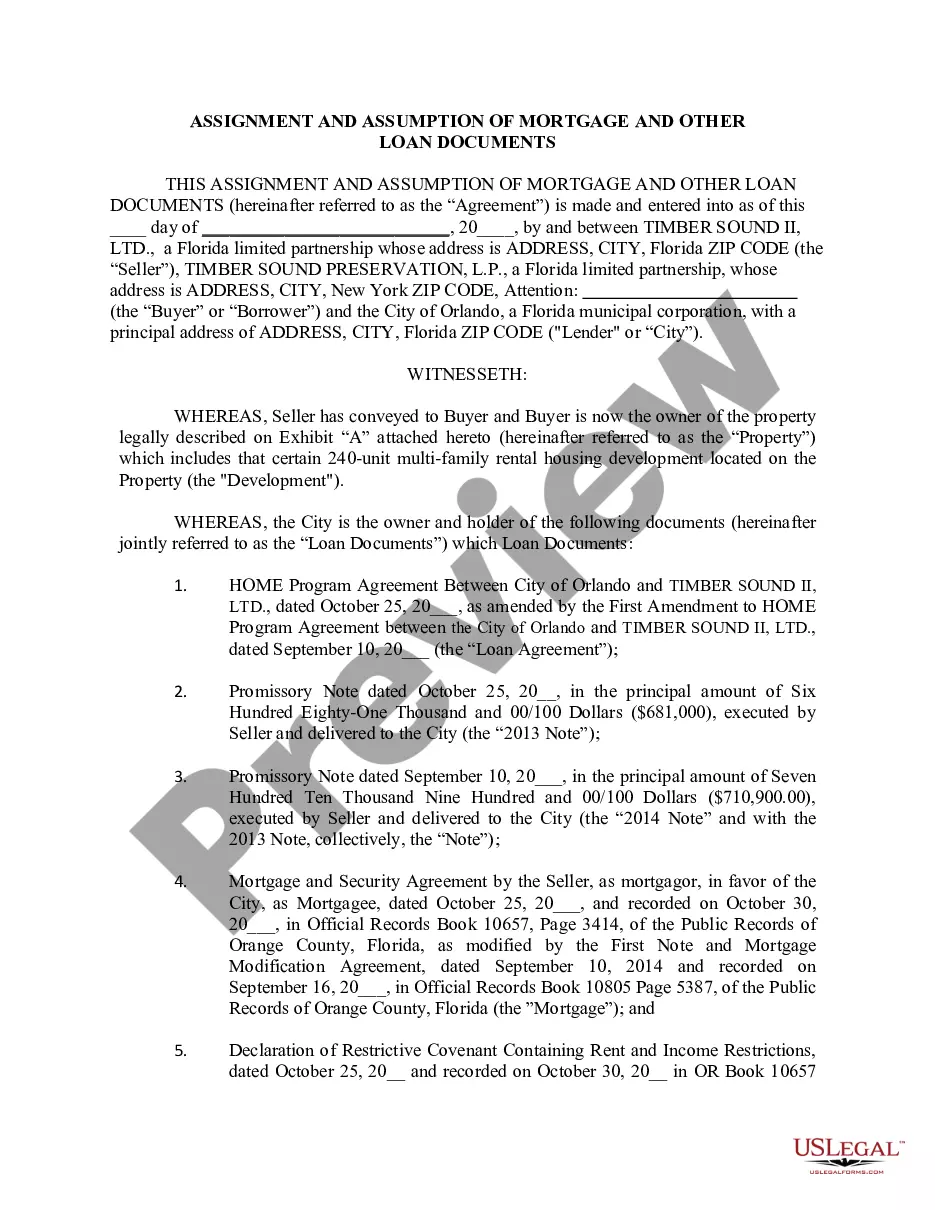
The Assumption and Amendment of Loan Documents is a legal agreement that allows a new borrower to assume the responsibility for an existing loan while simultaneously amending the loan terms. This form is essential for instances where a property is sold, transferring both the ownership and the debt associated with real estate. It differs from normal loan agreements by specifically addressing the transfer of obligations from the original borrower to a new one, ensuring clear terms for all parties involved.
Form components explained
- Borrower and Lender Information: Identification of the Borrower and Lender parties involved.
- Assumption Clause: Explicit consent from the Lender allowing the new Borrower to take over loan responsibilities.
- Amendment Sections: Details of any changes to the original loan terms, including interest rates and payment schedules.
- Property Description: Legal description of the property associated with the loan.
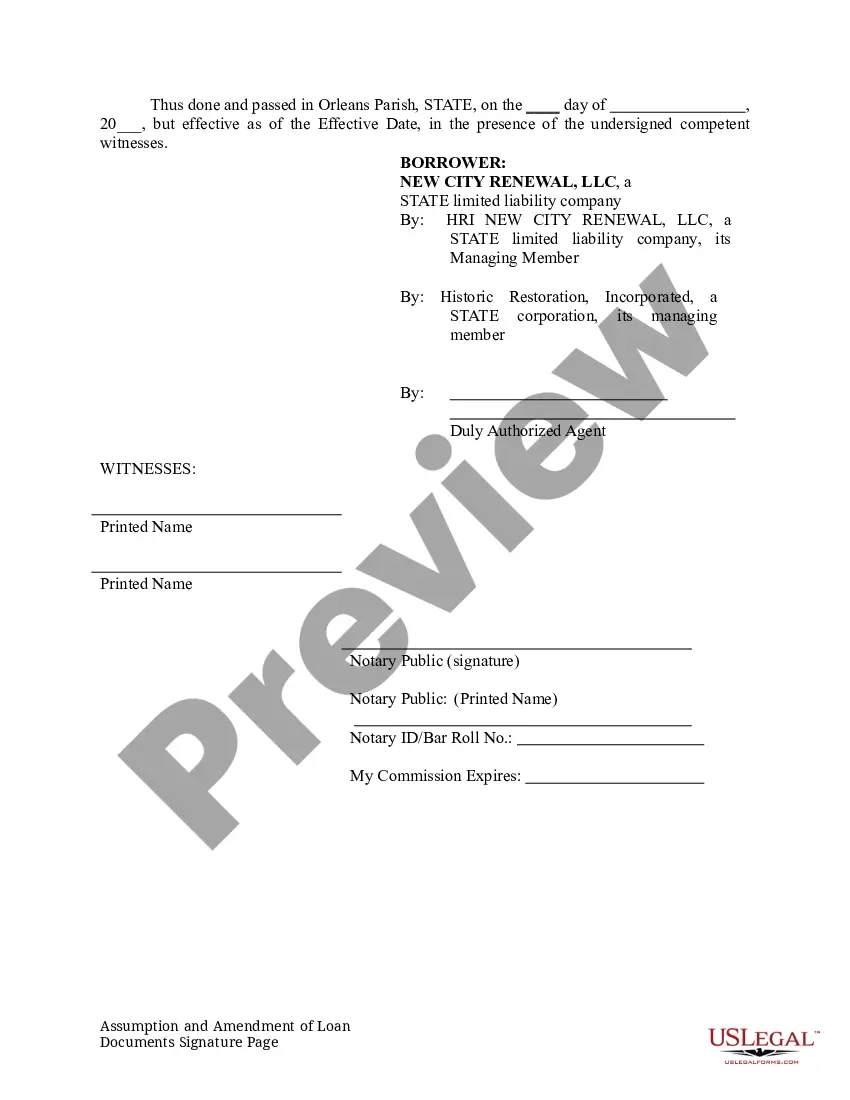
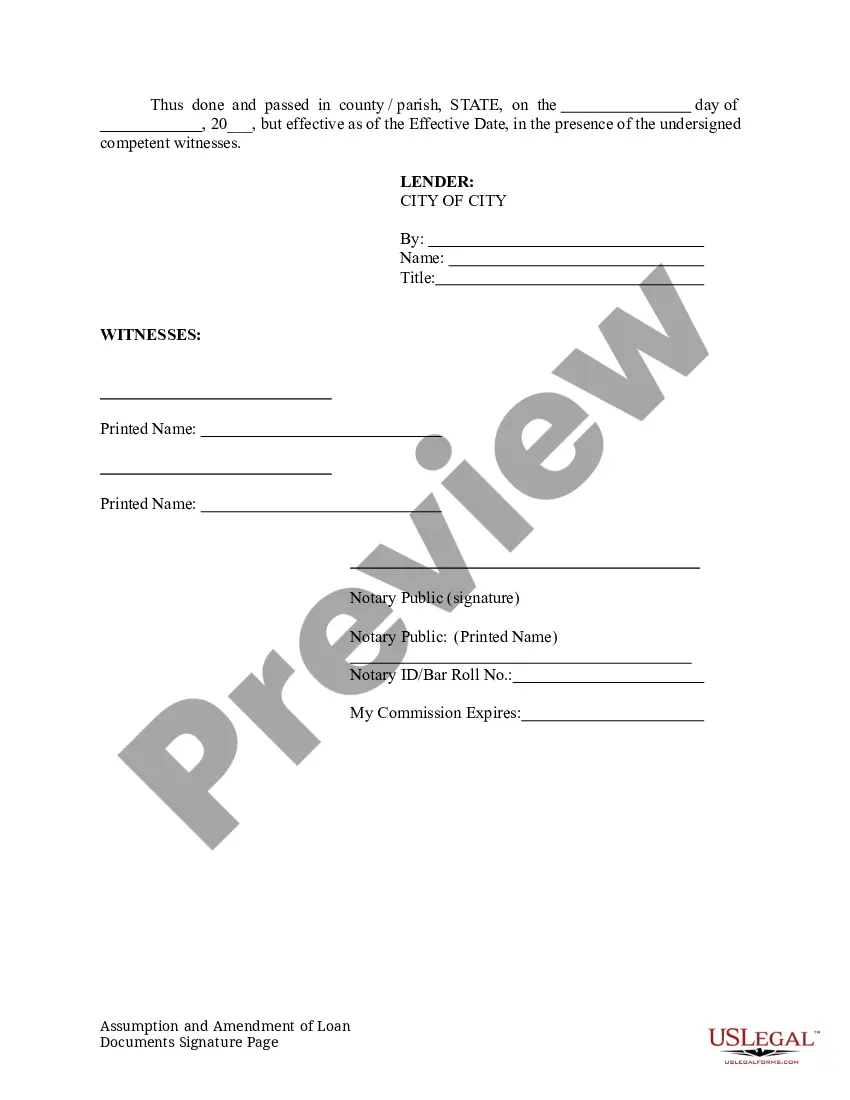
- Notary and Witness Signatures: Requirements for authentication of the agreement through signatures.
Common use cases
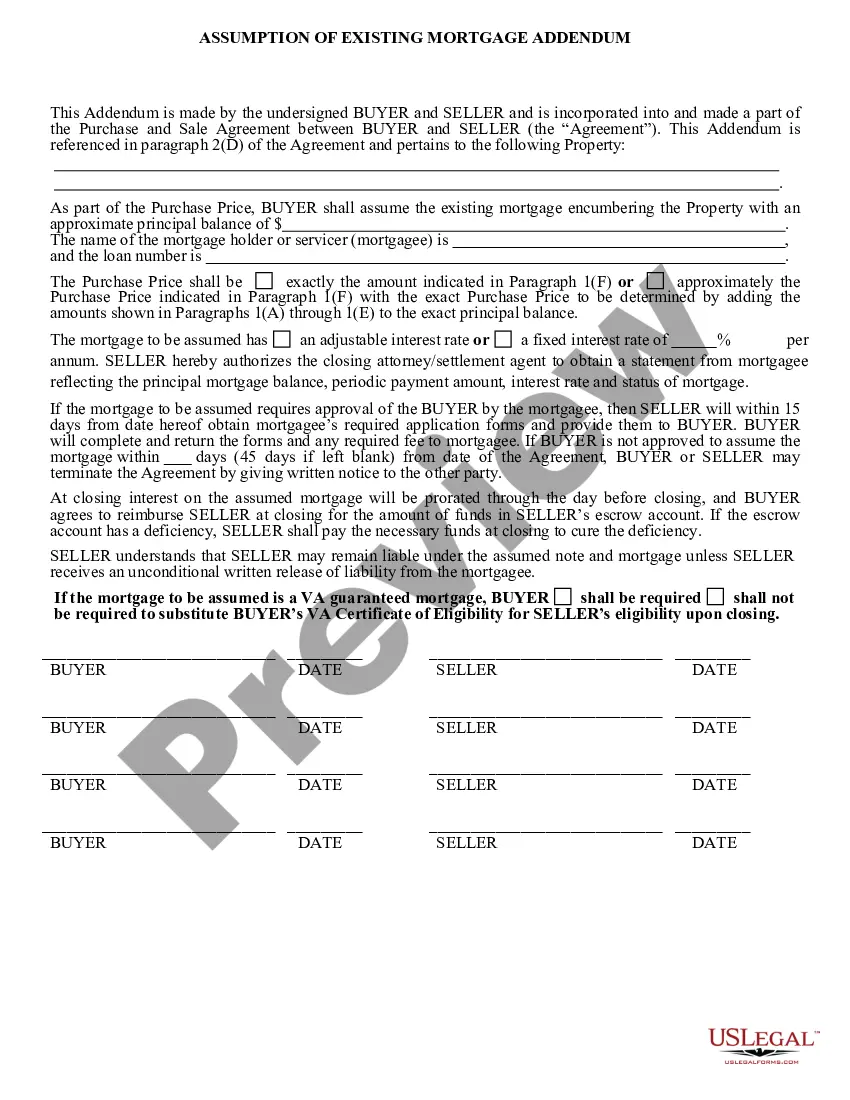
This form is typically used when a property is sold, and the buyer wishes to take over an existing mortgage from the seller. It is necessary when the original borrower is no longer able to fulfill their loan obligations, and the new borrower accepts responsibility for the outstanding loan. This agreement ensures that all parties are aware of the updated terms and conditions associated with the loan.
Who can use this document
- Homebuyers who are assuming an existing mortgage on a property.
- Property owners looking to transfer their loan obligations to a new party.
- Lending institutions that require formal documentation of borrower assumption and amendment.
- Real estate attorneys representing clients in loan assumption scenarios.
How to prepare this document
- Identify the parties: Fill in the names and addresses of the Borrower and Lender.
- Enter the effective date: Specify when the agreement takes effect.
- Outline the property details: Provide a legal description of the property involved.
- Sign and date: Ensure that all parties sign, including a notary public as necessary for verification.
- Review amendments: Clearly state any changes to the loan terms, including the new principal amount or interest rate.
Notarization guidance
Yes, this form must be notarized to be legally valid. US Legal Formsâ online notarization process provides a secure and reliable way to complete the necessary documentation through a virtual video call with a licensed notary, available 24/7.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Mistakes to watch out for
- Failing to properly identify all parties involved in the agreement.
- Omitting significant details in the amendment clauses that could lead to misunderstandings.
- Not including a legal description of the property, which is essential for clarity.
- Neglecting to obtain the necessary signatures and notarization, making the document unenforceable.
Benefits of completing this form online
- Convenient and quick access to legal forms without visiting an attorney.
- Editable templates allow for customization to fit specific needs.
- All forms are drafted by licensed attorneys ensuring legal compliance.
- Instant downloads mean faster processing for real estate transactions.
Looking for another form?
Form popularity
FAQ
A mortgage loan assumption allows you to buy a home by taking over (or "assuming") the owner's mortgage instead of getting a new mortgage. This has advantages for homebuyers and sellers. Homebuyers can get a mortgage with a lower interest rate than may be currently available on the market.
An assumable mortgage allows a homebuyer to assume the current principal balance, interest rate, repayment period, and any other contractual terms of the seller's mortgage. Rather than going through the rigorous process of obtaining a home loan from the bank, a buyer can take over an existing mortgage.
Buyer shall receive a credit at Closing in an amount equal to the sum of the unpaid principal balance of the Loan, and any interest, default interest, or other sum that is accrued, due and/or payable to Existing Lender on the Closing Date.
A loan assumption agreement is an agreement between a lender, original borrower, and a new borrower, where the new borrower agrees to assume responsibility for the debt owed by original borrower. These agreements are commonly seen in mortgages and real estate.
What is a Loan Amendment? A loan amendment is a legally bound modification to the terms and conditions of an already-existing loan agreement. If a lender or a borrower needs changes made to the original loan agreement, they will use a loan amendment to outline the terms and conditions of those modifications.
An assumption clause is a provision in a mortgage contract that allows the seller of a home to pass responsibility for the existing mortgage to the buyer of the property. In other words, the new homeowner assumes the existing mortgage and?along with it?ownership of the property that secures the loan.
An assignment and assumption agreement is used after a contract is signed, in order to transfer one of the contracting party's rights and obligations to a third party who was not originally a party to the contract.
A loan assumption agreement is an agreement between a lender, original borrower, and a new borrower, where the new borrower agrees to assume responsibility for the debt owed by original borrower. These agreements are commonly seen in mortgages and real estate.