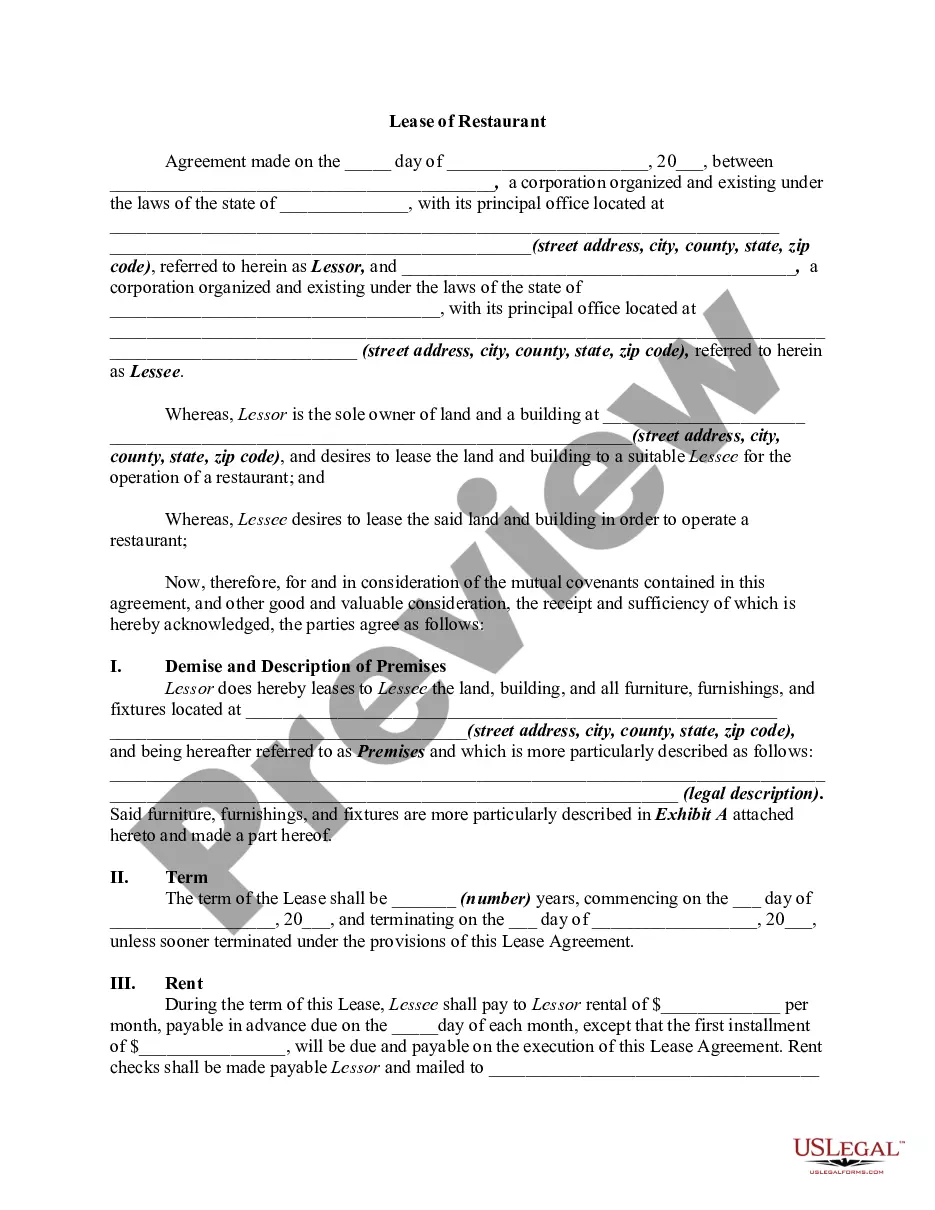
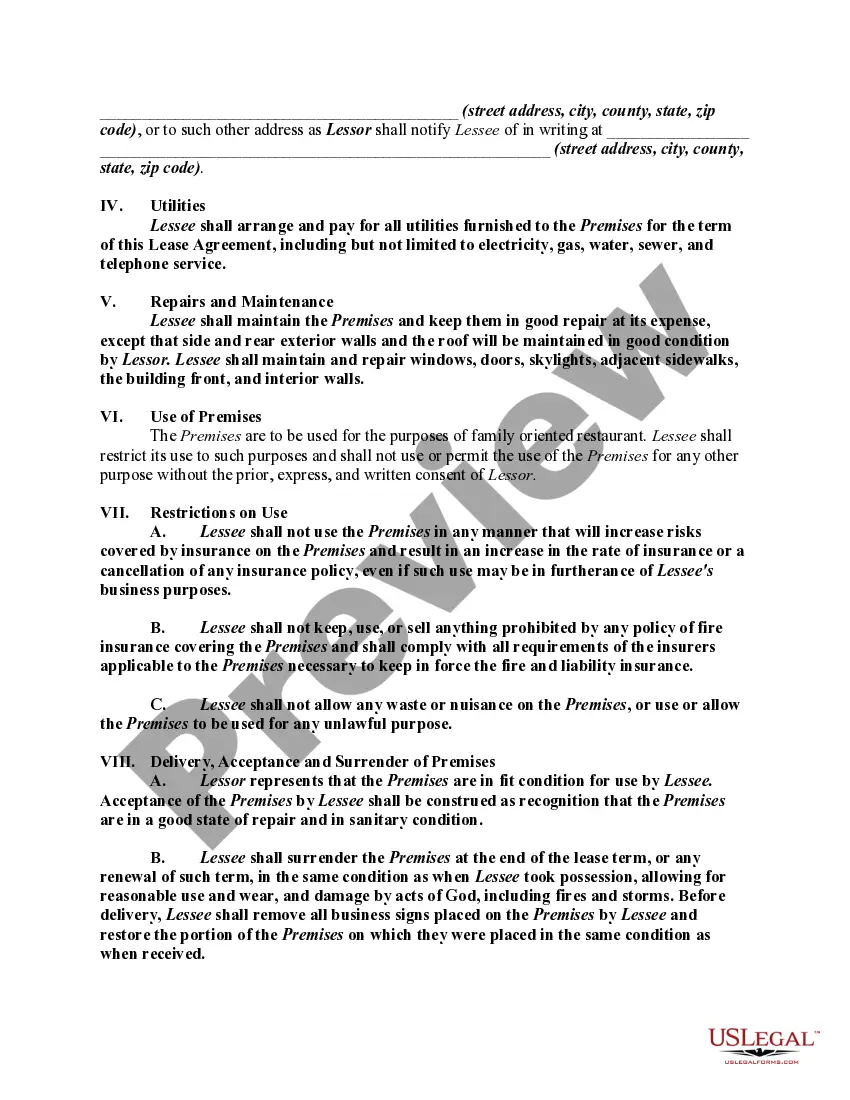
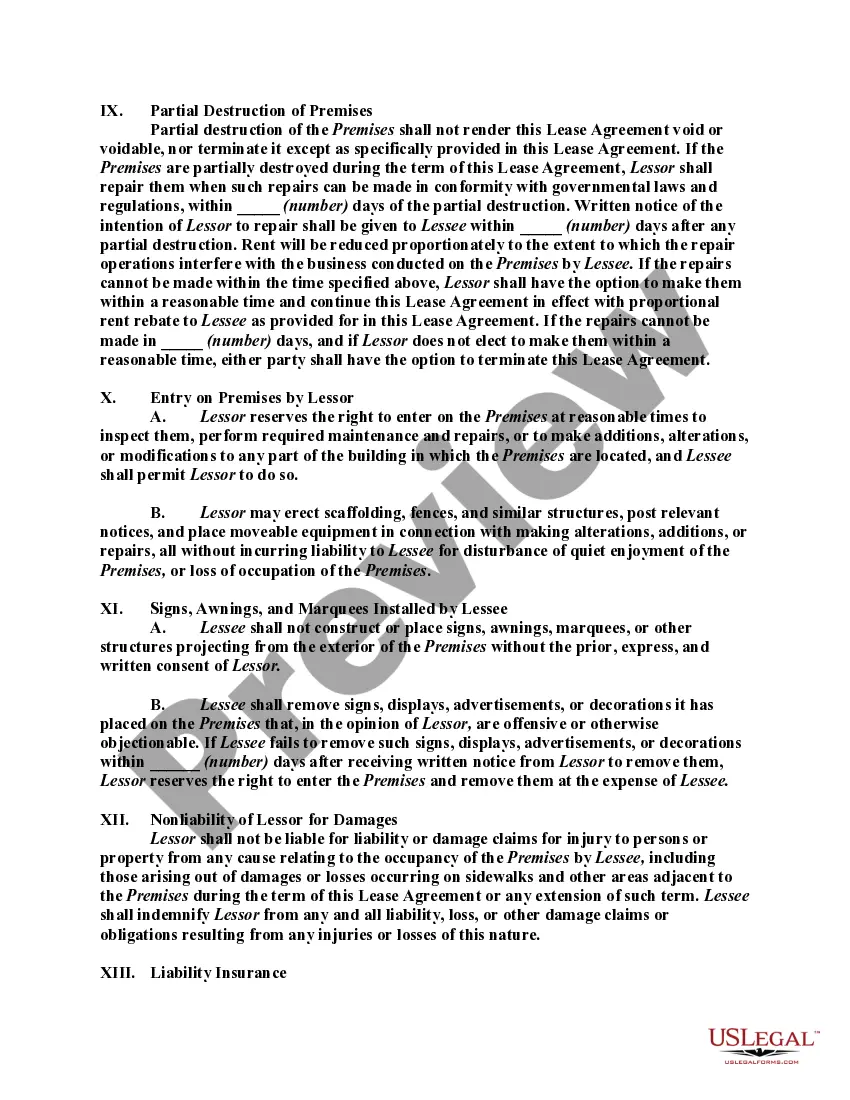
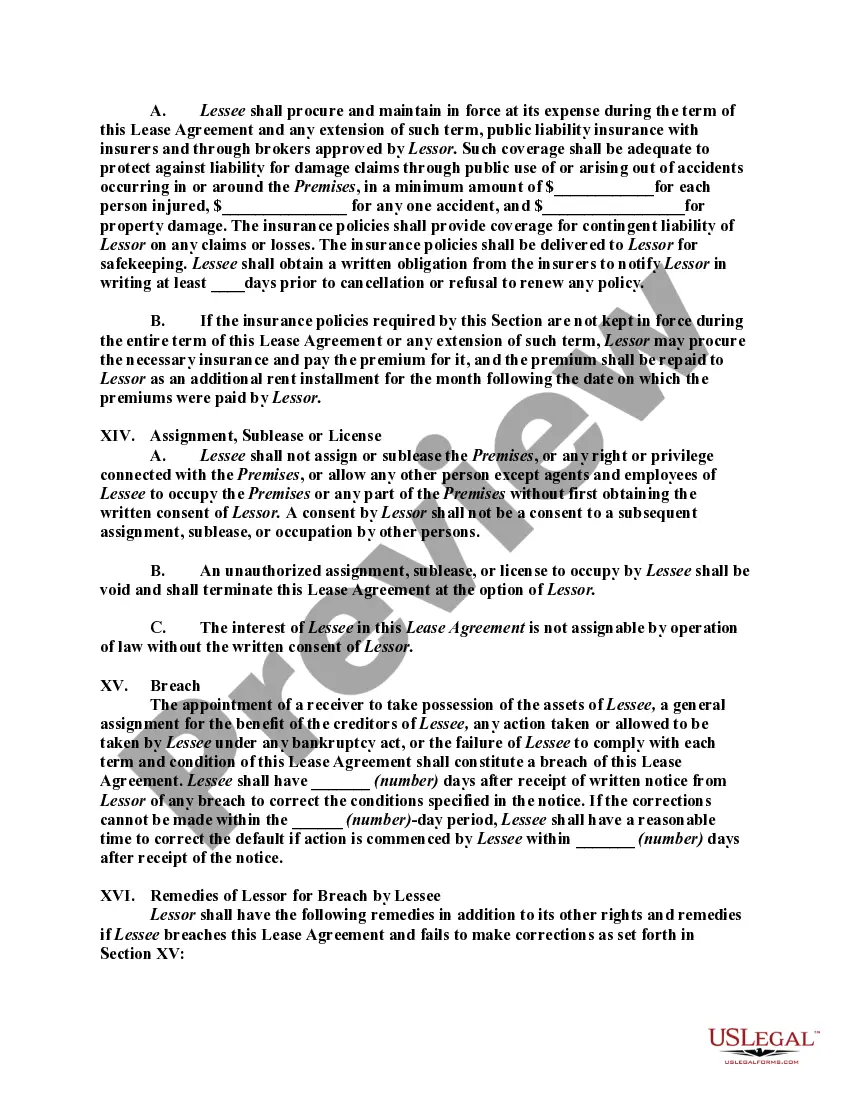
Virgin Islands Lease of Restaurant
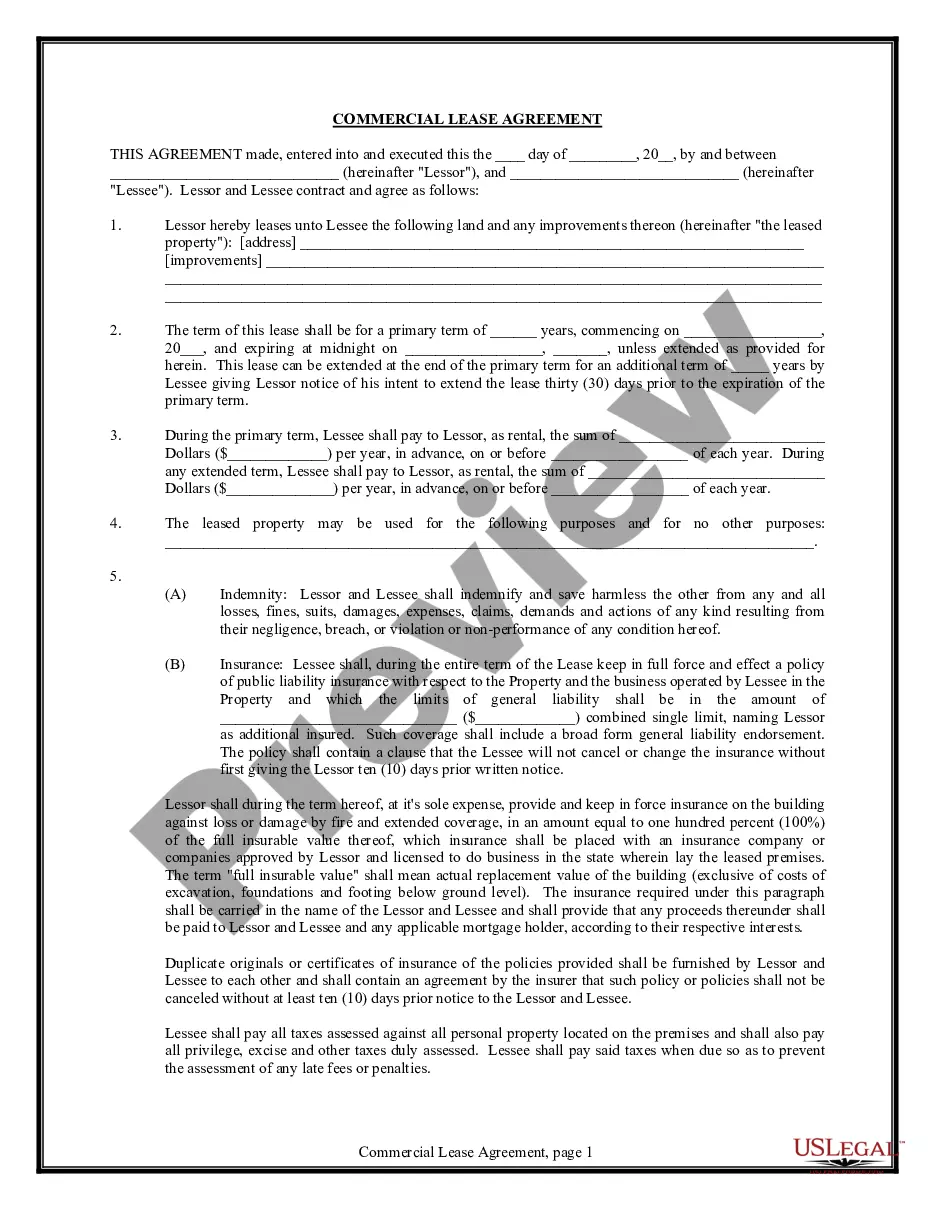
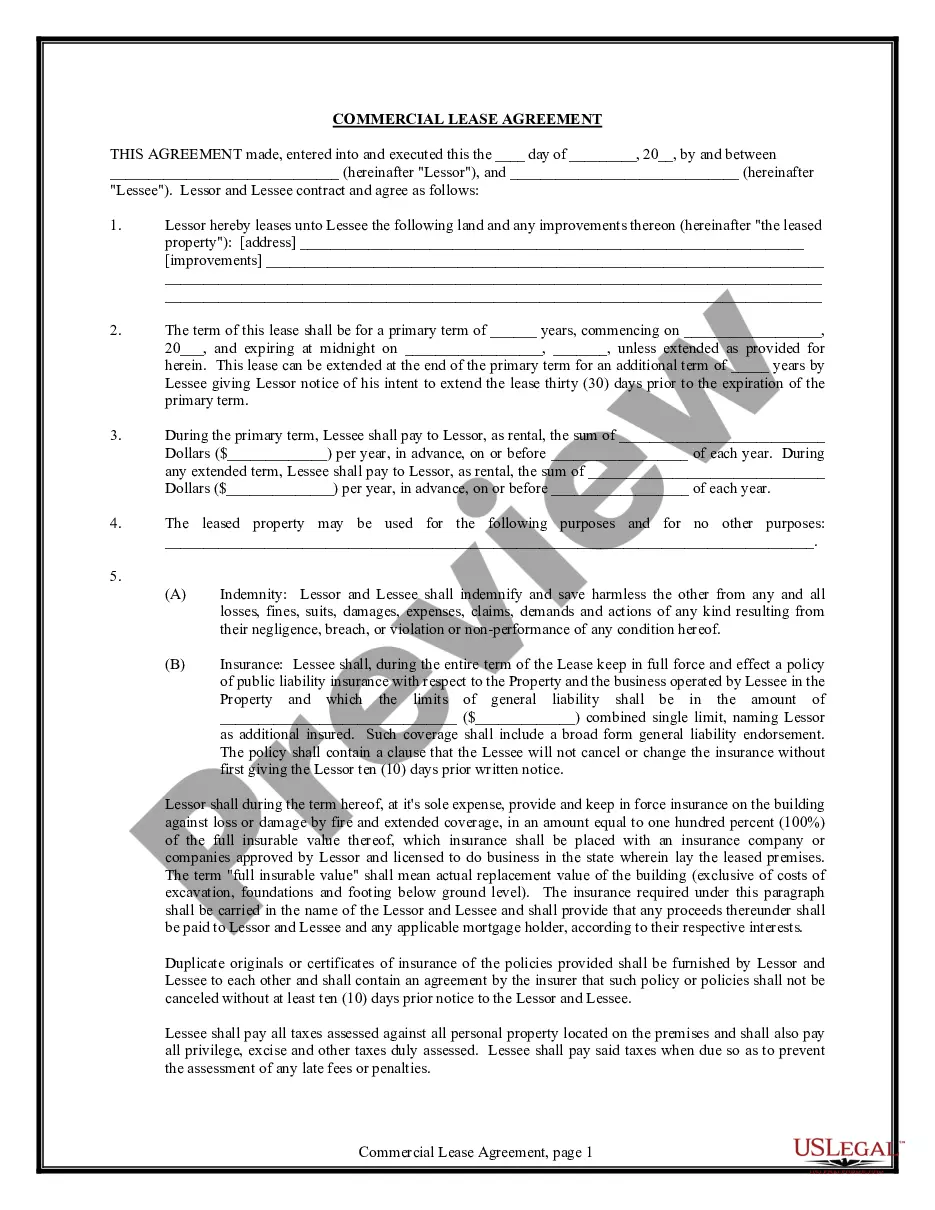
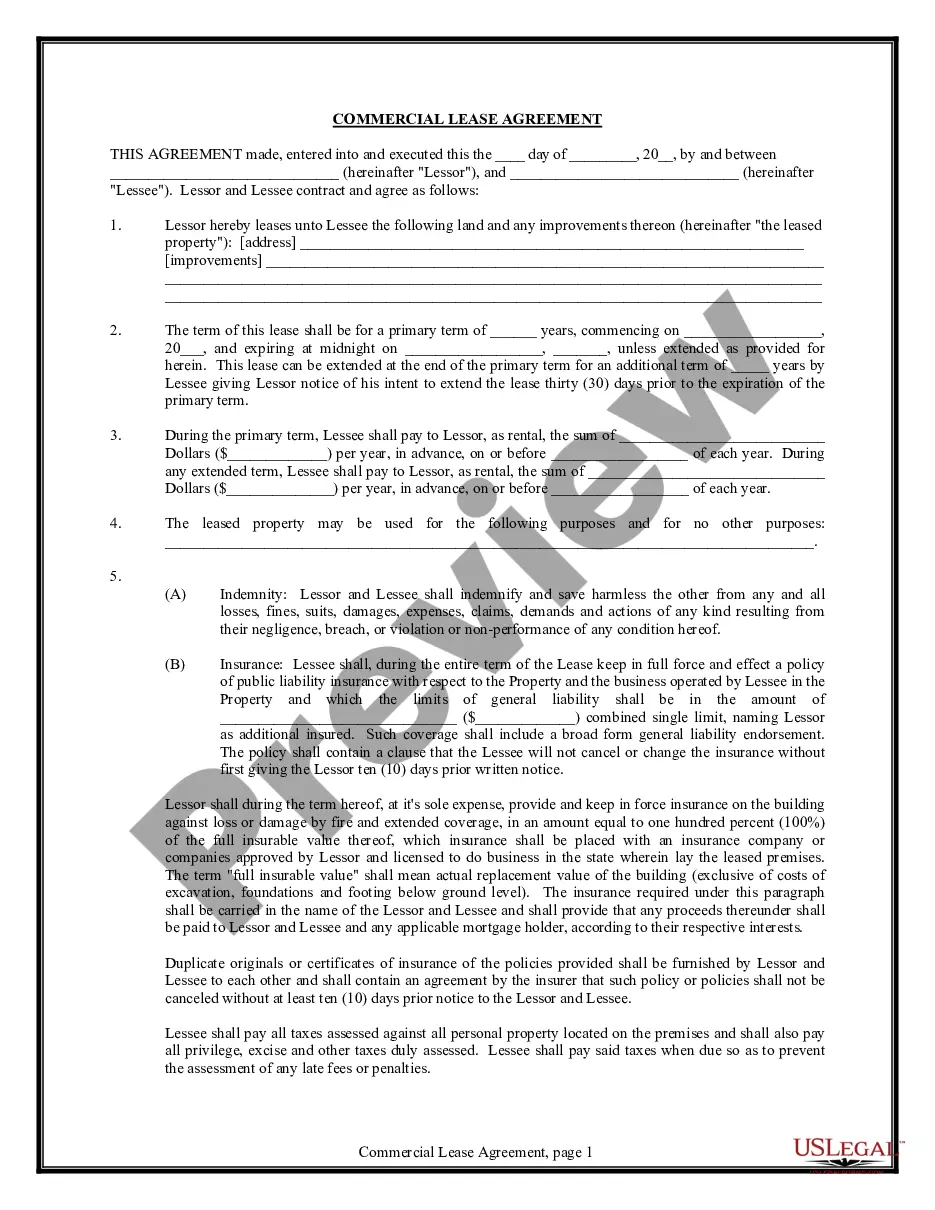
Description
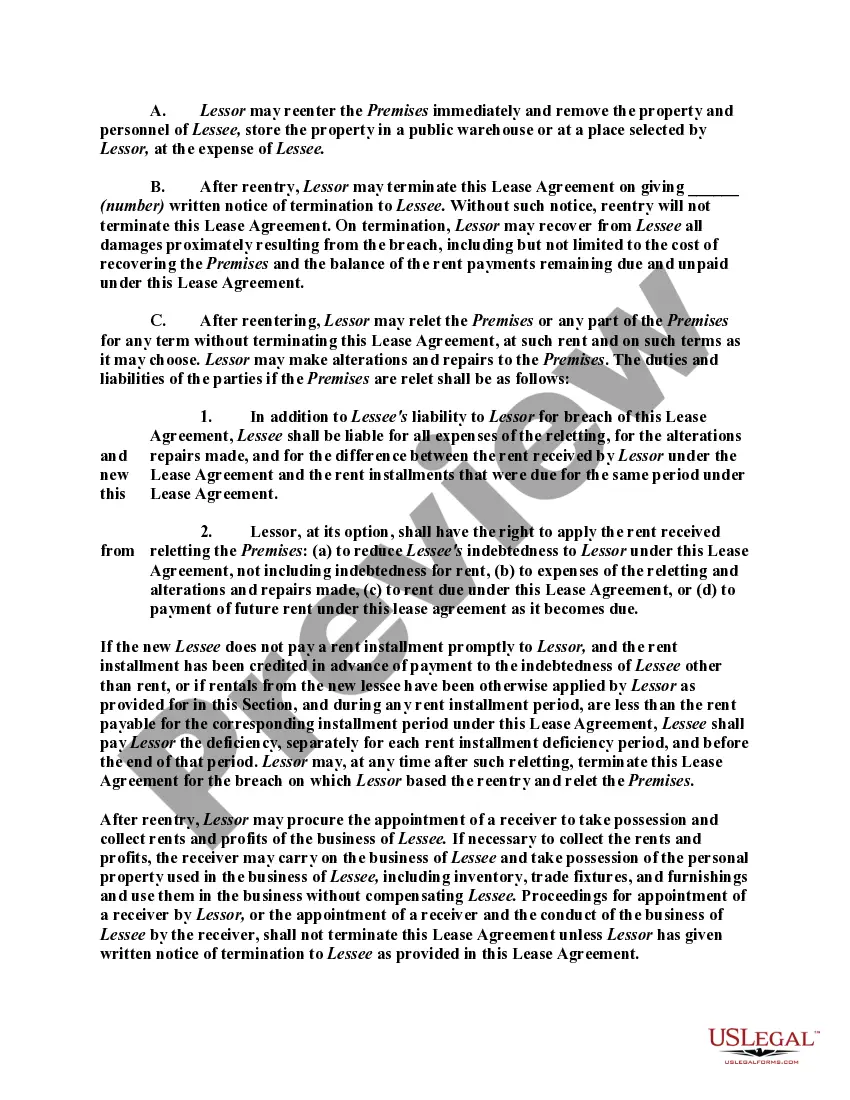
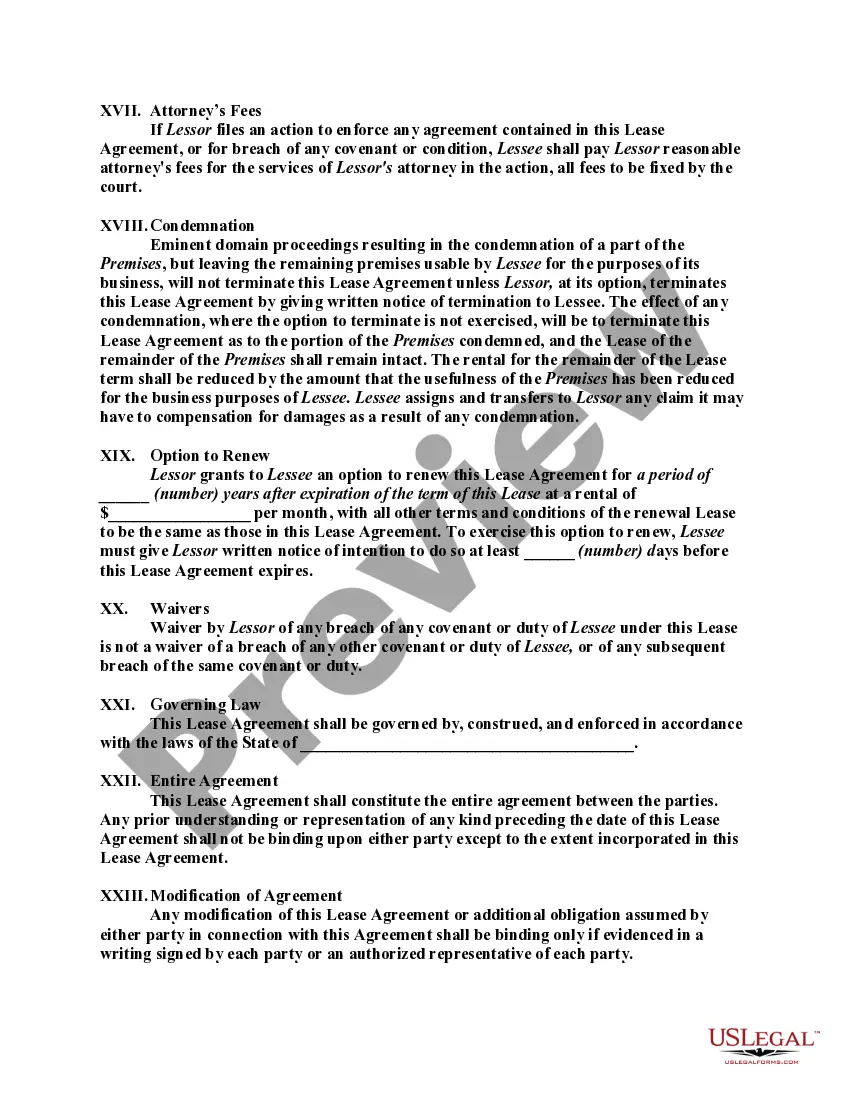
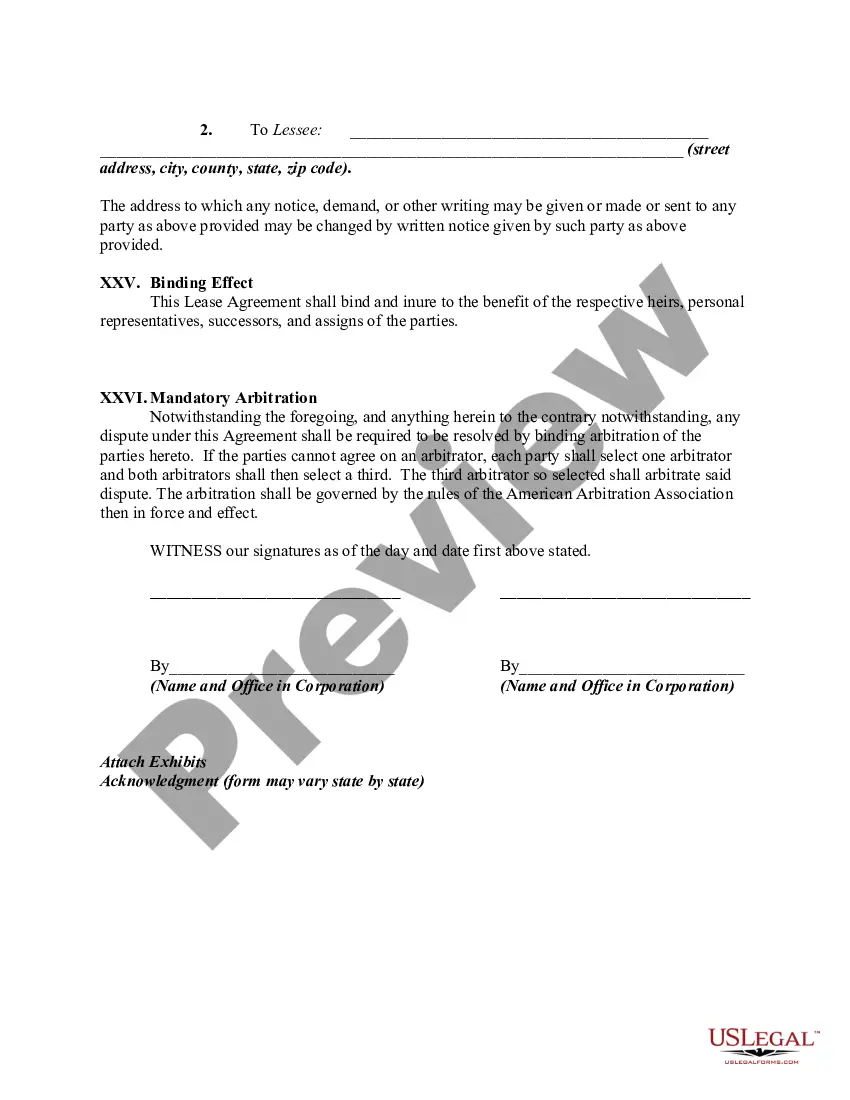
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
How to fill out Lease Of Restaurant?
It is feasible to spend hours online attempting to discover the legal document format that complies with the state and federal requirements you require.
US Legal Forms offers thousands of legal documents that have been assessed by experts.
You can acquire or create the Virgin Islands Lease of Restaurant through the service.
If available, use the Preview option to review the document format as well.
- If you have a US Legal Forms account, you can Log In and then click the Download button.
- Subsequently, you can complete, modify, print, or sign the Virgin Islands Lease of Restaurant.
- Every legal document format you buy is yours forever.
- To obtain another copy of any purchased form, visit the My documents tab and click the respective option.
- If you are using the US Legal Forms website for the first time, follow the simple instructions below.
- First, ensure you have selected the correct document format for the county/city of your choice.
- Check the form description to confirm you have chosen the right document.
Form popularity
FAQ
The Virgin Islands are sometimes referred to as a tax haven due to their favorable tax structures and incentives for businesses. This designation can be particularly advantageous for those entering into a Virgin Islands Lease of Restaurant, as it allows for greater financial benefits. However, it's important to understand the legal obligations that come along with operating in the Islands. Utilizing platforms like uslegalforms can assist you in navigating regulations and maximizing your benefits.
Yes, businesses operating in the Virgin Islands, including those with a Virgin Islands Lease of Restaurant, must file taxes locally. This includes both federal and local tax obligations, and understanding the requirements is crucial for compliance. Failure to file can lead to penalties, so staying informed about the regulations is essential. Regularly consulting a tax professional will help ensure you are meeting all necessary obligations.
The Virgin Islands provide numerous tax benefits that attract business owners from various industries. Notably, the economic development programs offer significant incentives, such as lower business taxes and potential property tax exemptions. If you pursue a Virgin Islands Lease of Restaurant, you can utilize these benefits to enhance your restaurant's profitability and stability. Such advantages make the Islands an appealing location for entrepreneurs.
In the US Virgin Islands, the rental tax typically applies to leased properties, including those for restaurant use. The rental income generated from a Virgin Islands Lease of Restaurant is subject to this tax, which is part of the overall tax structure in the territory. It's crucial to consult with a local tax advisor to understand your obligations and ensure compliance. Being informed will help you focus on your business growth without fear of unexpected costs.
The Virgin Islands offer several attractive tax breaks for businesses. When you enter into a Virgin Islands Lease of Restaurant, you can benefit from reduced corporate income taxes and exemptions on certain kinds of business activities. Additionally, businesses in the territory can take advantage of tax incentive programs that promote investment and job creation. This makes the Islands an appealing option for restaurateurs seeking to maximize their profits.
term lease gives you the benefit of being able to relocate if you need more space, but a longterm lease will ensure that you don't have to take on the expense of moving shortly after getting settled. Typically, landlords will offer you a better deal if you lock in to a longterm lease.
A lease is a contract outlining the terms under which one party agrees to rent an assetin this case, propertyowned by another party. It guarantees the lessee, also known as the tenant, use of the property and guarantees the lessor (the property owner or landlord) regular payments for a specified period in exchange.
Break clauses A break clause is written into the commercial lease from the outset and allows a Tenant (and even a Landlord) to end a lease early by serving a notice on the other party.
The three most common types of leases are gross leases, net leases, and modified gross leases.The Gross Lease. The gross lease tends to favor the tenant.The Net Lease. The net lease, however, tends to favor the landlord.The Modified Gross Lease.
Commercial tenants should be able to spend 5% to 10% of their gross sales per foot on rent. Your gross sales divided by the location's square footage will give you sales per square foot. For example, you estimate your business will make $300,000 per year in total sales, and you are looking at a 1,500 square foot space.