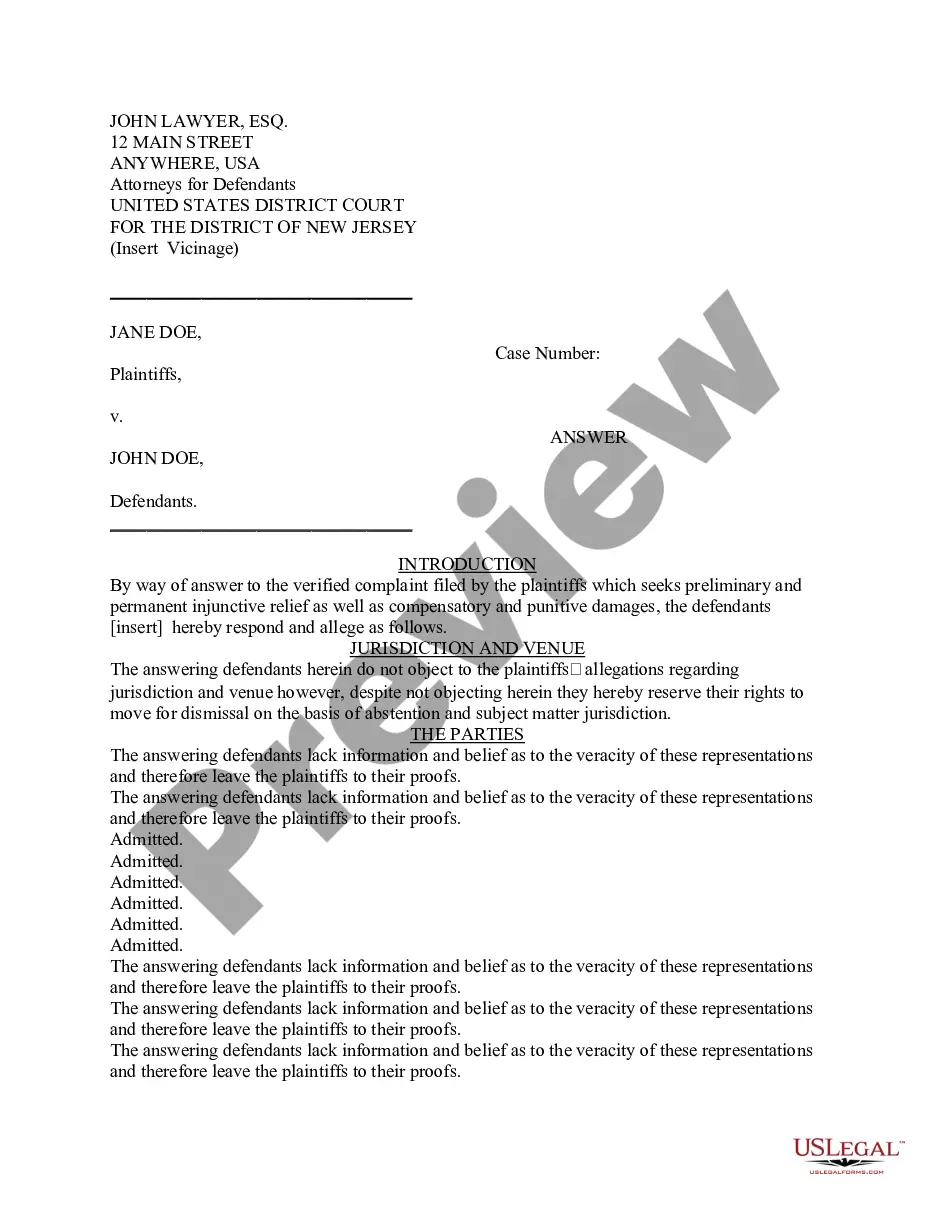
TAX EVASION / 26 U.S.C. Sec. 7201
Understanding this form
The Tax Evasion form, pursuant to 26 U.S.C. Sec. 7201, is a legal document used to prosecute individuals who willfully attempt to evade or defeat federal income tax payments. This form outlines the essential legal elements that must be proven in cases of tax evasion, distinguishing it from lesser offenses, such as failure to file a tax return. It establishes the legal framework for identifying criminal intent and actions related to tax liability.
Key components of this form
- Substantial tax owed: Proof of a significant income tax liability beyond what was reported.
- Intent to evade: Demonstration that the individual intended to avoid paying the owed amount.
- Affirmative acts: Identification of specific actions taken to conceal or mislead regarding tax obligations.
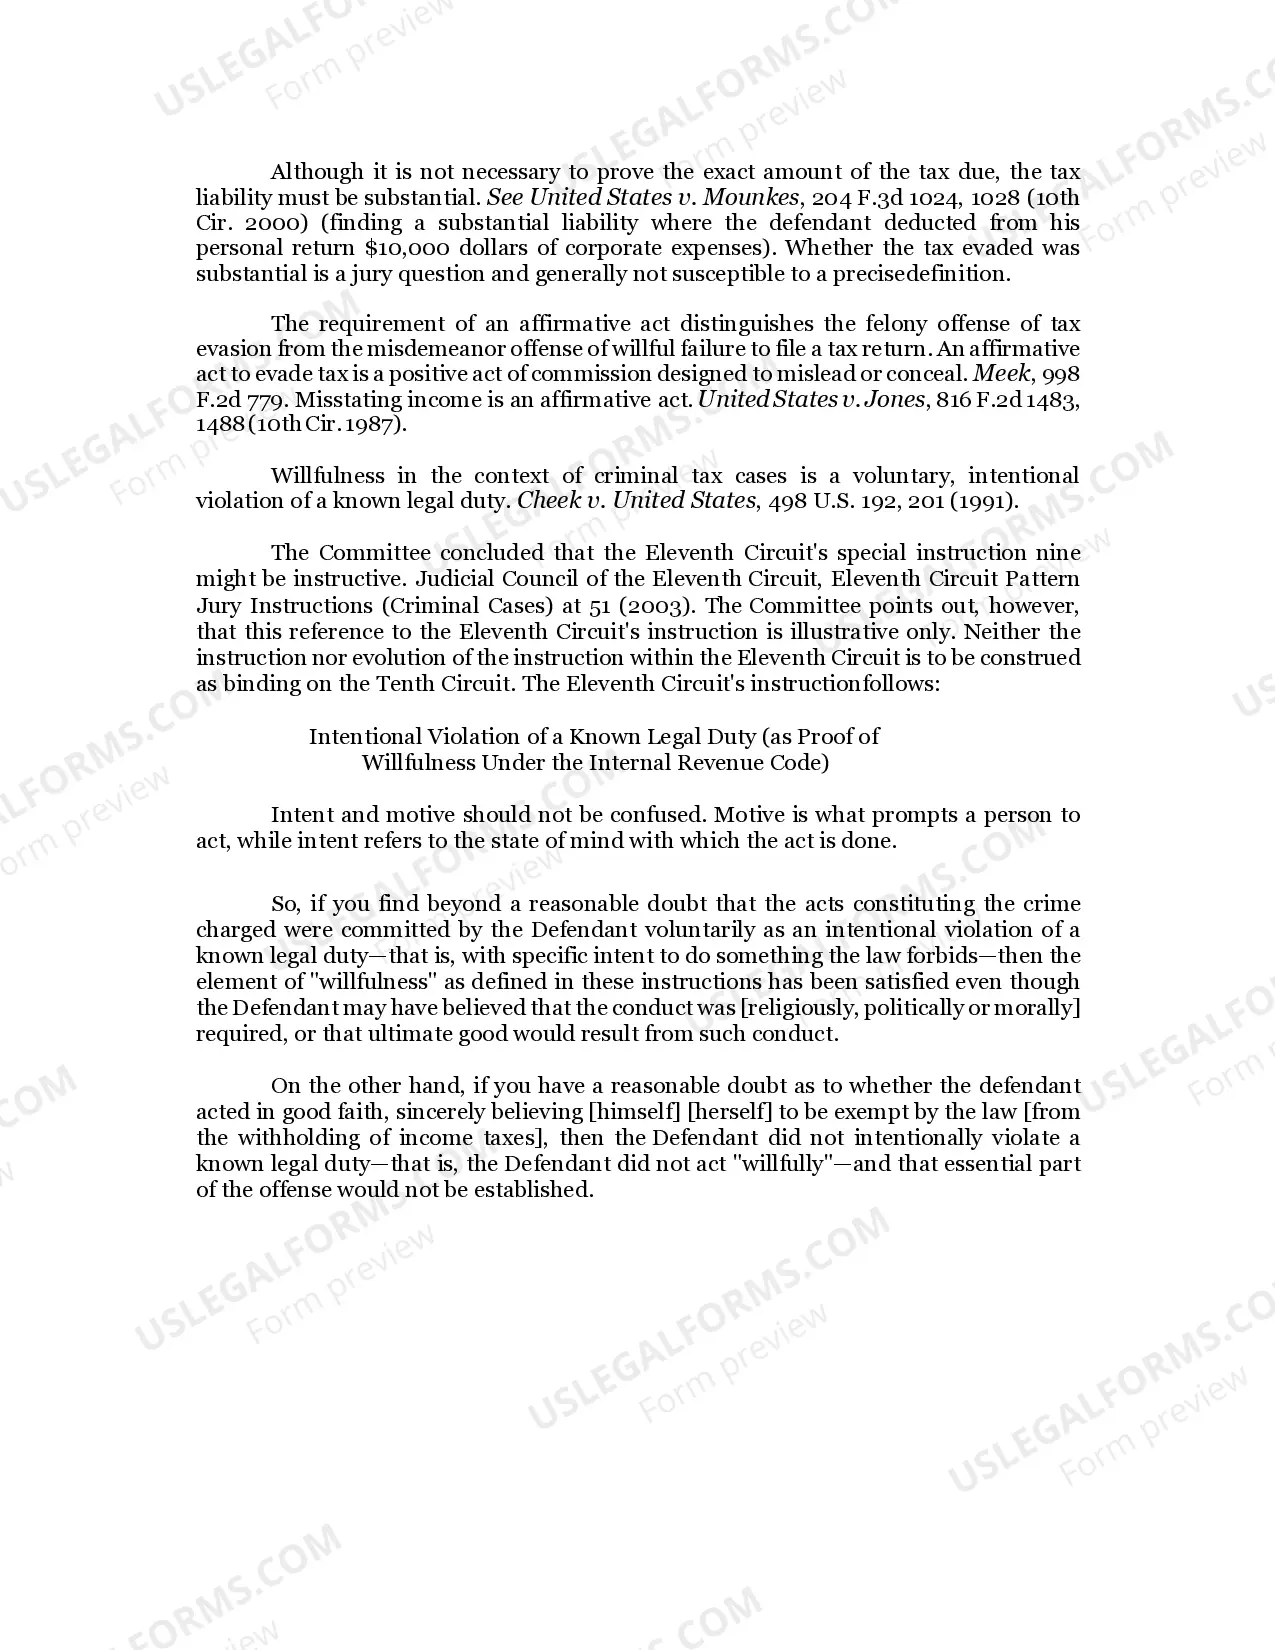
- Willfulness: Establishing that the actions were taken intentionally and knowingly, violating legal tax duties.
When this form is needed
This form is necessary when individuals are facing charges for tax evasion or when there are allegations that someone has intentionally misrepresented their income to avoid paying taxes. It is typically used by prosecutors in federal criminal cases involving significant tax liabilities.
Who can use this document
- Prosecutors handling tax evasion cases.
- Legal professionals representing defendants accused of tax evasion.
- Individuals who need to understand the implications of tax evasion allegations.
How to complete this form
- Identify the specific count under which the defendant is charged.
- Document the substantial tax liability claimed against the defendant.
- Describe the affirmative acts allegedly committed by the defendant to evade taxes.
- Establish that the defendant acted willfully in failing to fulfill tax obligations.
Notarization guidance
This form does not typically require notarization unless specified by local law. However, it is essential to verify any jurisdictional requirements regarding notarization before submission.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Typical mistakes to avoid
- Failing to clearly define the specific acts of evasion committed by the defendant.
- Not establishing the context of the substantial tax liability adequately.
- Misinterpreting willful intent versus genuine misunderstanding of tax obligations.
Why complete this form online
- Convenience of accessing legal templates anytime, anywhere.
- Editability allows for customization to fit specific legal scenarios or jurisdictions.
- Reliability of templates drafted by licensed attorneys to ensure legal compliance.
Legal use & context
- This form establishes the legal basis for prosecuting tax evasion under federal law.
- Tax evasion is treated as a felony, and convictions can lead to substantial penalties.
- Understanding the legal definitions of willfulness and affirmative acts is crucial for both prosecution and defense.
Summary of main points
- The Tax Evasion form is essential for prosecuting cases under federal law.
- It highlights the need to prove substantial tax liability, intent, and affirmative acts of evasion.
- Proper completion is crucial to successful legal proceedings concerning tax evasion allegations.
Looking for another form?
Form popularity
FAQ
Generally, the IRS can include returns filed within the last three years in an audit. If we identify a substantial error, we may add additional years. We usually don't go back more than the last six years. The IRS tries to audit tax returns as soon as possible after they are filed.
For fraud and tax evasion, the tax law dictates that if you're convicted, you may be fined up to $100,000 and sent to jail for up to five years.
The average jail time for tax evasion is 3-5 years. Evading tax is a serious crime, which can result in substantial monetary penalties, jail, or prison. The U.S. government aggressively enforces tax evasion and related matters, such as fraud.
The federal tax statute of limitations describes the time the IRS has to file charges against you if you are suspected of tax fraud. In most cases, the IRS can audit your tax returns up to three years after you file them, which means the tax return statute of limitations is three years.
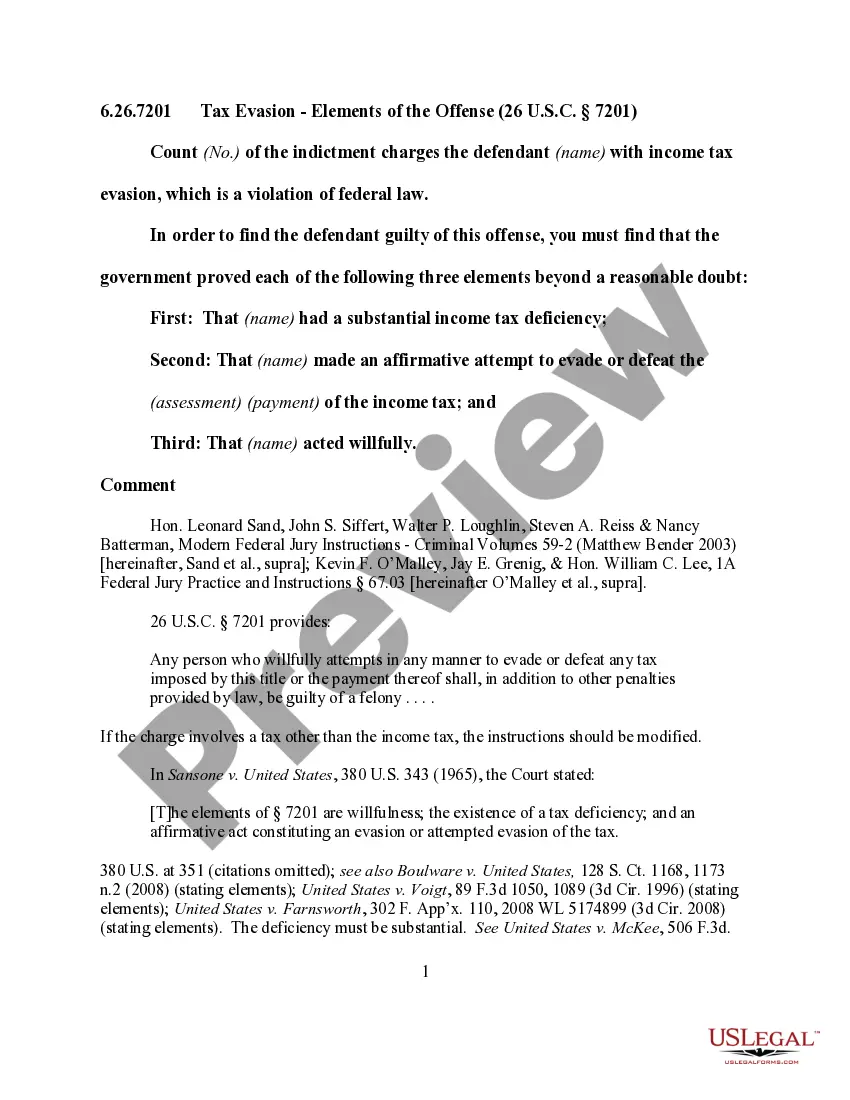
Any person who willfully attempts in any manner to evade or defeat any tax imposed by this title or the payment thereof shall, in addition to other penalties provided by law, be guilty of a felony and, upon conviction thereof, shall be fined not more than $100,000 ($500,000 in the case of a corporation), or imprisoned
Section 7201 creates two offenses: (a) the willful attempt to evade or defeat the assessment of a tax, and (b) the willful attempt to evade or defeat the payment of a tax. Sansone v. United States, 380 U.S. 343, 354 (1965).
The lookback period is the five-year period before the excess benefit transaction occurred. The lookback period is used to determine whether an organization is an applicable tax-exempt organization.