California Subordination Agreement for Existing Loan
Overview of this form
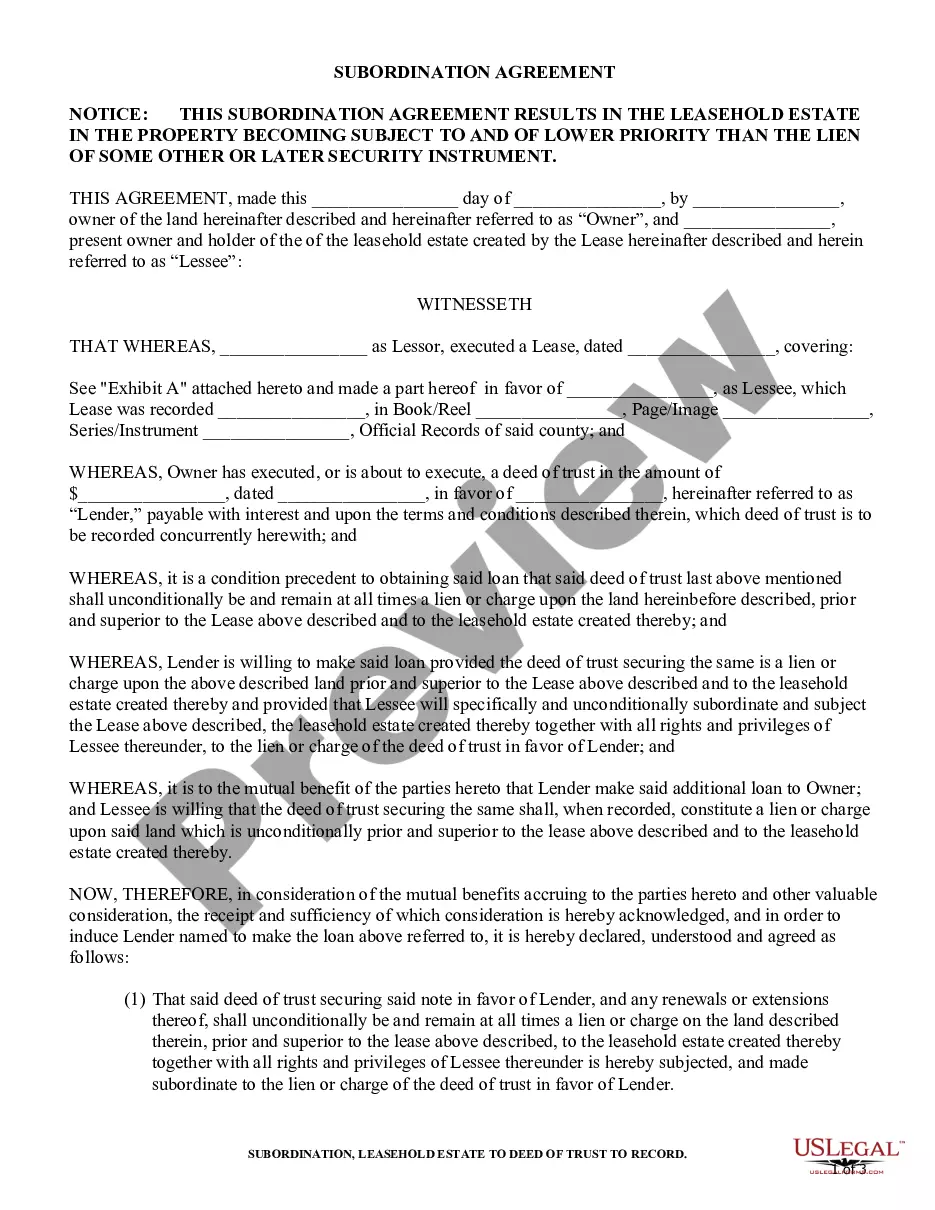
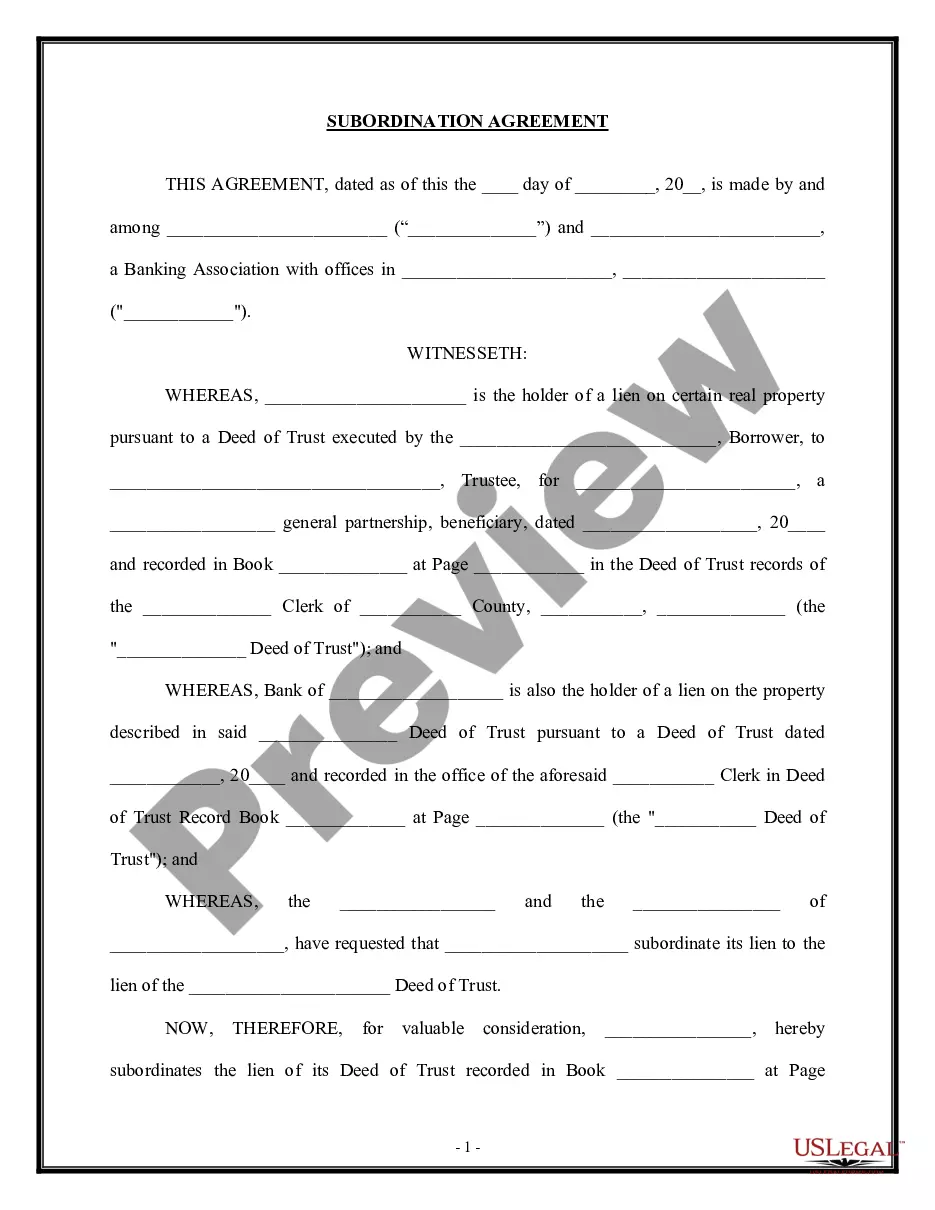
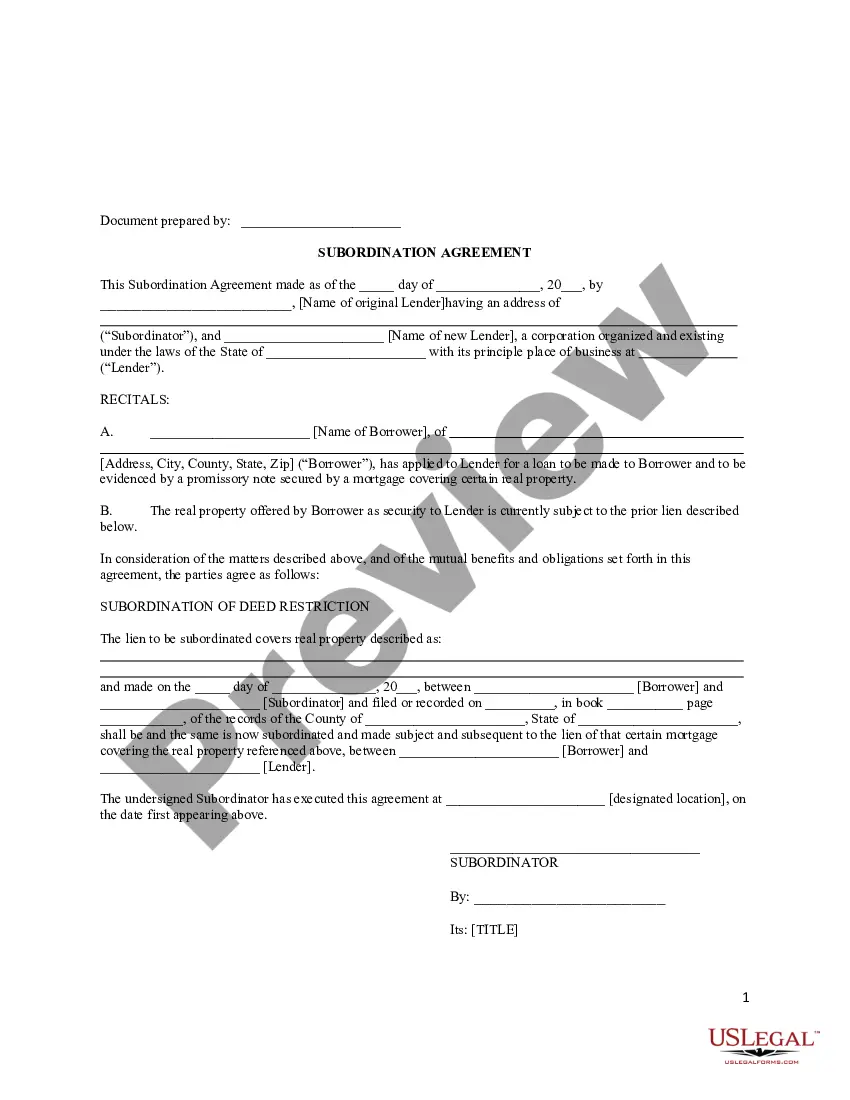
A Subordination Agreement for Existing Loan is a legal document that establishes one party's claim to a property as inferior to another party's claim. This form is used to prioritize one financial interest over another, making it essential in real estate and lending situations where a lease or another loan needs to be subordinated to a new loan. It differs from other legal agreements by specifically addressing the hierarchy of claims on property interests.
Main sections of this form
- Parties involved: Owner and Lessee, who are the signatories of the agreement.
- Details of the original lease: Information about the lease being subordinated.
- Loan details: The specifics of the new loan, including the amount and lender.
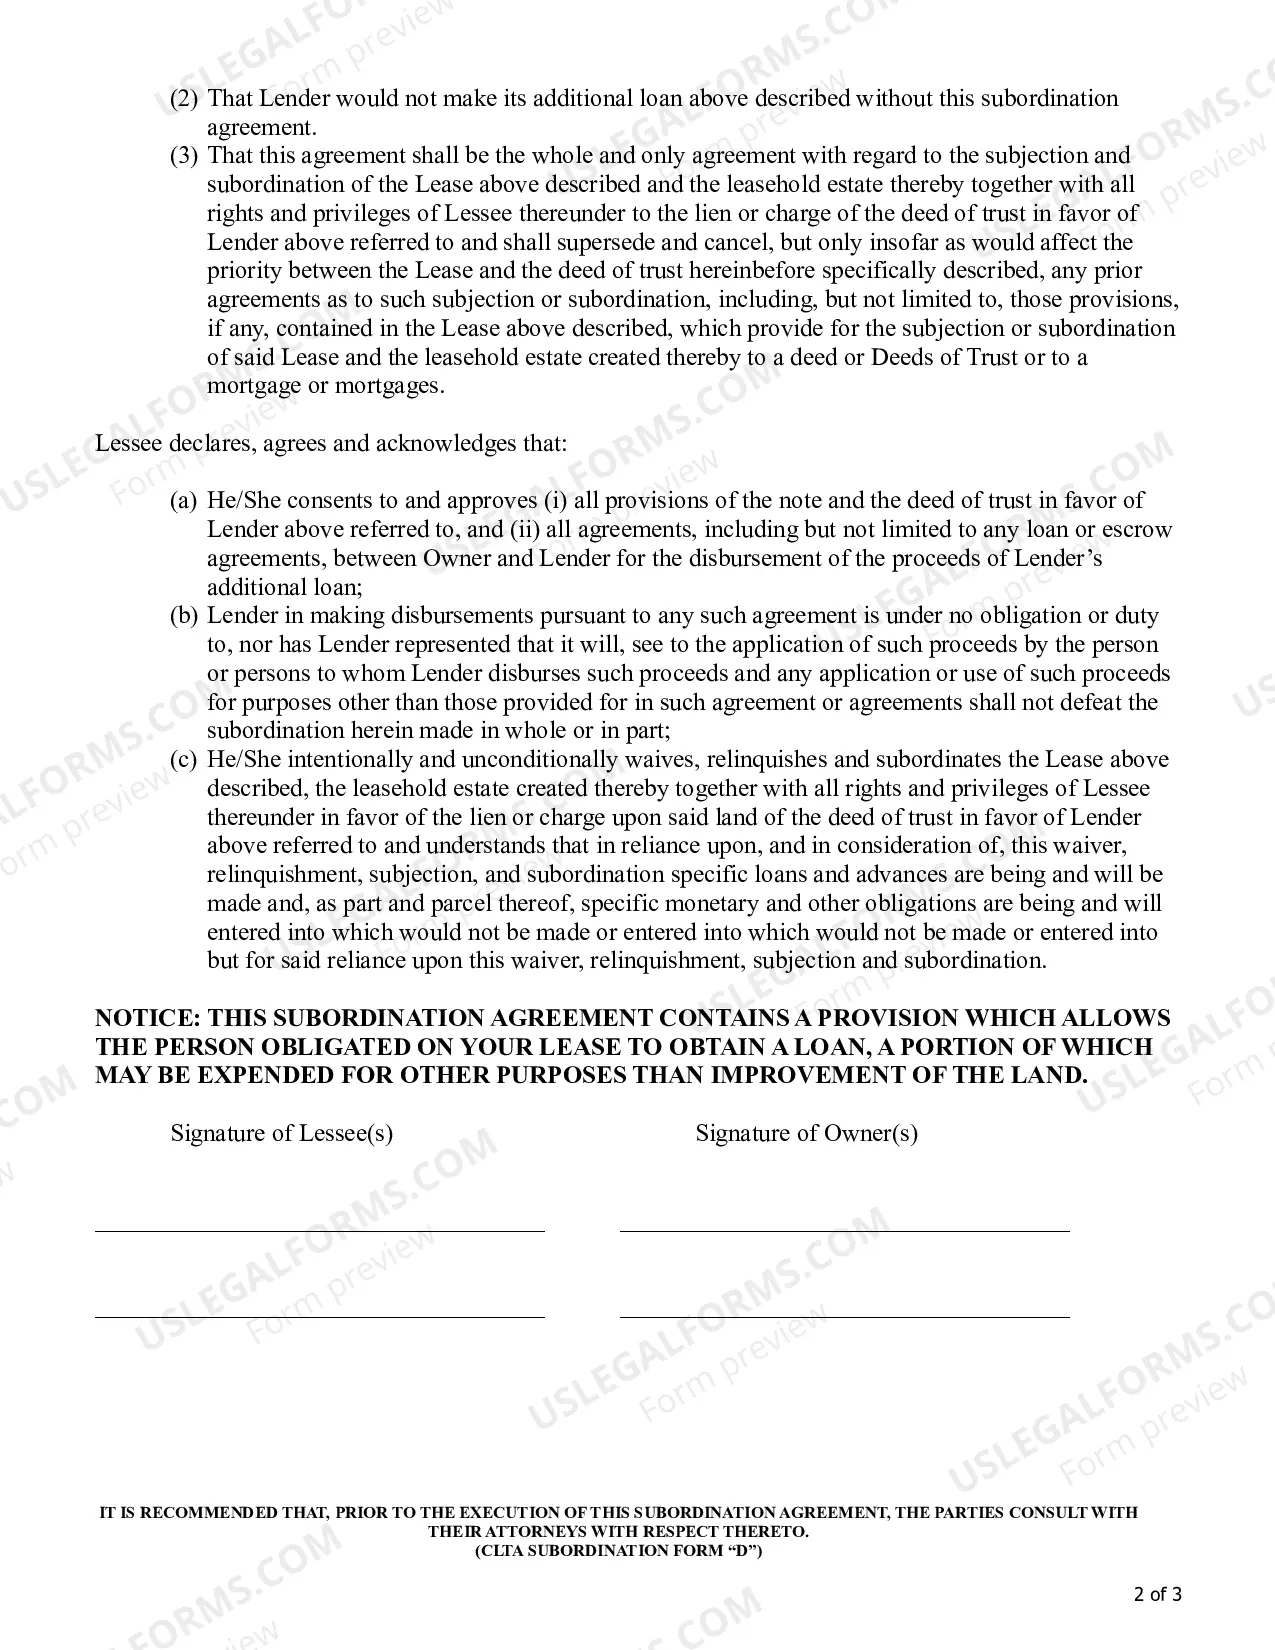
- Subordination clause: Explicit acknowledgment of the subordination of the leasehold estate to the new loanâs lien.
- Consent provisions: A declaration by Lessee agreeing to the terms of the loan agreement and its implications.
Situations where this form applies
This Subordination Agreement is needed when a property owner wishes to obtain a new loan that requires the existing lease or loan to be subordinated. It is common in situations where the property owner seeks refinancing, a second mortgage, or financing for property improvements, and must ensure that the lender's interests take priority over an existing lease.
Who should use this form
- Property Owners looking to secure additional financing against their property.
- Lessees who must consent to the subordination of their lease for the ownerâs new loan.
- Lenders who require assurance that their new loan will have priority over previous interests.
Instructions for completing this form
- Identify the parties: Enter the names of the Owner and Lessee in the appropriate sections.
- Specify the property: Clearly define the property involved in the agreement.
- Enter loan details: Fill in the loan amount, lender's name, and relevant dates.
- Review subordination terms: Ensure that all parties agree to the subordination clause.
- Sign and notarize: Ensure all parties sign the document and have it notarized, if required.
Notarization requirements for this form
Yes, this form must be notarized to be legally valid. US Legal Forms provides an integrated online notarization service that is available 24/7 via secure video call, ensuring convenience and legal equivalence without the need for travel.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Avoid these common issues
- Failing to include all necessary parties in the agreement.
- Not accurately describing the property involved.
- Overlooking the requirement for notarization.
- Incomplete or incorrect details about the loan terms.
- Assuming all Lessees will automatically agree without proper notification.
Advantages of online completion
- Convenient access: Download and complete the form at your own pace.
- Editability: Customize the form as per your specific situation and legal requirements.
- Reliable templates: Use lawyer-drafted templates ensuring legal compliance.
Looking for another form?
Form popularity
FAQ
Subordination agreements ensure that a primary lender will be paid in the event the borrower takes on more debt. As with most legal documents, subordination agreements need to be notarized in order to be official in the eyes of the law.
Purpose of a Subordination Agreement A subordination agreement is generally used when there are two mortgages and the mortgagor needs to refinance the first mortgage. It acknowledges that one party's interest or claim is superior to another in case the borrower's assets need to be liquidated to repay debts.
A subordination agreement prioritizes debts, ranking one behind another for purposes of collecting repayment from a debtor in the event of foreclosure or bankruptcy. A second-in-line creditor collects only when and if the priority creditor has been fully paid.
A subordination clause serves to protect the lender if a homeowner defaults. If this happens, the lender then has the legal standing to repossess the home and cover their loan's outstanding balance first. If other subordinate mortgages are involved, the secondary liens will take a backseat in this process.
A subordination clause is a clause in an agreement which states that the current claim on any debts will take priority over any other claims formed in other agreements made in the future.
The lender may require a subordination agreement to protect its interests in the event that the borrower deposits additional liens on the property, such as if the borrower were to take out a second mortgage.
A subordinate mortgage loan is any loan not in the first lien position. The subordination order goes by the order the loans were recorded. For example, your first mortgage (the mortgage used to buy the house) is recorded first because it's the first loan you borrow.
The party that primarily benefits from a subordination clause in real estate is the lender. However, if you decide to pursue a second mortgage, then the subordination clause prioritizes the first lender's repayment and contract rights. The most common application of subordination clauses is when refinancing a property.