Waiver Of Subrogation On Property
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
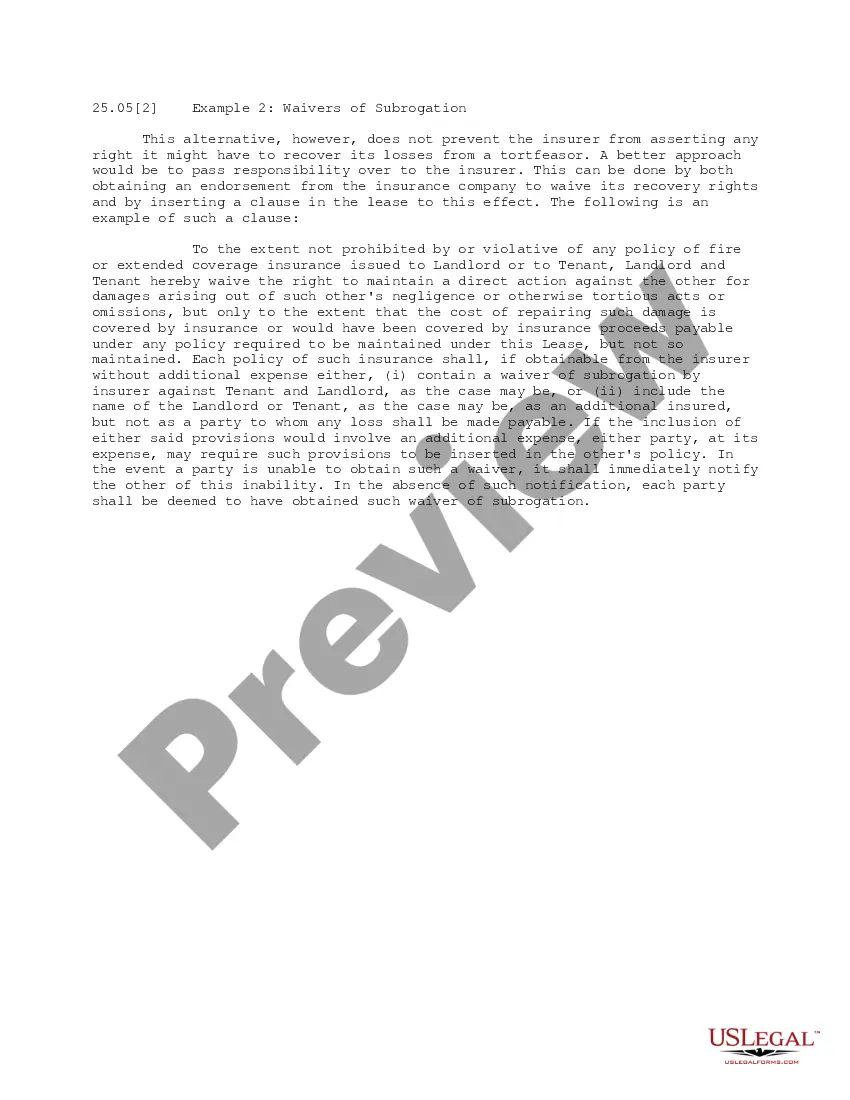
A waiver of subrogation endorsement is a clause in an insurance policy that prevents your insurance company from seeking reimbursement from a third party after paying a claim. This type of endorsement is critical when it comes to property agreements, as it protects both parties from potential conflicts. By using a waiver of subrogation on property, you can maintain a collaborative relationship with your business partners and minimize lawsuits. If you want to incorporate this type of provision, consider using US Legal Forms to help you draft the necessary documents accurately.
To obtain a waiver of subrogation on property, you typically need to request this waiver from your insurance provider or the party with whom you're entering a contract. Start by reviewing your existing insurance policy to understand its terms regarding subrogation. Then, communicate clearly with the relevant party, outlining your need for this waiver and its benefits. Using platforms like US Legal Forms can simplify the process, offering you templates and guidance tailored to help you secure a waiver of subrogation on property.
The steps in the process of subrogation begin with the insurance company paying the policyholder's claim. Next, the insurer investigates the incident to determine liability. Finally, if a third party is found liable, the insurer seeks reimbursement through legal channels. Knowing these steps can help you navigate your rights and responsibilities in property insurance.
Certainly, a waiver of subrogation applies to property. It functions by releasing your insurance company from the right to recover costs from others after settling a claim. This provision fosters smoother relationships during real estate transactions.
The disadvantages of subrogation can include increased costs for policyholders if claims become contested. Additionally, this process can lead to extended settlement times, potentially delaying payments. Understanding these issues can help you make informed decisions about protecting your property.
An example of subrogation in real estate occurs when a landlord's insurance pays for damages caused by a tenant's negligence. After paying the claim, the insurer may pursue the tenant for repayment. This instance highlights the importance of having a waiver of subrogation on property for both parties involved.
Exceptions to the waiver of subrogation can include specific circumstances outlined in the insurance policy and contractual obligations. For example, a waiver might not apply if the loss results from willful misconduct or if it contradicts local laws. Clearly understanding these exceptions can help you navigate property insurance effectively.
In property insurance, subrogation allows the insurance company to pursue recovery after it pays a claim for damages. After compensating the policyholder, the insurer can seek to recover costs from the party at fault. This process ensures you, as a property owner, receive fair compensation without causing undue financial strain.
Subrogation typically does not apply to covered losses that are not related to an insurance claim. For instance, it usually does not cover intentional acts or losses caused by the policyholder's negligence. Understanding these limitations can help you when considering a waiver of subrogation on property.
Filling out a subrogation letter involves clearly stating the details surrounding the claim. You should include the policyholder's information, the claim number, and a detailed description of the incident. Additionally, describe why you believe subrogation is applicable to your situation to ensure clarity for the receiving party.