Directors And Officers Insurance For Nonprofits
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
An example of a directors and officers claim could involve a former employee suing the nonprofit, alleging that the board members made negligent decisions that affected their employment. If the former employee claims that the leaders acted outside their legal authority, the directors and officers insurance for nonprofits would provide coverage for legal fees and any settlements arising from the situation. This demonstrates the importance of having proper coverage to protect your nonprofit's leadership.
While both directors and officers insurance and errors and omissions insurance provide essential protections, they serve different purposes. Directors and officers insurance for nonprofits focuses on the personal liability of executives for their decision-making, whereas errors and omissions insurance covers claims related to professional services and advice provided by the organization. Understanding these distinctions can help guide your nonprofit in choosing the right coverage.
Directors and officers insurance for nonprofits usually does not cover fraudulent actions or illegal profits gained by the individuals involved. Additionally, personal liability for actions taken outside their official roles may also be excluded. Issues related to bodily injury, property damage, or professional malpractice typically fall outside the scope of this insurance, so it's crucial to understand the limits of coverage.
Directors and officers insurance for nonprofits primarily protects the personal assets of the organization's leaders. This coverage typically includes defense costs for legal actions against directors and officers for alleged wrongful acts while managing the organization. It also covers settlements or judgments arising from claims, ensuring your nonprofit's executives can focus on their duties without the fear of personal financial loss.
Directors and officers insurance for nonprofits and professional liability insurance are not the same, though they both protect against lawsuits. D&O insurance focuses on the management actions and decisions of directors and officers, while professional liability relates to the services provided by professionals. Understanding these differences helps organizations choose the right coverage to address their specific risks.
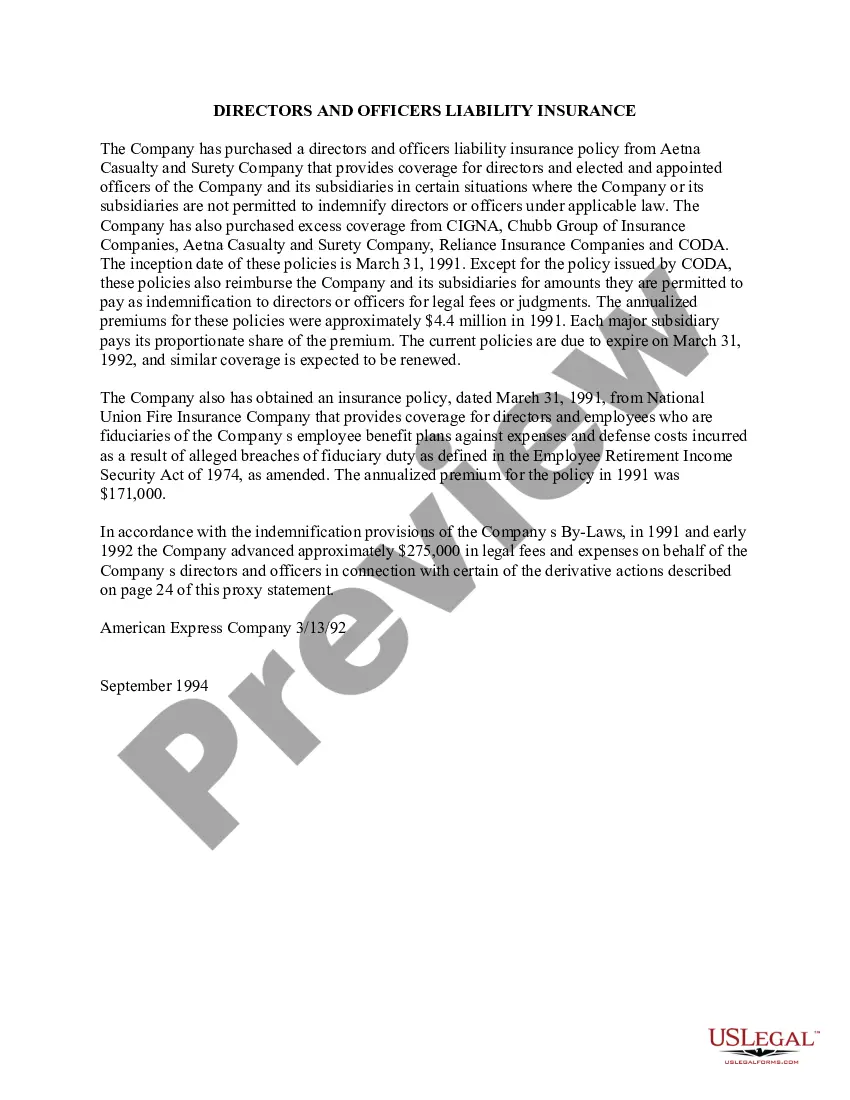
A directors and officers liability insurance clause outlines the terms of coverage within the insurance policy. It specifies the scope of protection offered, detailing how claims are processed and what instances are covered. Nonprofits benefit from understanding this clause, as it clarifies their responsibilities and the insurance company's duties in safeguarding against potential liabilities.
Directors and officers insurance for nonprofits usually operates on a claims-made basis, meaning it covers claims only when they are made during the policy period. This structure emphasizes the necessity of having continuous coverage, as any claims reported after the policy expires may not be covered. Organizations should ensure they understand this aspect to maintain adequate liability protection.
An example of a D&O claim might involve allegations of mismanagement of nonprofit funds by the board of directors. If stakeholders believe that decisions made have caused financial harm, they may file a lawsuit against the directors. Claims like these highlight the importance of having directors and officers insurance for nonprofits, as it can provide financial protection against such legal issues.
Similar to directors and officers insurance for nonprofits, the major shareholder exclusion in D&O insurance indicates that claims brought forth by significant shareholders generally will not receive coverage. This exclusion aims to prevent conflicts of interest and protects nonprofits from potential lawsuits among those who have substantial control. Organizations must be aware of this exclusion to properly manage their risk and governance.
The major shareholder exclusion in directors and officers insurance for nonprofits refers to a provision that typically excludes coverage for claims made by major shareholders. This means that if a claim arises from actions taken by individuals holding a significant percentage of shares, those claims may not be covered. Understanding this exclusion helps organizations protect themselves while maintaining a balanced governance structure.