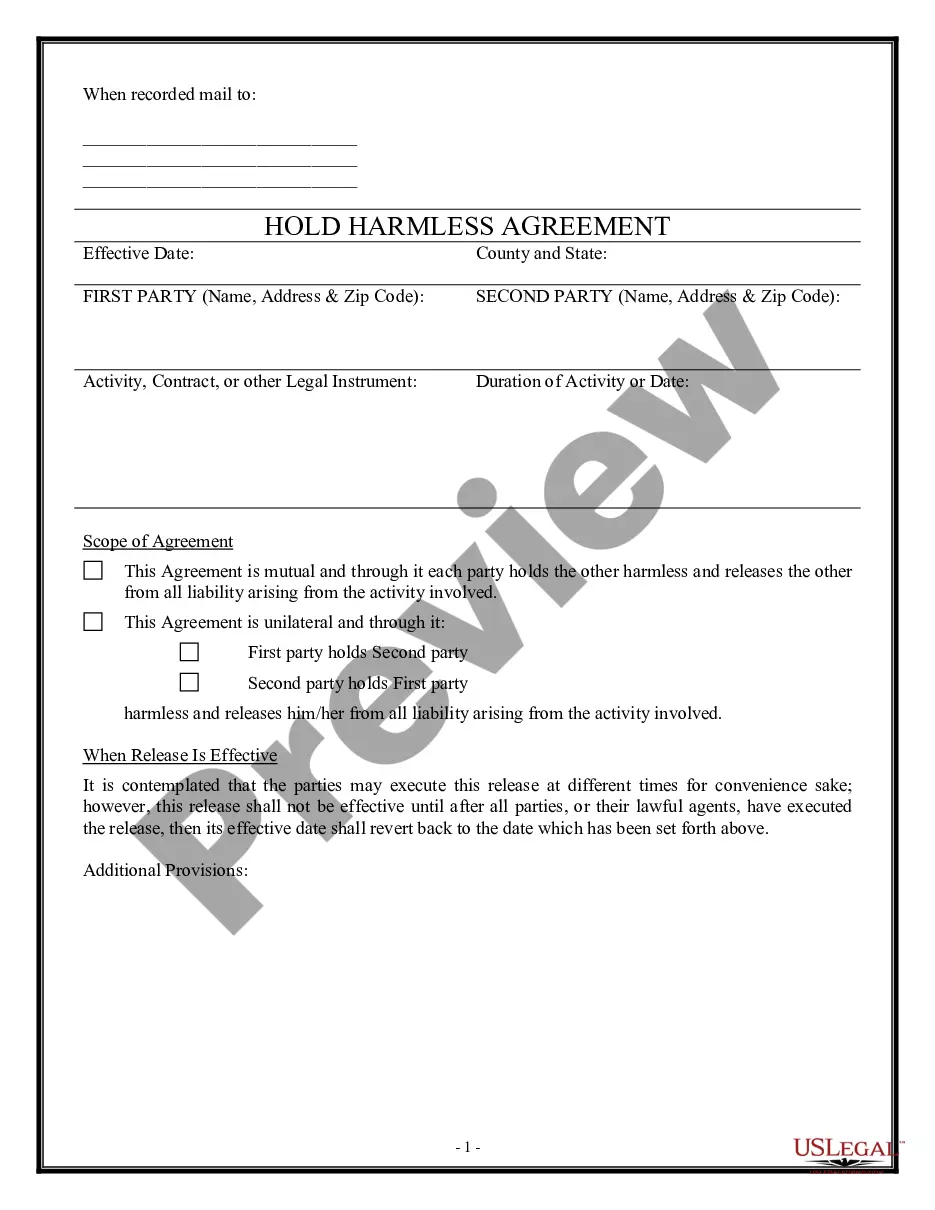
Hold Harmless Agreement For Hunting
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
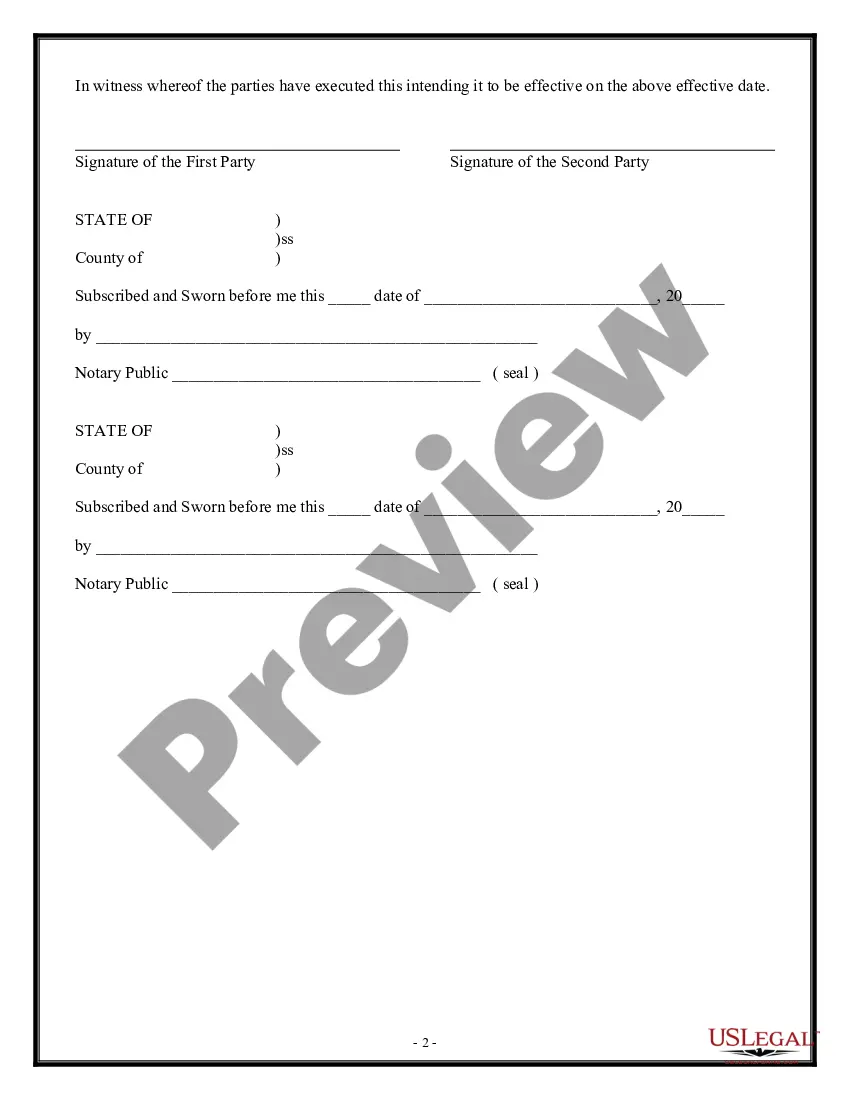
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
How to fill out General Hold Harmless Agreement?
Managing legal documents can be perplexing, even for the most seasoned experts.
If you are in need of a Hold Harmless Agreement For Hunting and lack the time to search for the correct and current version, the process can be stressful.
Tap into a valuable resource database of articles, tutorials, and guides relevant to your situation and requirements.
Conserve time and effort searching for the documents you need, utilizing US Legal Forms' sophisticated search and Review tool to find Hold Harmless Agreement For Hunting and secure it.
Make sure the template is accepted in your state or county before selecting Buy Now when ready.
- If you have a subscription, Log In to your US Legal Forms account, search for the form, and acquire it.
- Check the My documents tab to see the documents you have previously downloaded and to manage your folders as desired.
- If this is your first interaction with US Legal Forms, create an account for unlimited access to all the platform's benefits.
- Here are the steps to take once you find the form you need.
- Ensure it is the correct document by previewing it and reviewing its details.
- Access state- or county-specific legal and business documents.
- US Legal Forms addresses any requirements you might have, ranging from personal to business paperwork, all in one location.
- Employ advanced tools to complete and manage your Hold Harmless Agreement For Hunting.
Form popularity
FAQ
If you lend the money at no interest, the IRS can consider the loan a gift, making you liable for gift taxes. The repayment schedule that the borrower must follow. State whether you'll require periodic payments, a balloon payment or some combination.
Wiedman suggests putting everything involving the loan in your written agreement: "The date of the loan, loan amount, repayment terms, interest rate, payment due dates and so forth." That said, putting everything in writing can make things awkward, but it's a safe move if you want to ensure repayment.
There are 10 basic provisions that should be in a loan agreement. Identity of the parties. The names of the lender and borrower need to be stated. ... Date of the agreement. ... Interest rate. ... Repayment terms. ... Default provisions. ... Signatures. ... Choice of law. ... Severability.
A loan agreement is any written document that memorializes the lending of money. Loan agreements can take several forms. The most basic loan agreement is commonly called an "IOU." These are typically used between friends or relatives for small amounts of money, and simply state the dollar amount that is owed.
At a minimum, your loan contract should include: Your name and the borrower's name. The date the loan was granted. The amount of money being lent. Minimum monthly payment. Payment due date. Interest rate, if you're charging interest. Consequences for defaulting on the loan.
Do you need to notarize a Loan Agreement? First and foremost, understand that personal loan agreements fall into the classification of contracts. Technically, you don't have to notarize these documents. But if you want to make this document legally binding, then notarization is the best course of action.
What should be in a personal loan contract? Names and addresses of the lender and the borrower. Information about the loan co-borrower or cosigner, if it's a joint personal loan. Loan amount and the method for disbursement (lump sum, installments, etc.) Date the loan was provided. Expected repayment date.
Loaning friends and family money is a hotly-debated topic, but one thing that is always a given ? the threshold after which the IRS gets involved. ing to the U.S. Code, that figure is $10,000. It's referred to as the ?de minimis exception? ? referring to small loans from the tax agency's perspective.