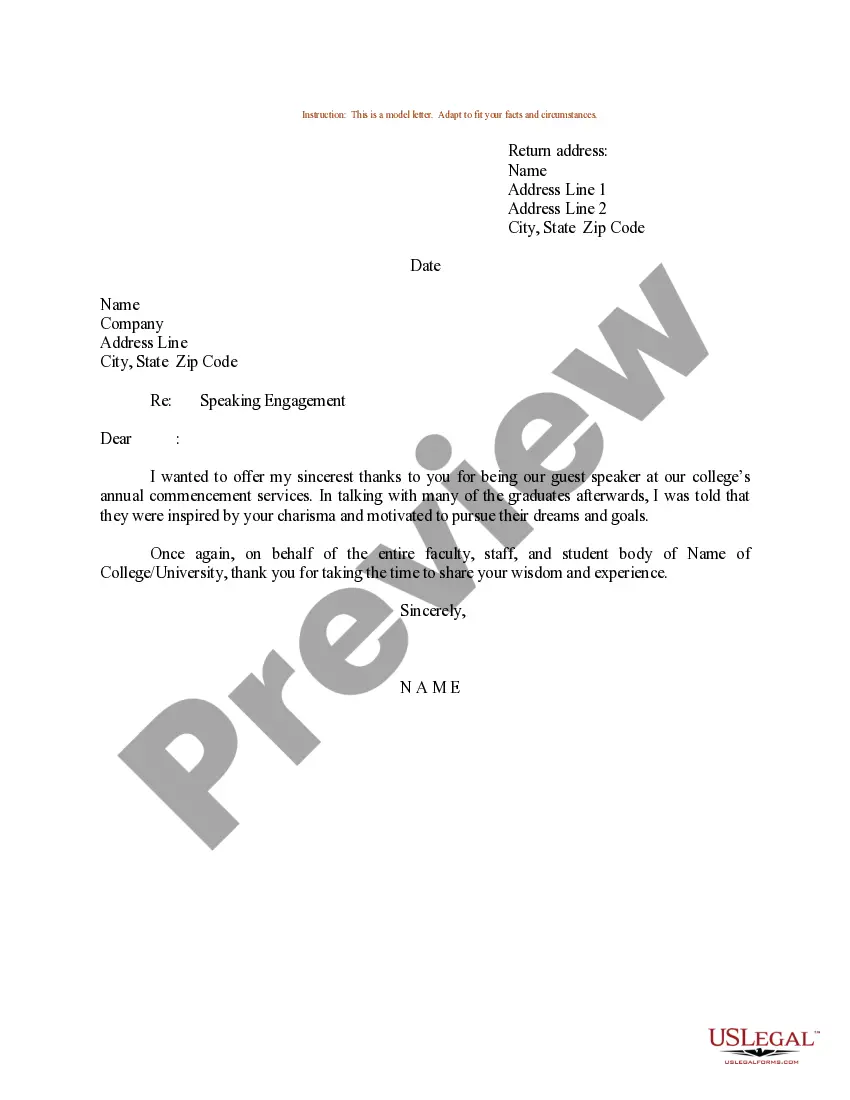
Letter Engagement Form With Decimals In Los Angeles
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
The California Constitution provides for the exemption of $7,000 (maximum) in assessed value from the property tax assessment of any property owned and occupied as the owner's principal place of residence.
Overview of California Taxes Gross Paycheck$2,415 Federal Income 8.58% $207 State Income 3.08% $74 Local Income 0.00% $0 FICA and State Insurance Taxes 8.65% $20923 more rows
A seller/transferor that qualifies for a full, partial, or no withholding exemption must file Form 593. Any remitter (individual, business entity, trust, estate, or REEP) who withheld on the sale/transfer of California real property must file Form 593 to report the amount withheld.
Property tax in California is calculated at a standard rate of 1% of the assessed property value, plus additional charges for voter-approved bonds, fees, and special charges.
A party making a peremptory challenge by motion or affidavit of prejudice regarding an assigned judge must submit it in writing to the assigned judge within 20 days after service of the order assigning the judge to the coordination proceeding.
LASC CIV 301 - Amendment to Cross-Complaint (Corrected Name). This form is used when the cross-complainant files a cross-complaint with an incorrect name for the cross-defendant. The form allows for the correction of the cross-complaint by substituting the true name for the incorrect one, with options for both cases.
A seller/transferor that qualifies for a full, partial, or no withholding exemption must file Form 593. Any remitter (individual, business entity, trust, estate, or REEP) who withheld on the sale/transfer of California real property must file Form 593 to report the amount withheld.
In order to claim exemption from state income tax withholding, employees must submit a W-4 or DE-4 certifying that they did not have any federal tax liability for the preceding year and that they do not anticipate any tax liability for the current taxable year.
Any remitter (individual, business entity, trust, estate, or REEP) who withheld on the sale/transfer of California real property must file Form 593 to report the amount withheld. If this is an installment sale payment after escrow closed, the buyer/transferee is the responsible person.
Generally, you must file an income tax return if you're a resident , part-year resident, or nonresident and: Are required to file a federal return. Receive income from a source in California.