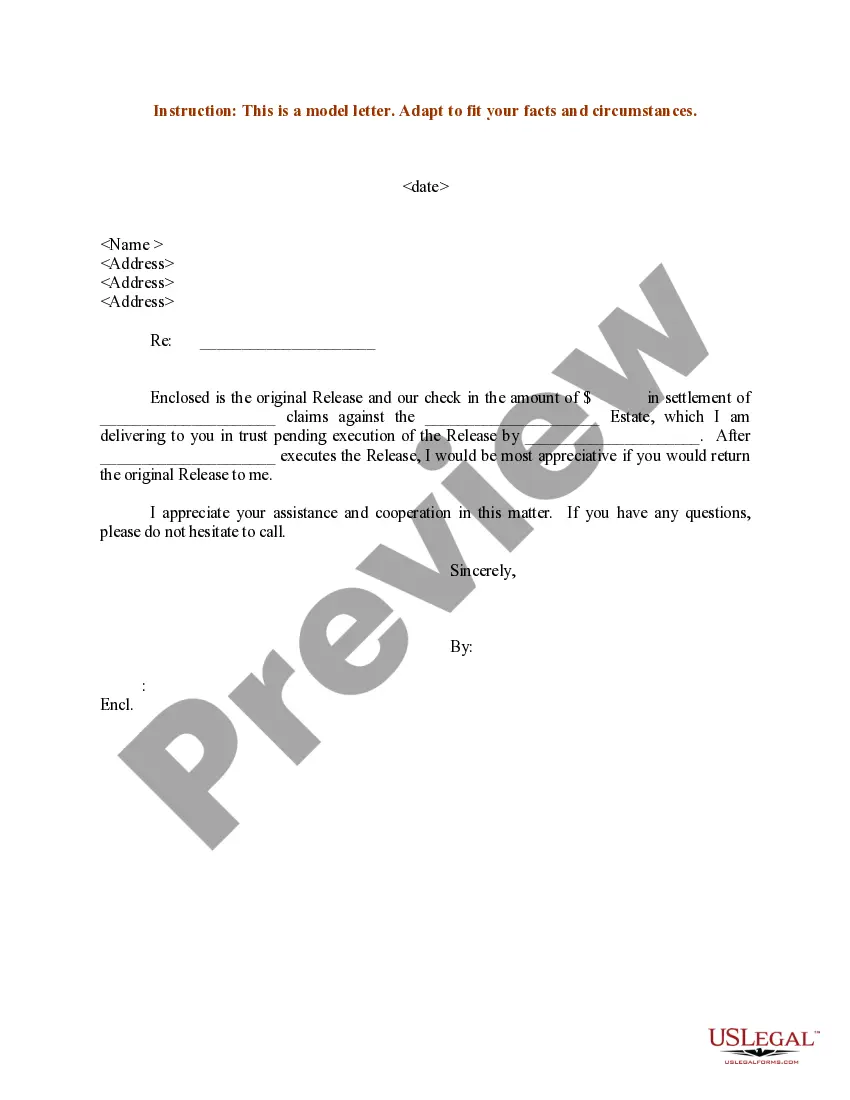
Estate Claim Form With Irs In New York
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
You must file Form ET-706 within nine months after the decedent's date of death, unless you receive an extension of time to file the return. An extension of time to file the estate tax return may not exceed six months, unless the executor is out of the country.
Residents. The estate of a New York State resident must file a New York State estate tax return if the following exceeds the basic exclusion amount: the amount of the resident's federal gross estate, plus. the amount of any includible gifts.
The Gift Tax Return (Form 709) and the Estate Tax Return (Form 706) document your estate planning and provide the “Paper Trail” for the IRS and state departments of revenue. Most of the estate planning techniques must be reported on these tax returns.
New York Estate Tax Rate The estate tax rate for New York is graduated. It starts at 3.06% and goes up to 16%. The taxable estate is the value of the estate above the $7.16 million exemption (unless the estate reaches that cliff of 105% of $7.16 million, then the whole estate is taxable).
New York is one of 15 states (and the District of Columbia) that imposes a state level estate or inheritance tax on its residents (and even some non-resident property owners) at the time of death. This tax is in addition to the estate tax imposed by the Federal government. The top New York estate tax rate is 16%.
Generally, for New York estate tax purposes, if the value of assets passing to beneficiaries other than a spouse or charity is below a certain threshold ($6.94 million in 2024), the assets are fully exempt from tax and no New York estate taxes will be due.
Filing Requirements Residents: The estate of a New York resident must file a New York State estate tax return if the amount of the resident's federal gross estate, plus the amount of any includible gifts, exceeds the basic exclusion amount applicable at the date of death.
New York Estate Tax Exemption The New York estate tax threshold is $7.16 million in 2025 and $6.94 million in 2024. That number will keep going up annually with inflation. This means that if a person's estate is worth less than $7.16 million and they die in 2024, the estate owes nothing to the state of New York.
Generally, for New York estate tax purposes, if the value of assets passing to beneficiaries other than a spouse or charity is below a certain threshold ($6.94 million in 2024), the assets are fully exempt from tax and no New York estate taxes will be due.