Nys Deferred Comp Withdrawal Form With Two Points In San Diego
Description
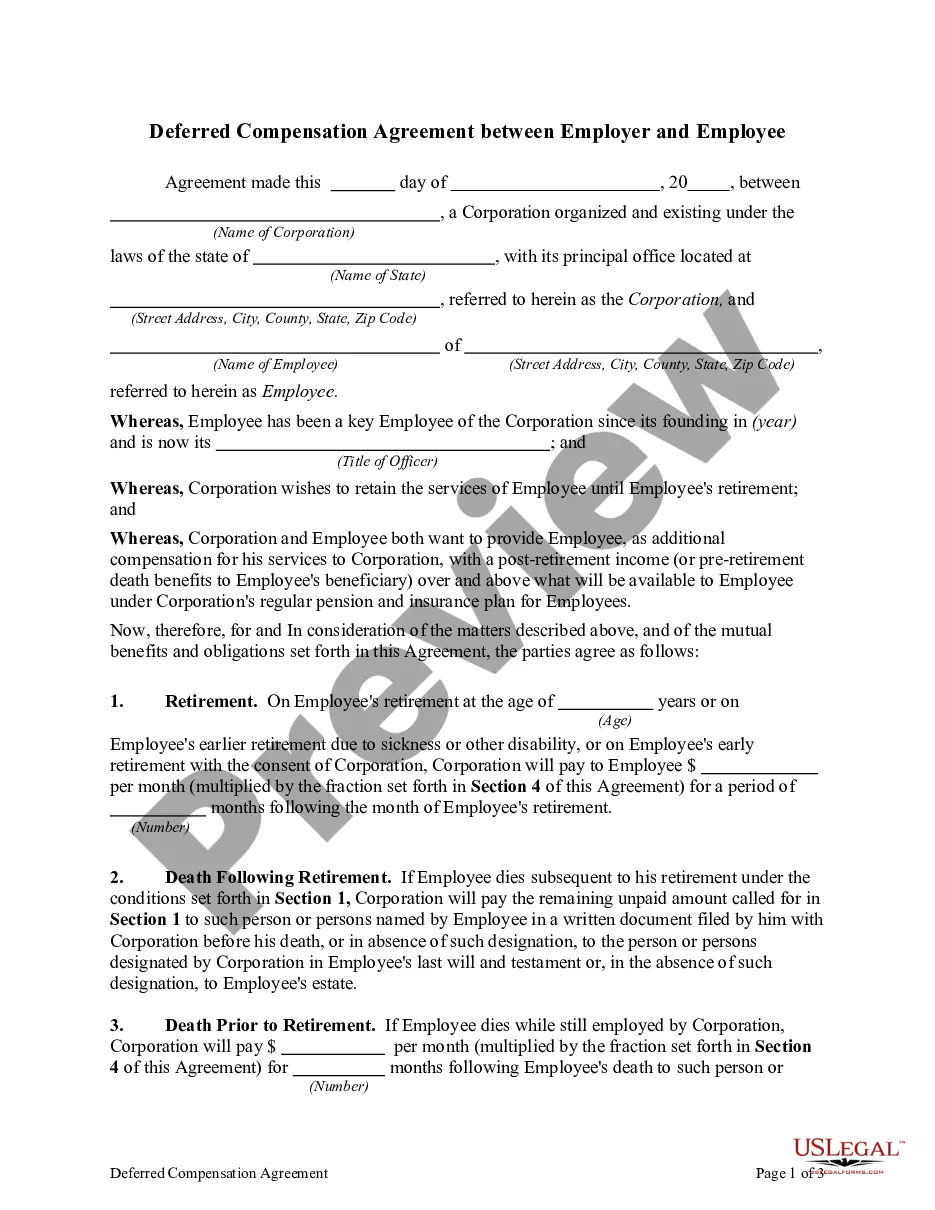
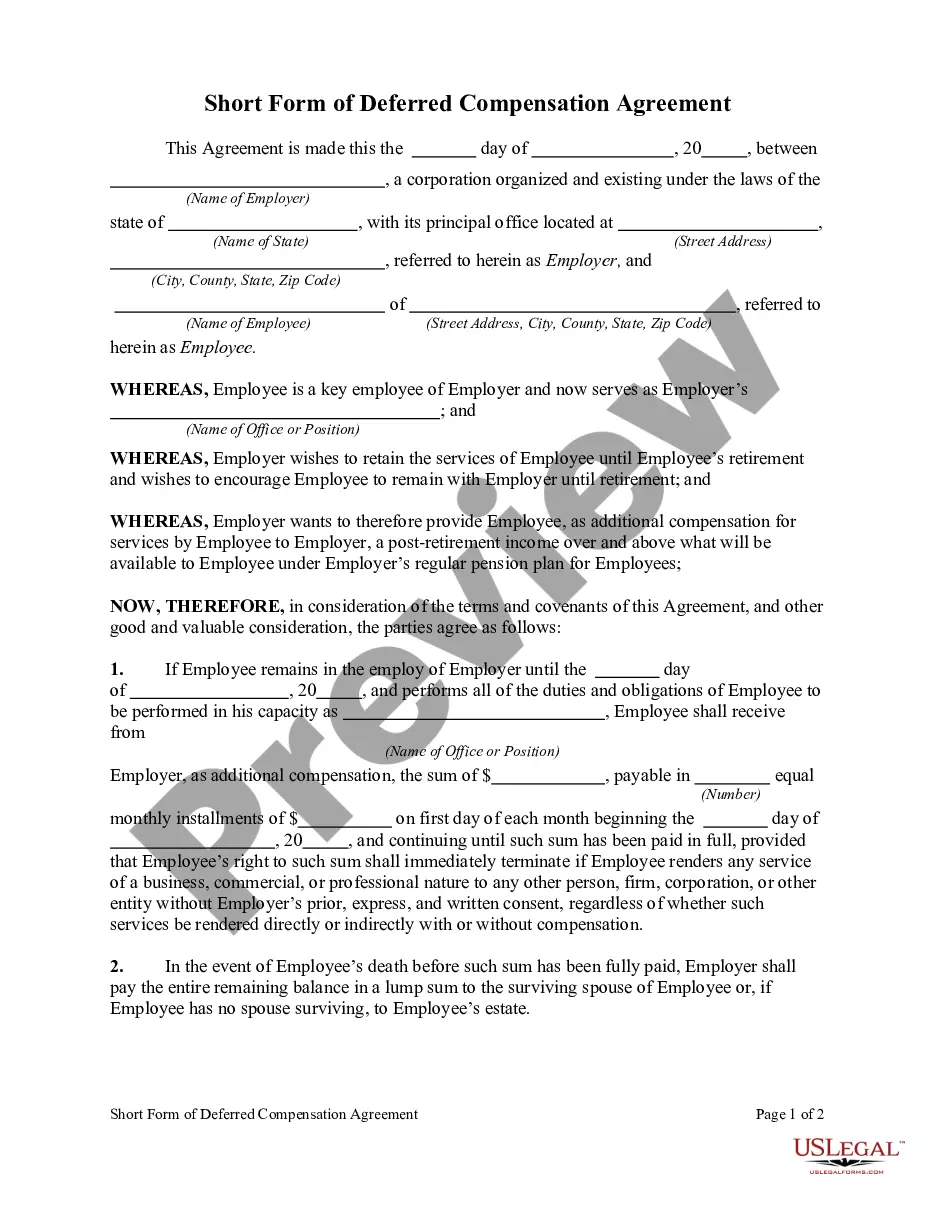
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
You may keep your contributions in the Plan and continue to build savings for retirement. However, you may withdraw your contributions if you: Have a Plan account balance of less than $5,000, exclusive of any assets you may have in a rollover account, AND. Have not contributed to the Plan in the last two years, AND.
The Plan differs from other defined contribution retirement plans (like a 401(k) or 403(b)), because it is designed and managed with public employees in mind. The New York State Deferred Compensation Board establishes and administers the Plan policies.
You can: Call the HELPLINE at 1-800-422-8463 and an Account Executive will help you.
Specifically, an unforeseeable emergency is defined in Plan Y as a severe financial hardship of the participant resulting from any of the following: an illness or accident of the participant, the participant's spouse, or the participant's dependent (as defined in § 152(a)); loss of the participant's property due to ...
With Roth 401(k)s, income taxes are not owed on the withdrawal of your contributions, but income taxes and the 10% penalty tax may apply on the withdrawal of earnings, unless an exception applies. It's important to keep taxes and penalties in mind when making an early withdrawal.
The regular yearly contributions amount for Deferred Compensation will increase from $23,000 to $23,500. The catch-up contribution limit that generally applies for employees aged 50 and over remains at $7,500 for 2025 for a combined maximum contribution limit of $31,000 in 2025.
Elective deferral limit The amount you can defer (including pre-tax and Roth contributions) to all your plans (not including 457(b) plans) is $23,000 in 2024 ($22,500 in 2023; $20,500 in 2022; $19,500 in 2020 and 2021; $19,000 in 2021).
If you roll your DCP funds directly over into a traditional IRA or eligible retirement plan, the funds won't be taxed until you withdraw them. If you roll over into a Roth account, the rules could be different. Check with the IRS to learn how this choice will impact you.