Decedent Account Bank Withholding In Montgomery
Description
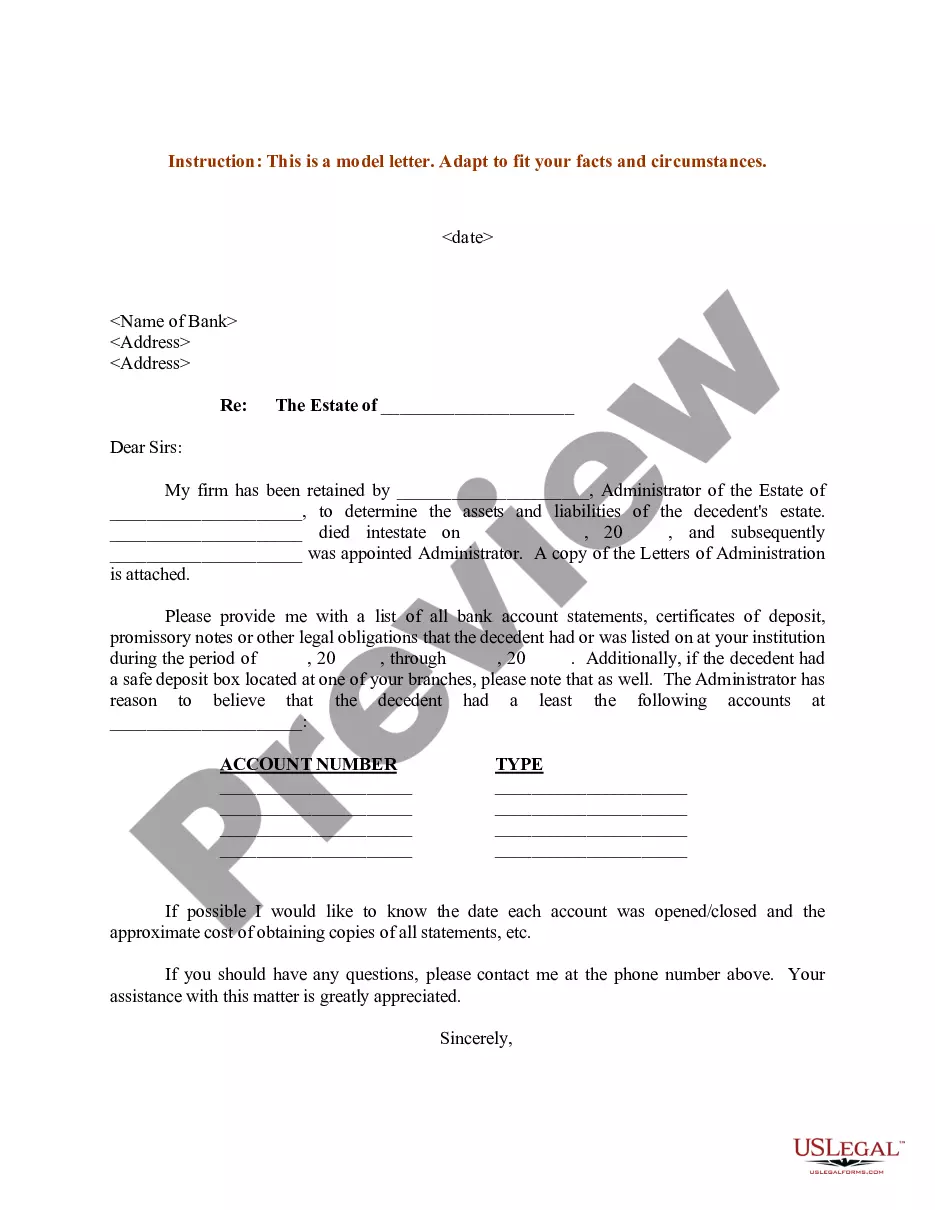
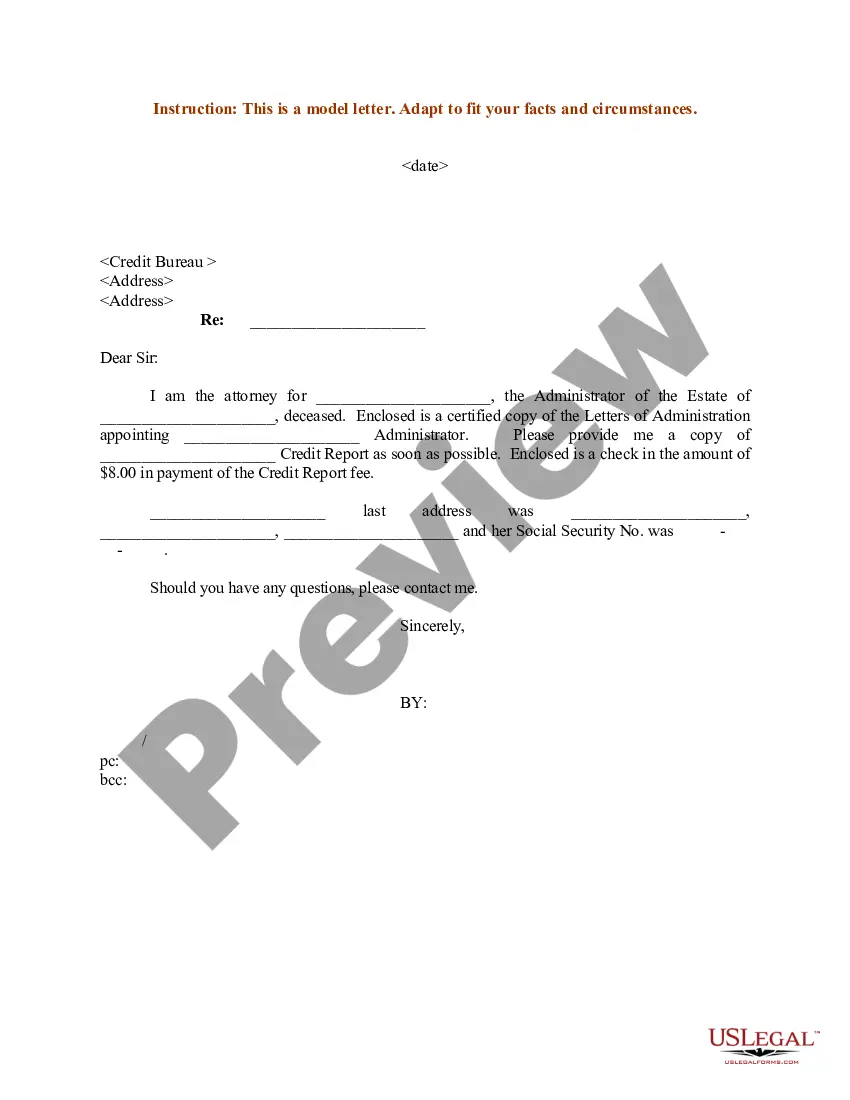
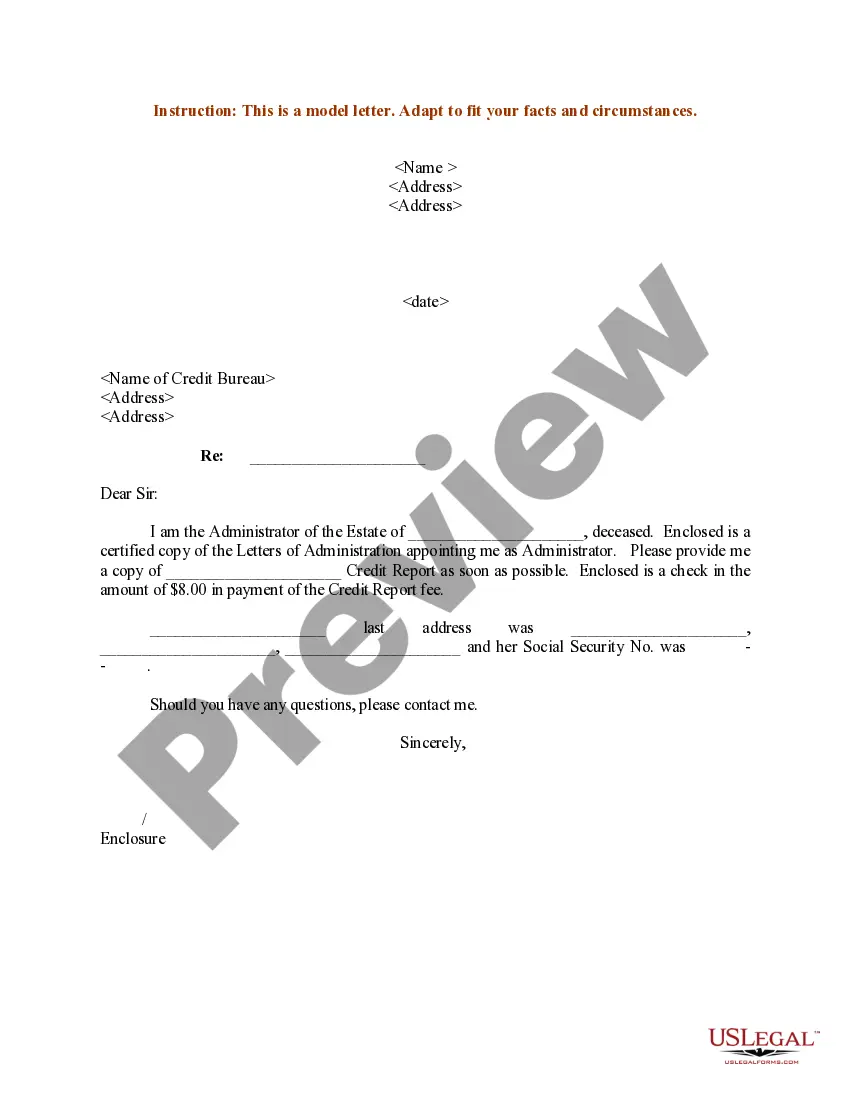
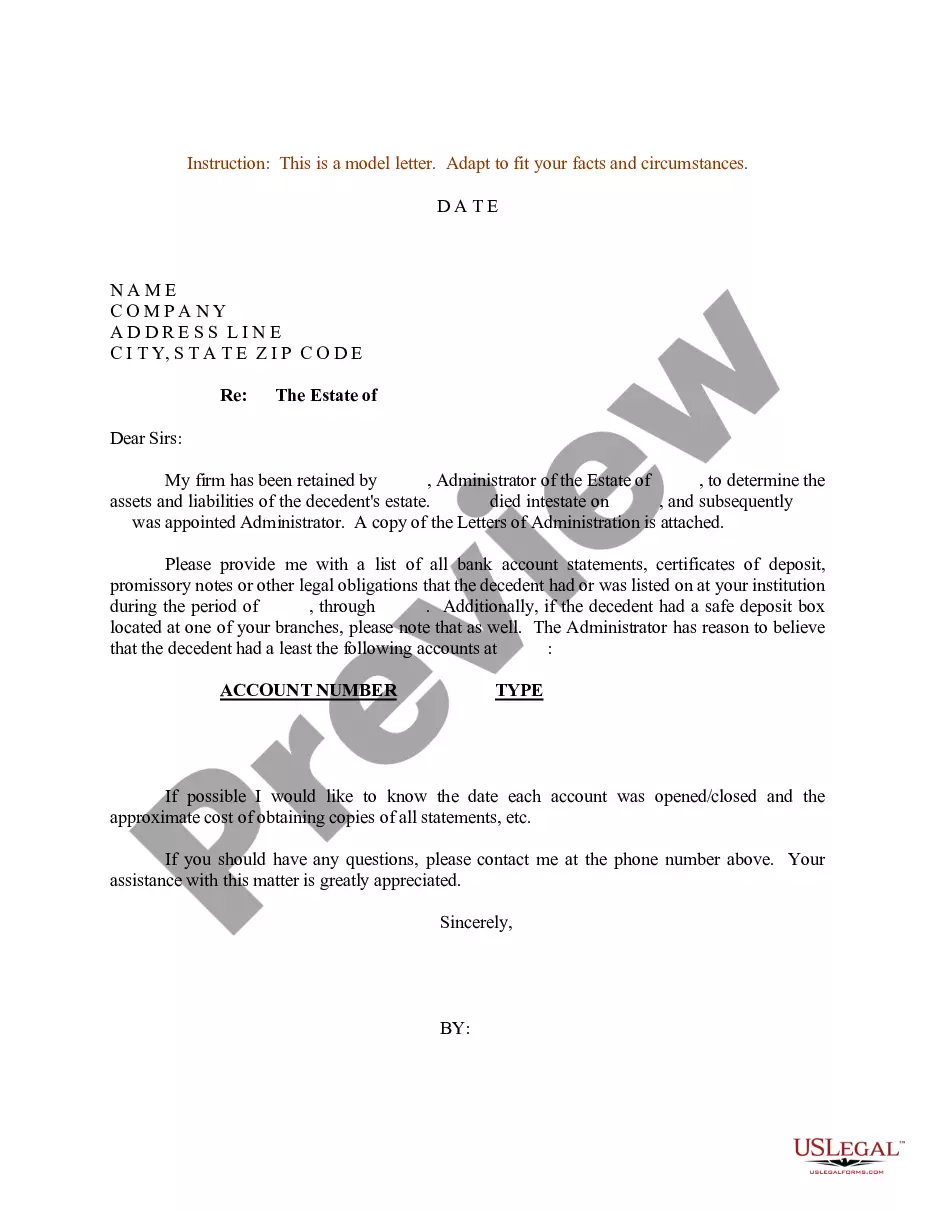
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
1% tax on the clear value of property passing to a child or other lineal descendant, spouse, parent or grandparent. 10% on property passing to siblings or other individuals.
Transfer assets into a trust Because those assets don't legally belong to the person who set up the trust, they aren't subject to estate or inheritance taxes when that person passes away. Setting up a trust also has other financial benefits, such as helping the estate avoid probate.
How to Avoid Probate in Maryland: Strategies to Simplify the... Create a Revocable Living Trust. Utilize Joint Ownership with Right of Survivorship. Designate Beneficiaries on Accounts and Policies. Gift Assets Before Death. Establish a Small Estate. Use Maryland's Simplified Probate Options.
Spouse and Direct or Lineal Heirs For decedents dying on or after July 1, 2000, direct or lineal heirs are exempt from inheritance tax. This includes a spouse, child, grandchild, great-grandchild, stepchild, parent, or grandparent.
Property passing to a child or other lineal descendant, spouse of a child or other lineal descendant, spouse, parent, grandparent, stepchild or stepparent, siblings or a corporation having only certain of these persons as stockholders is exempt from taxation.
(Non-Probate property includes, but not limited to, jointly held assets, life estate or remainder interests in a trust or deed, trusts in which the decedent had an interest, payable on death (P.O.D.) assets, and pension and benefit plans including IRAs with named beneficiaries.)
The family exemption is a right given to specific individuals to retain or claim certain types of a decedent's property in ance with Section 3121 of the Probate, Estate and Fiduciaries Code. For decedents dying after January 29, 1995, the family exemption is $3,500.
EXEMPTIONS FROM INHERITANCE TAX Life insurance benefits payable to a named beneficiary, other than the estate of the decedent. Grave maintenance up to $500 passing under a Will for perpetual upkeep. Property administered under a Small Estate proceeding. Property passing to any one person not exceeding a total of $1,000.
Property owned jointly between husband and wife is exempt from inheritance tax, while property inherited from a spouse, or from a child aged 21 or younger by a parent, is taxed a rate of 0%. Inheritance tax returns are due nine calendar months after a person's death.
A Pennsylvania Inheritance Tax Return, REV-1500, must be filed for every decedent with property that may be subject to Pennsylvania inheritance tax.