Closing Account Due To Death Letter In California
Description
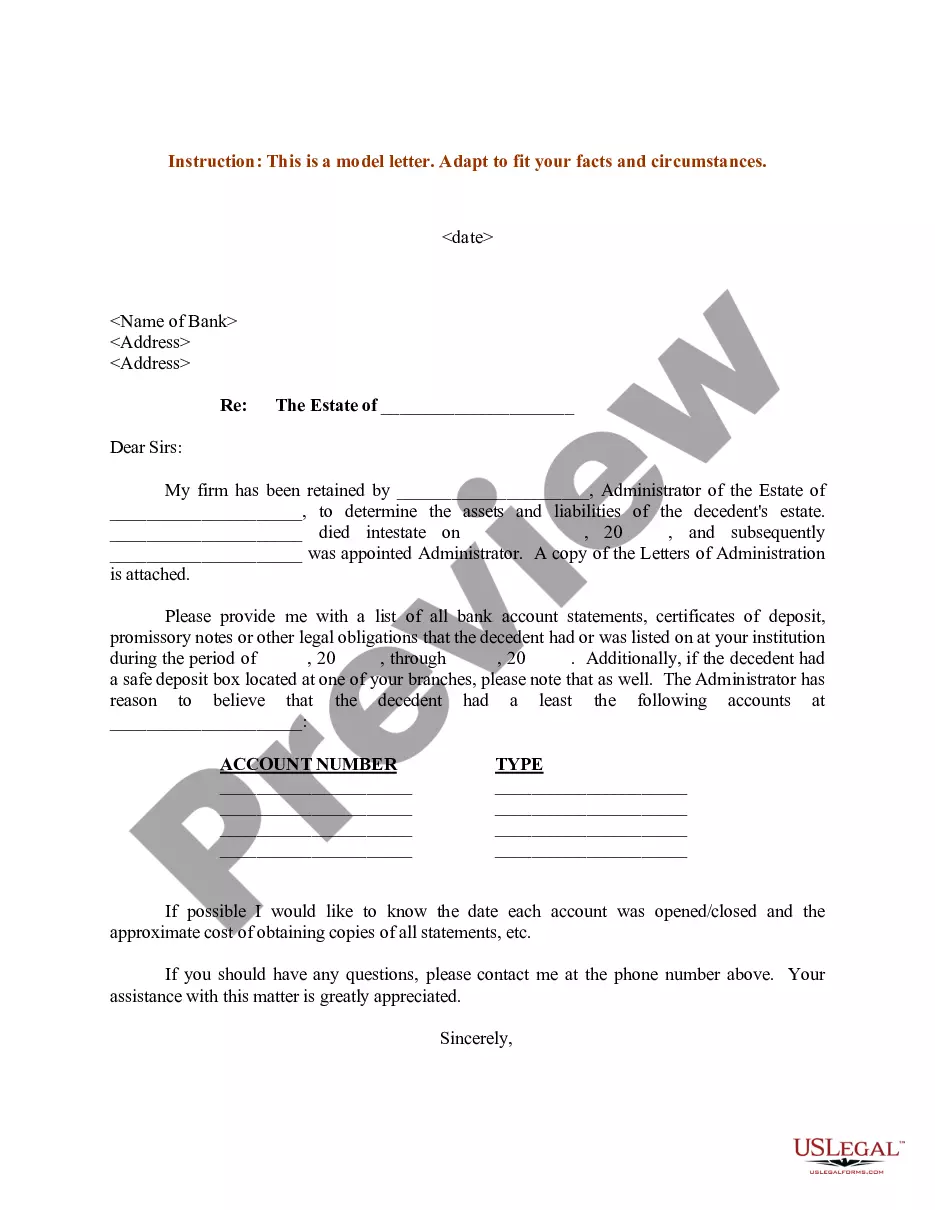
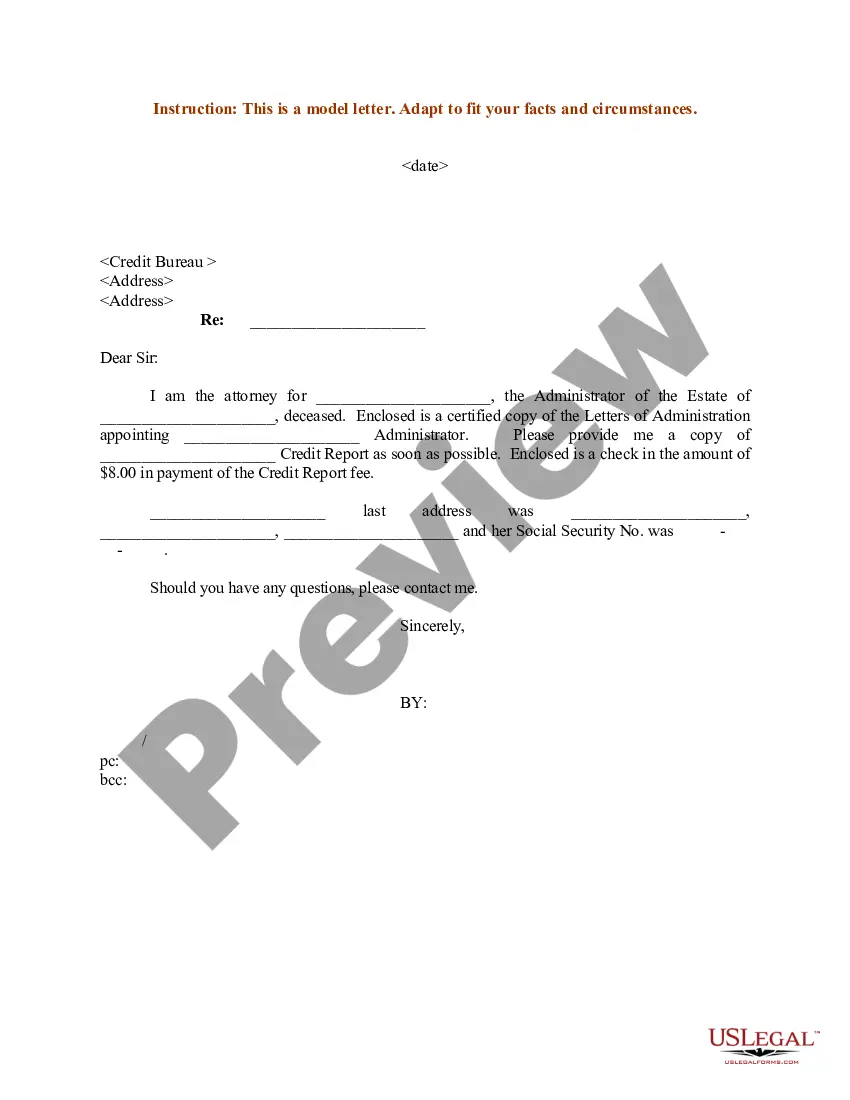
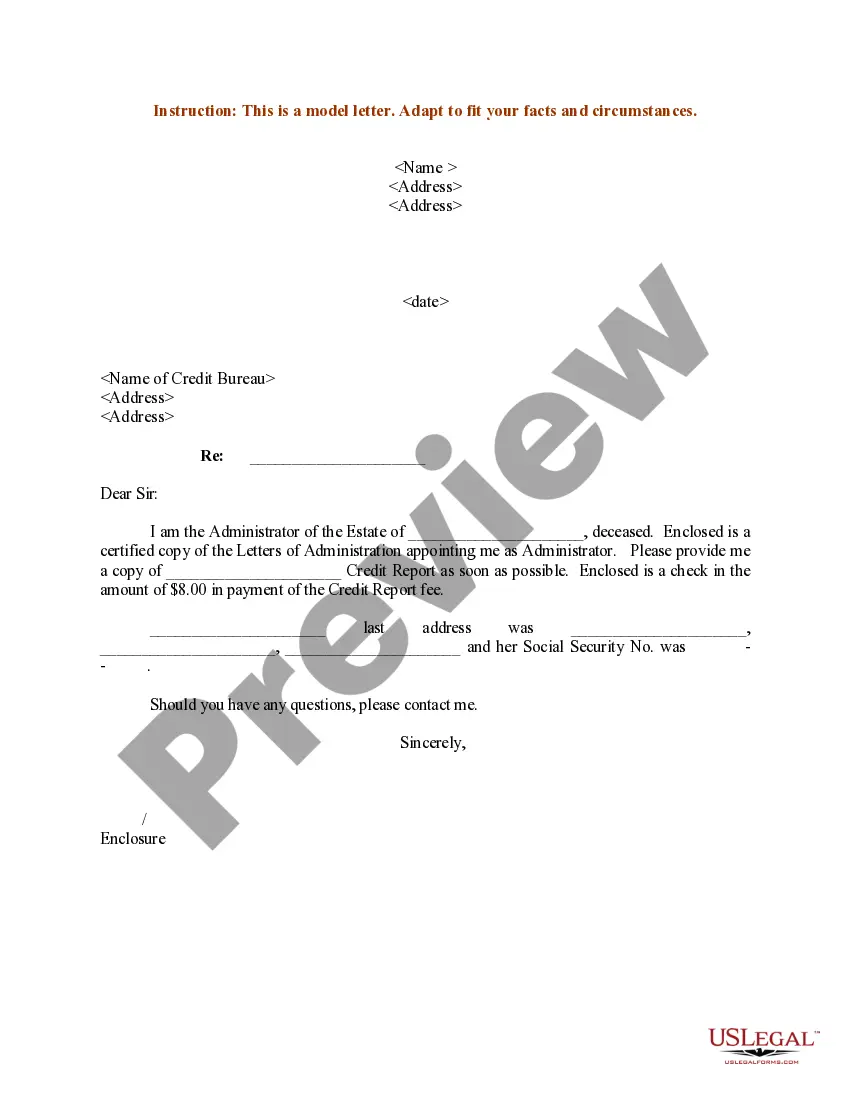
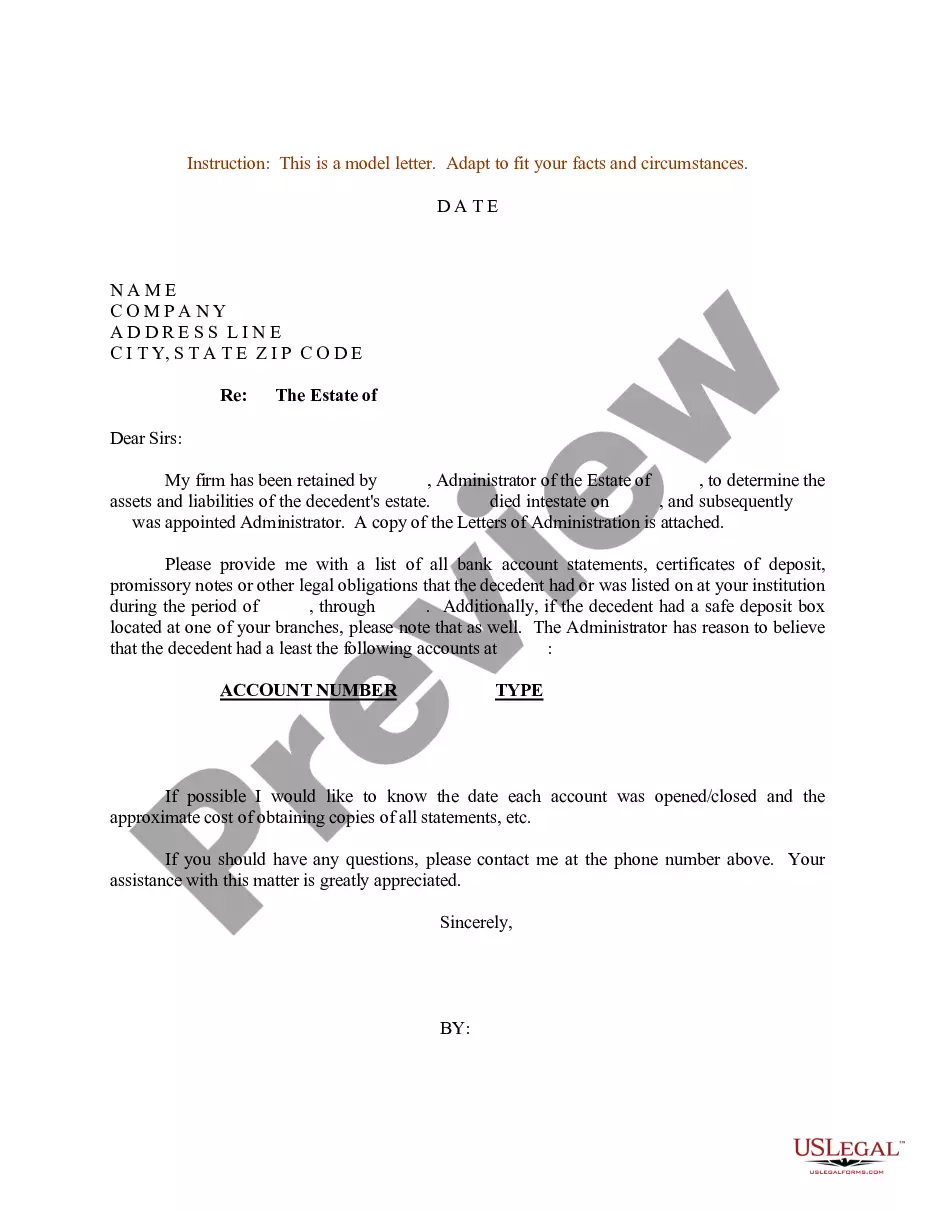
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
Key Takeaways If the account becomes part of the owner's estate, the legally designated executor can collect the funds and place them into an estate account. The joint owner, beneficiary or executor must provide a copy of the death certificate when taking action on the owner's account.
The death certificate gives us the information needed to verify the identity and legal residence of our customer as well as confirm date of death. Other legal documents. We may require additional documents such as a last will and testament, formal trust, birth or marriage certificate, or proof of legal name change.
Typically, a beneficiary can claim the proceeds from a payable-on-death account—sometimes called a “POD” account—by going to the bank with a death certificate and proof of identification.
Respected Sir/Madam, I am writing to you with a heavy heart to inform you of the demise of my husband, Mr. Rajeev Singh, who had a savings account in your esteemed bank. It is a difficult time for our family, and I need to settle his financial affairs.
Typically, a beneficiary can claim the proceeds from a payable-on-death account—sometimes called a “POD” account—by going to the bank with a death certificate and proof of identification.
After someone dies, a sole-owned bank account may go to a named beneficiary or be handled by the executor of the estate. Joint accounts typically have automatic rights of survivorship, but it's still important to check with your bank to ensure smooth access to funds.
If there's no will, the bank could ask for evidence of your relationship to the deceased. You'll also need the death certificate. When you've registered the death, you will be issued with a death certificate. This will act as formal notification for the bank to begin closing the account.
While every bank differs differently, and why there is a need to close a bank account after death. If the account was a joint one, it wouldn't need to be canceled because it will automatically transfer into the sole name of the other account holder after the bank has been notified of the death.
"The surviving owner will be able to withdraw funds from the account," says David Doehring, probate attorney and managing partner of Doehring & Doehring Attorneys at Law. If the account has a payable on death beneficiary, the bank account balance goes to the beneficiary after the last account owner dies.