Foreign Independent Contractor Agreement With Foreign Country In New York
Description

Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
Contractors must complete a Form W-9 if they're US citizens or residents and a Form W8-BEN if they're based entirely abroad. Both forms are available to download from the IRS website. From the moment the contract begins, you must store these documents for at least four years.
Can a U.S. employer hire someone living abroad as an Independent Contractor? The short answer is Yes. Being able to employ foreign talent can be transformative for a U.S. company. However, there are various legal implications and risks with cross-border relationships.
Conversely, if the independent contractor is not a US person and did not perform any of their services within the US, you will not be required to issue Form 1099. Instead, the foreign contractor will have to complete and file Form W-8BEN.
All persons ('withholding agents') making US-source fixed, determinable, annual, or periodical (FDAP) payments to foreign persons generally must report and withhold 30% of the gross US-source FDAP payments, such as dividends, interest, royalties, etc.
Exemption from withholding To qualify for this exempt status, the employee must have had no tax liability for the previous year and must expect to have no tax liability for the current year. A Form W-4 claiming exemption from withholding is valid for only the calendar year in which it's furnished to the employer.
Payments to a foreign corporation in exchange for personal services performed in the US by either a US citizen or alien is considered to be US-sourced income and is usually subject to withholding. (Can be wages or self-employment income.)
This is a key point in understanding how can a US company hire a foreign independent contractor. As long as the contractor complies with the tax and legal requirements of their home country and the U.S., they can provide services to a U.S. company without being considered an employee.
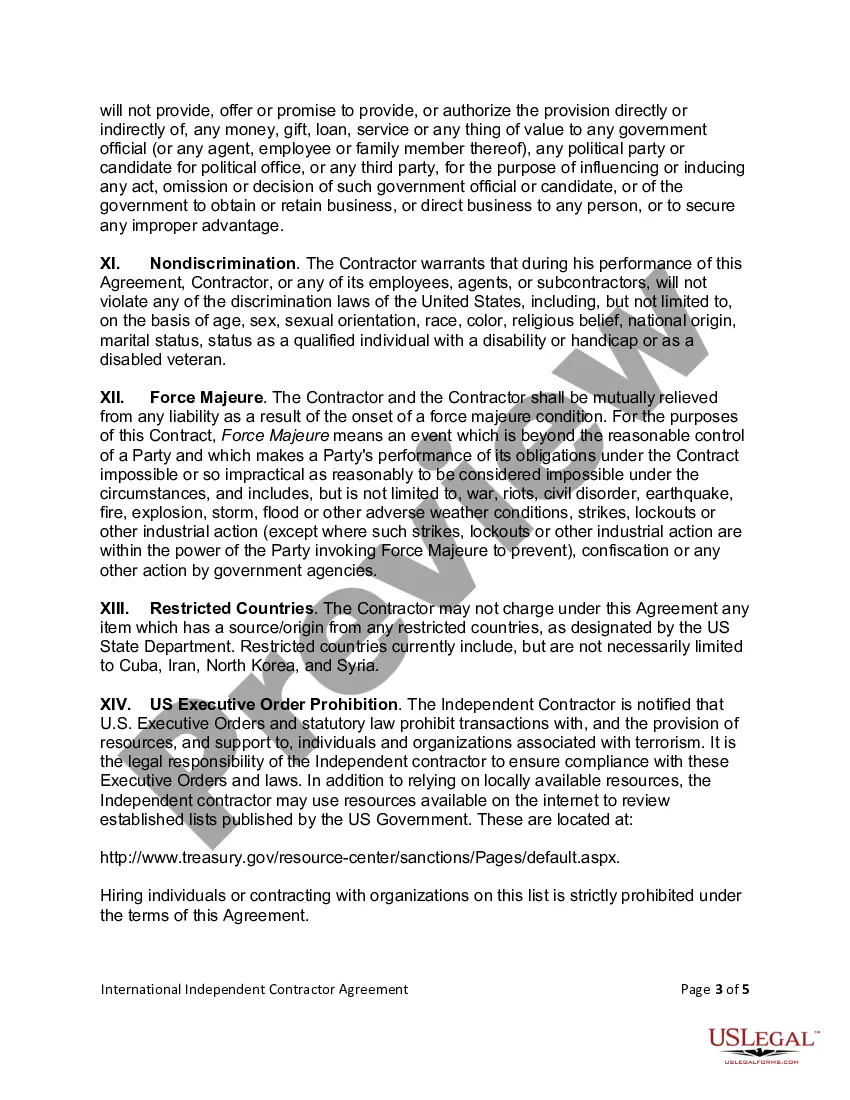
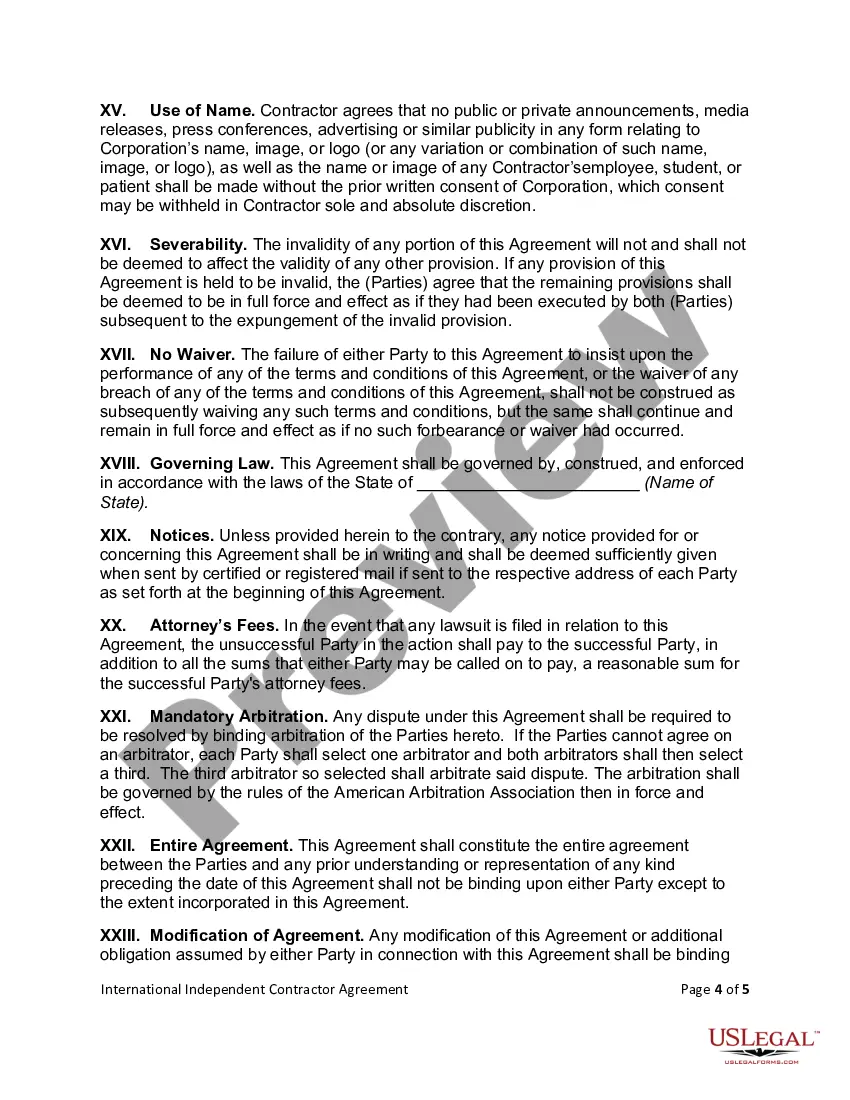
Below are eight important points to consider including in an independent contractor agreement. Define a Scope of Work. Set a Timeline for the Project. Specify Payment Terms. State Desired Results and Agree on Performance Measurement. Detail Insurance Requirements. Include a Statement of Independent Contractor Relationship.
The IRS requires a flat 30% withholding on ALL types of payments to foreign national individuals UNLESS: The individual has a U.S. tax identification number (SSN or ITIN) and qualifies for a tax reduction under the tax treaty between the U.S. and their country of tax residency.
New York does not require most contractors to hold a license on the state level.