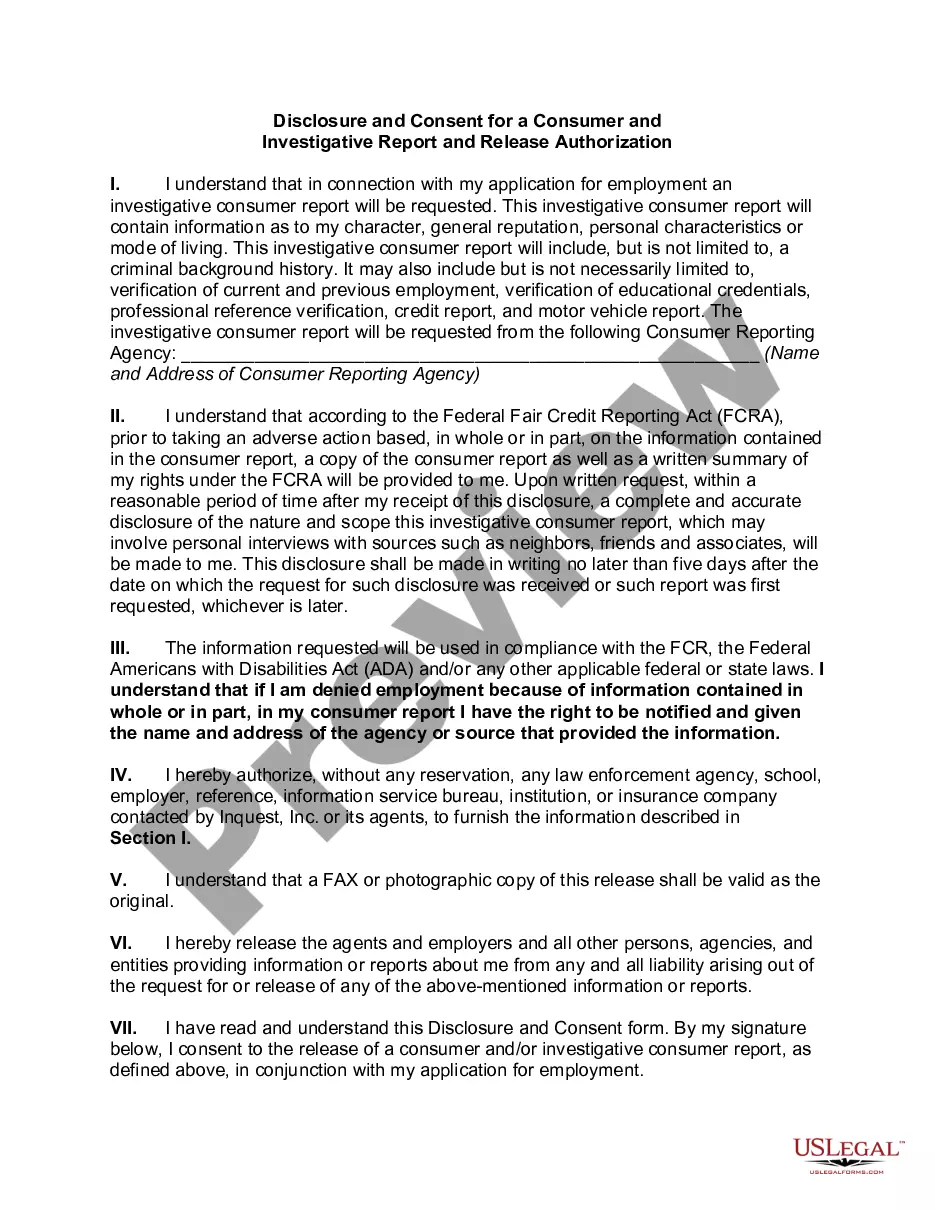
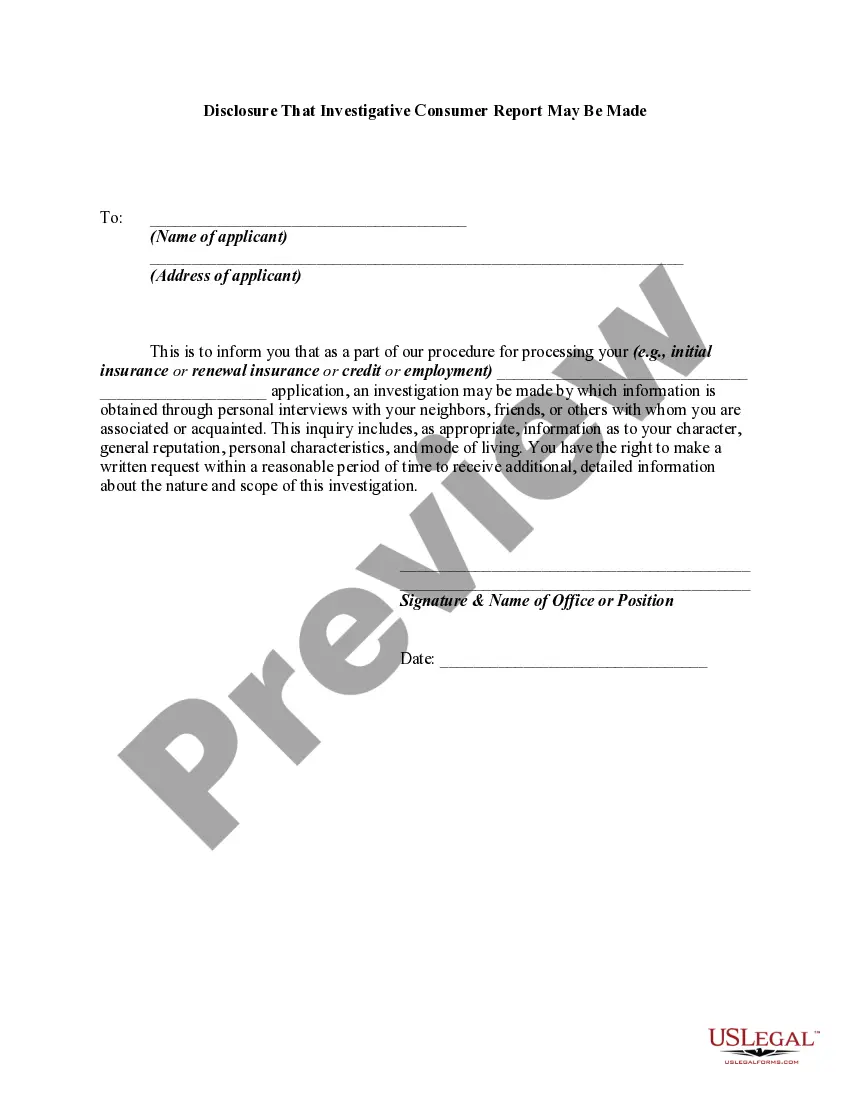
Consumer Reporting Agency Under Fcra In Clark
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
The FCRA's requirements for adverse action notices apply only to consumer transactions and are designed to alert consumers that negative information was the basis for the adverse action.
Background screening reports are “consumer reports” under the FCRA when they serve as a factor in determining a person's eligibility for employment, credit, insurance, housing, or other purposes and they include information “bearing on a consumer's credit worthiness, credit standing, credit capacity, character, general ...
The compliance requirements for the credit reporting agencies include the following: Establish FCRA Policies. Review FCRA Provisions & Applicability. Establish Smooth Consumer Consent Acquisition Processes. Ensure Reports Are Used Only for Permissible Purposes. Provide Adverse Action Notices.
The FCRA gives you the right to be told if information in your credit file is used against you to deny your application for credit, employment or insurance. The FCRA also gives you the right to request and access all the information a consumer reporting agency has about you (this is called "file disclosure").
Under Section 609(a) of FCRA, all consumer reporting agencies must clearly and accurately disclose to a consumer, upon request, “all information in the consumer's file at the time of request” and “the sources of the information.” Moreover, FCRA defines a consumer's file as “all of the information on that consumer ...
Reports including personal knowledge or firsthand interaction, reports made among persons under common control, and reports other than credit (including skip tracing, law enforcement, dating, and laboratory reports) are not consumer reports.
Reports including personal knowledge or firsthand interaction, reports made among persons under common control, and reports other than credit (including skip tracing, law enforcement, dating, and laboratory reports) are not consumer reports.
(a) Information excluded from consumer reports (2) Civil suits, civil judgments, and records of arrest that, from date of entry, antedate the report by more than seven years or until the governing statute of limitations has expired, whichever is the longer period.
What type of information is not found on a consumer credit report? Personal information irrelevant to credit. Information related to income and employment. Financial data not related to debt. Public records. Medical data. Expired and extraneous information. Interest rates and penalties. Soft inquiries.
While there are three national CRAs in the United States (Experian, Trans Union, and Equifax), private investigators, detective agencies, collection agencies, inspection bureaus, companies that sell information to insurance companies and assist in performing background checks, and college placement offices have been ...