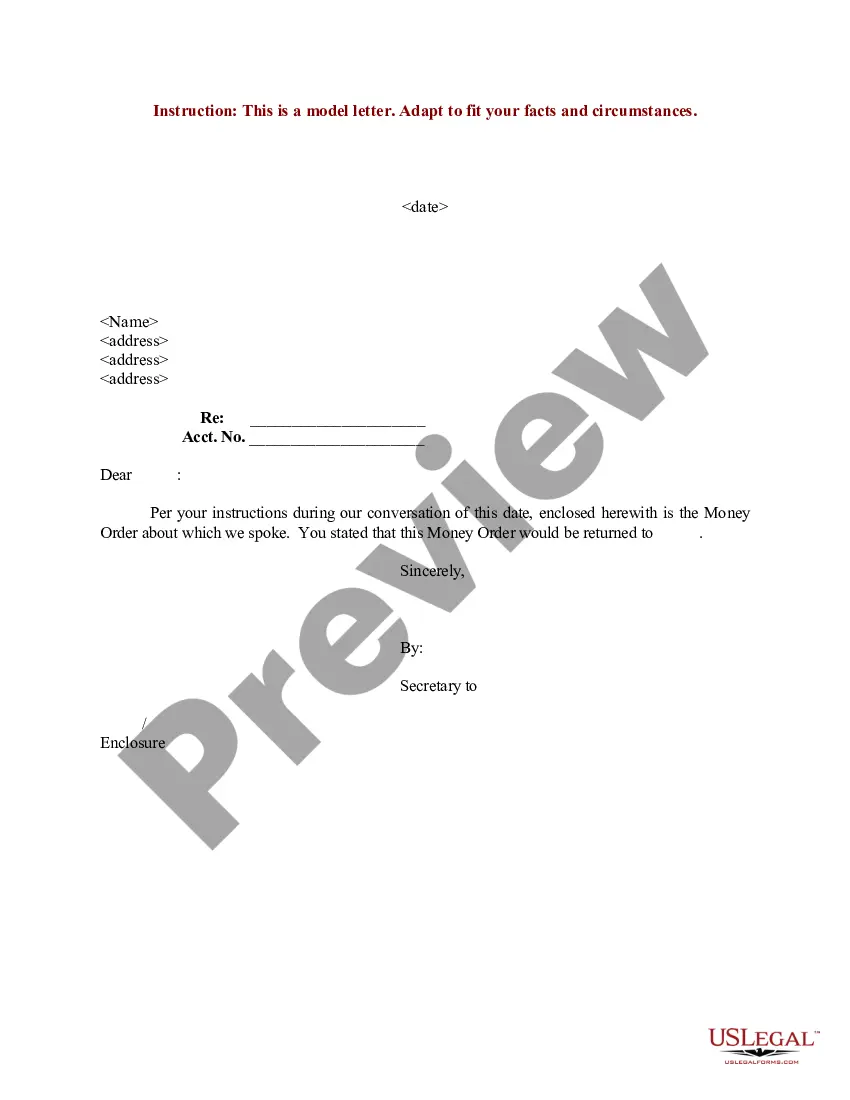
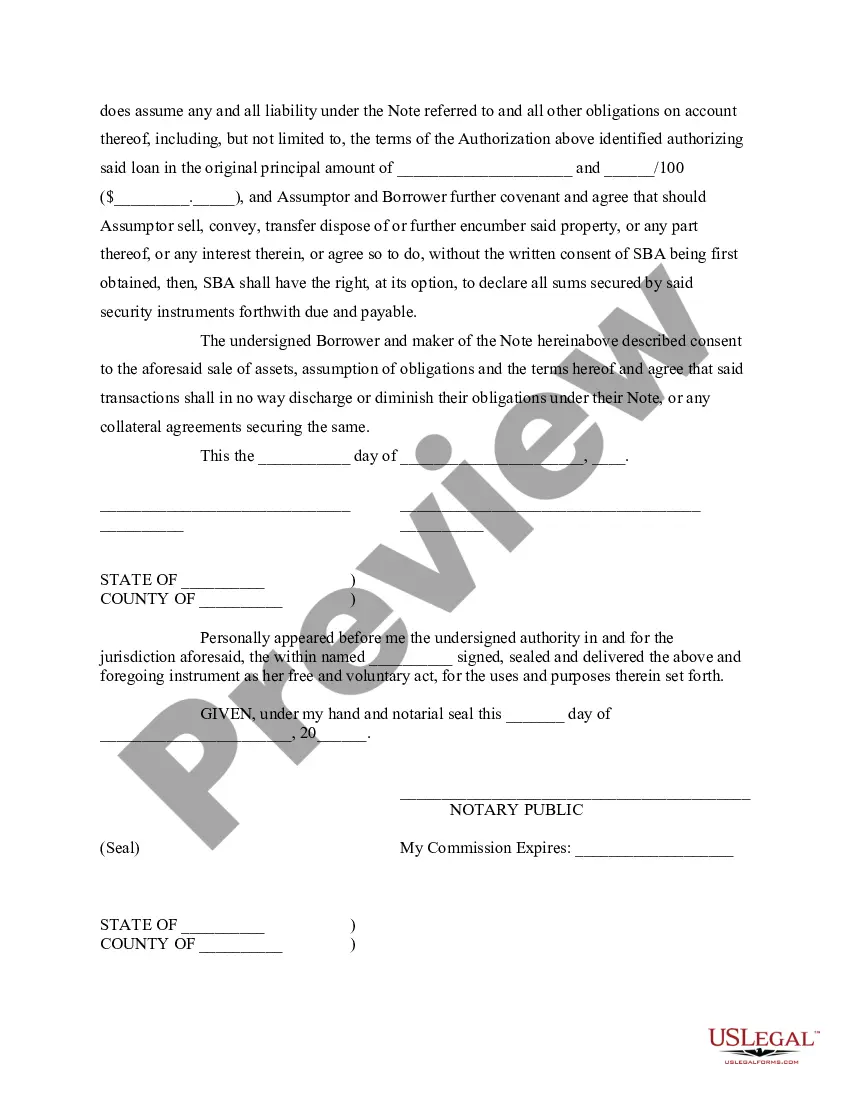
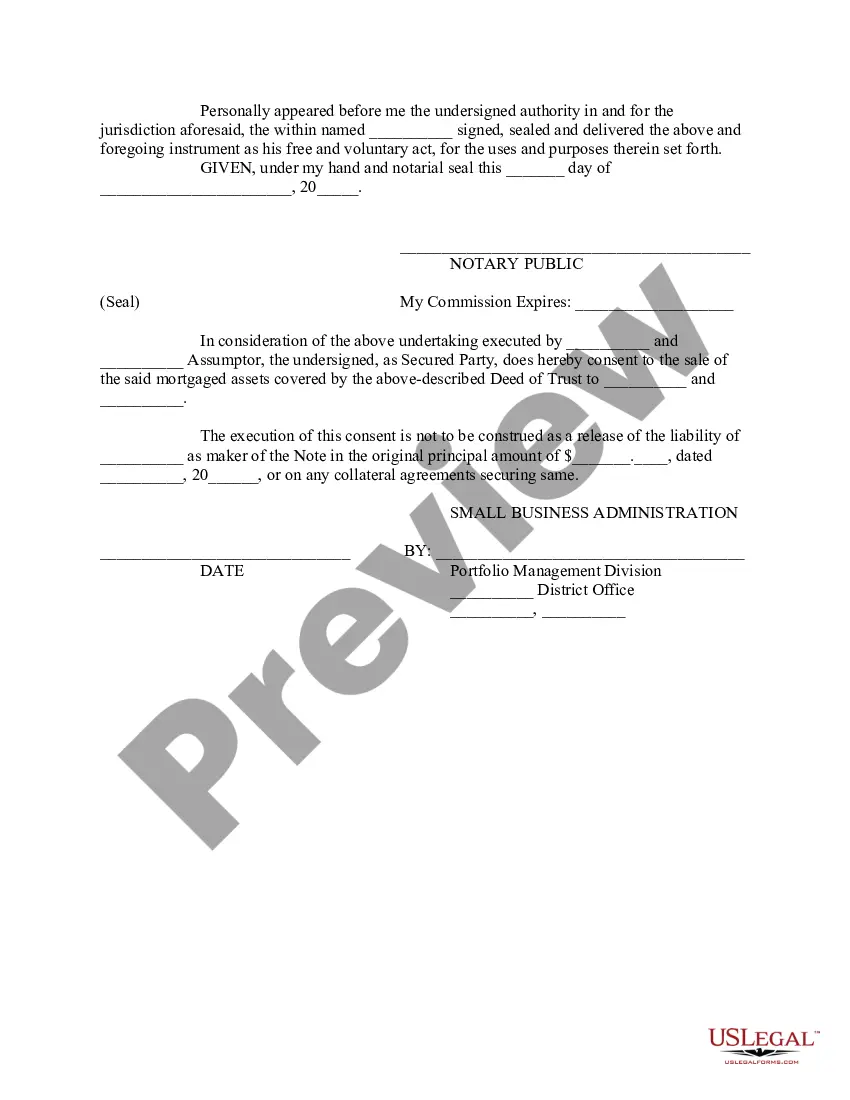
Sba Loan Assumption With A Mortgage In Dallas
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
Assumable loans sound good in theory, but seem to be not so great in practice. Harder to qualify for, need massive down payments or the ability to get a second mortgage, they usually take a very long time to close. It sounds neat, but that's about it.
Most government-backed loans, such as FHA or VA loans, are assumable. Most conventional mortgages aren't. An assumable mortgage can offer a better interest rate than what's on the market today.
Buyers Can Assume a Mortgage Direct from Seller An assumable mortgage is one that a buyer can take over, or assume, from the seller. This is typically an involved process, and it is not necessarily possible, depending on the situation; but it can be an excellent benefit to sellers and buyers.
An assumable mortgage is a type of home financing arrangement where an outstanding mortgage and its terms are transferred from the current owner to the buyer. By assuming the previous owner's remaining debt, the buyer can avoid obtaining their own mortgage, which may come with higher interest rates.
To assume a mortgage, your lender has to give you the green light. That means meeting the same requirements that you'd need to meet for a typical mortgage, such as having a good enough credit score and a low debt-to-income (DTI) ratio.
It depends. A mortgage takeover can be beneficial in certain situations, such as when the seller's original mortgage has a lower interest rate than what is currently available on the market. However, the process of assuming a mortgage can be complex and costly, and not all buyers will qualify.
Unless you're assuming a mortgage privately from someone you already have a close relationship with, you'll likely go through underwriting to transfer financial responsibility. The seller's lender will put you through an approval process that requires documentation and information typical of a mortgage application.
The mortgage balance, interest rate, and repayment schedule all carry over to the buyer. However, only Federal Housing Administration (FHA) loans, U.S. Department of Agriculture (USDA) loans, and U.S. Department of Veterans Affairs (VA) loans can qualify. Conventional mortgages cannot be assumed.