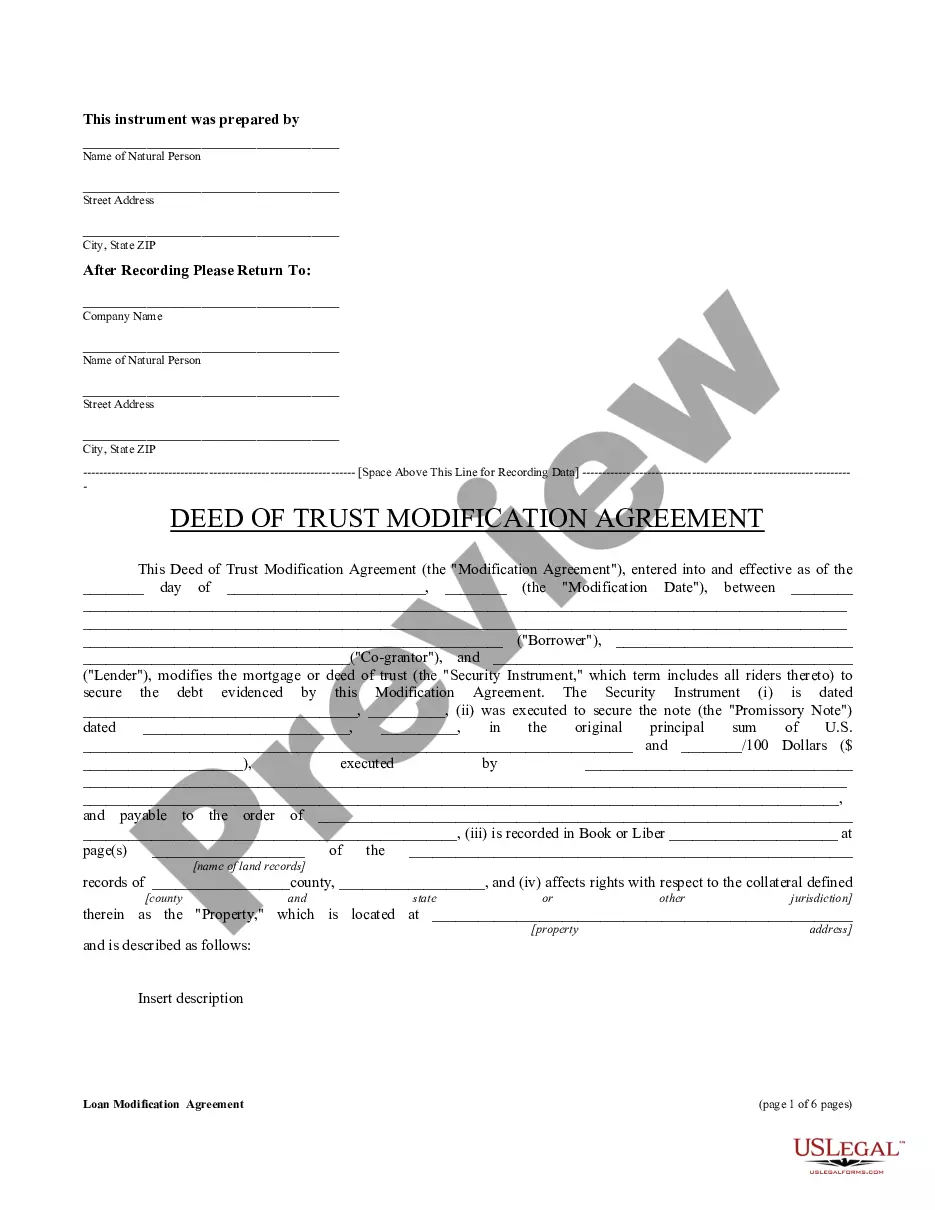
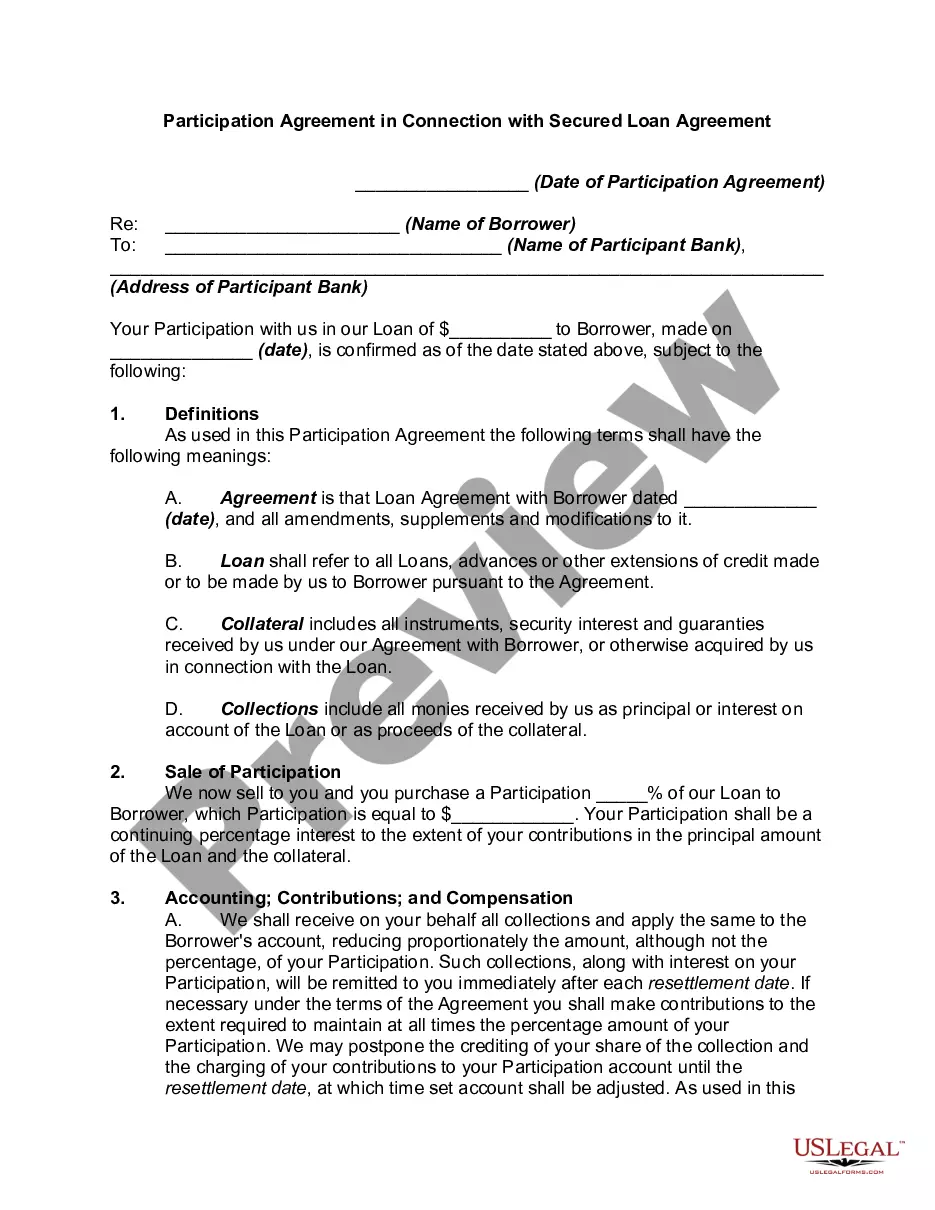
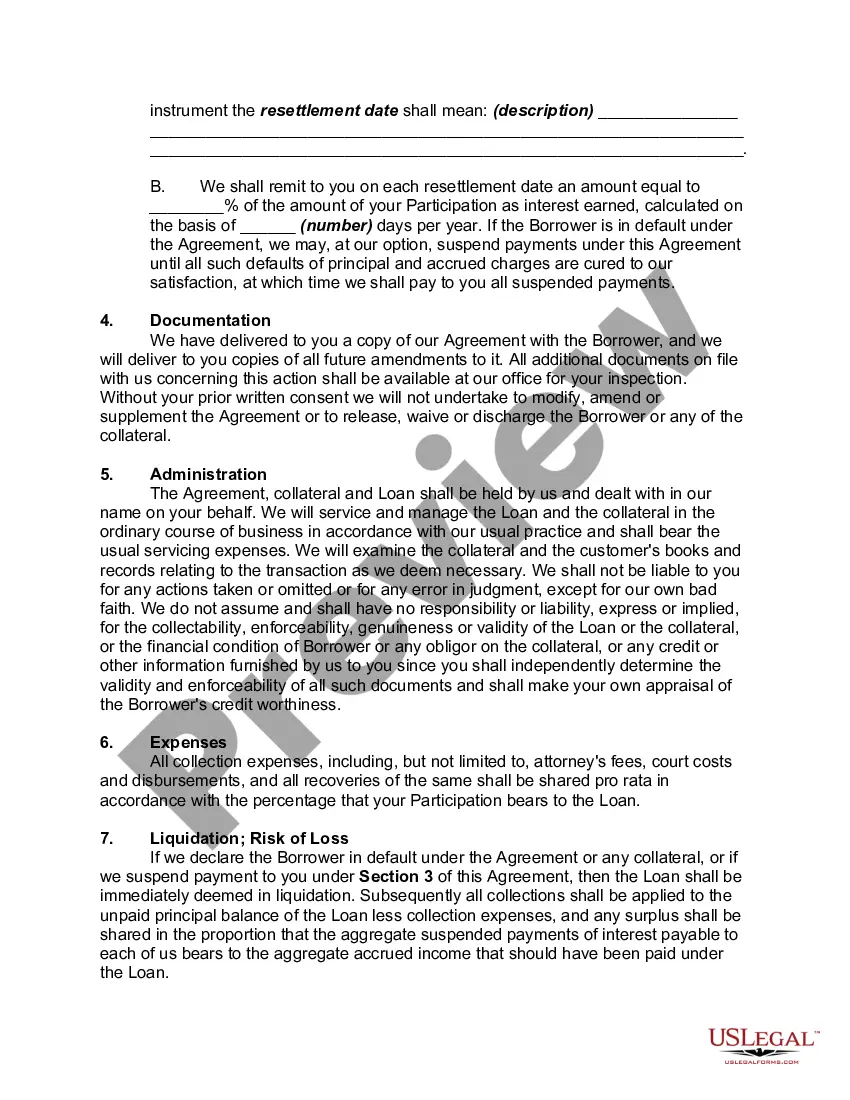
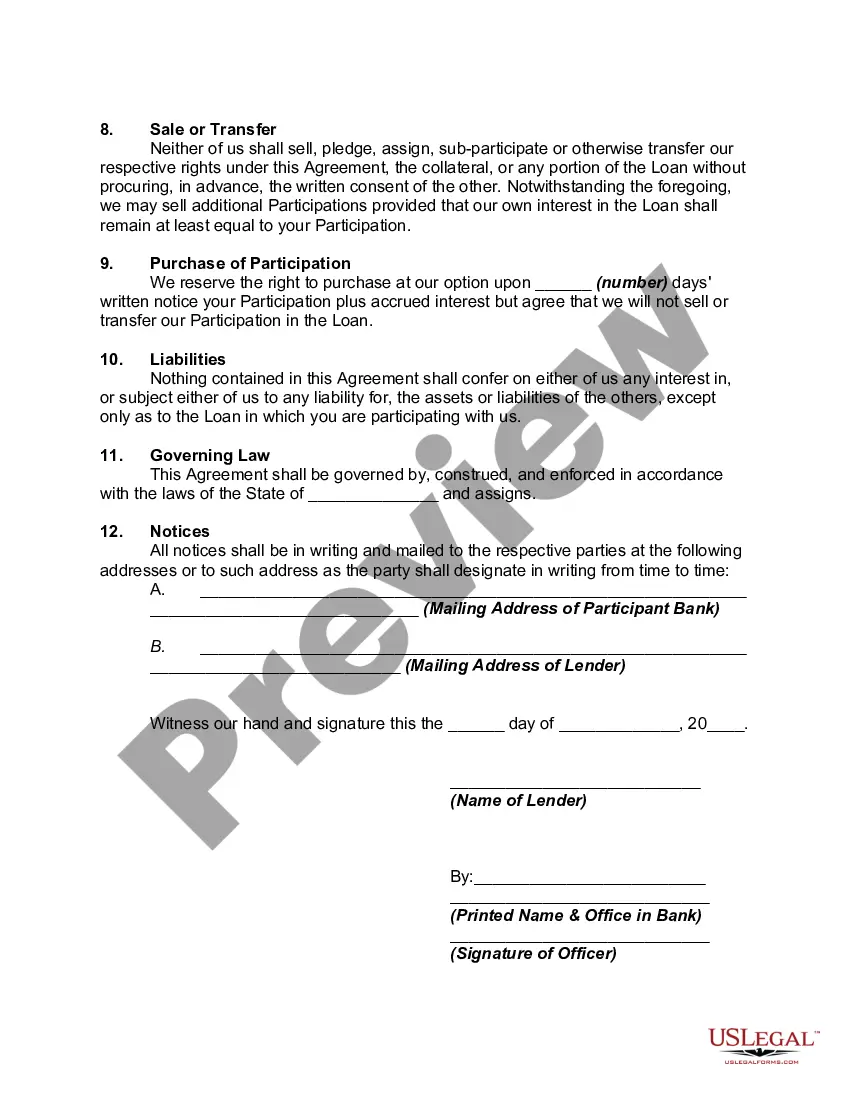
Loan Participation Agreement Template With Personal Guarantee In Washington
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?



Form popularity
FAQ
As long as the guarantee is in writing and is signed by a guarantor with the intention and capacity to sign it, there won't usually be any problems for the lender. Even if you resign from the company or close it down, the lender will still usually be able to enforce the guarantee.
A guaranty, much like any other contract, can be revoked later if both the guarantor and the lender agree in writing. Some debts owed by personal guarantors can also be discharged in bankruptcy.
Personal guarantees are binding contracts, and from the moment the guarantee is in writing it becomes legally enforceable. There is no set time period during which a guarantee can be valid - it depends on the specifics set out in the particular guarantee.
Try to eliminate certain assets. Request that certain assets, such as your personal residence or stock in the business, be outside the reach of the guarantee. You can suggest that your personal obligation be capped at a certain percentage of your net personal wealth. You can also offer alternate security for the debt.
The most direct risk of a personal guarantee is the potential loss of personal assets. This can include savings, real estate, vehicles, and even retirement accounts. In the event of a default, these assets could be seized by the lender to satisfy the debt.
Your personal guarantee may be unenforceable due to circumstances outside of your contract. This may include being misled by the creditor, if a key fact was omitted from the contract, co-guarantor issues, suspicions of fraud, or if the facility provided by the bank changed significantly since you signed the guarantee.
Ing to Zach Reece, a small business owner and former certified public accountant, you can get rid of personal guarantees only if you sell your business and are released from the guarantee or file for bankruptcy.
Dear Sir/Madam: This letter will serve as your notification that (Bank Name) will irrevocably honor and guarantee payment of any check(s) written by our customer (Customer's Name) up to the amount of (Amount Guaranteed) and drawn on account number (Customer's Account Number). No stop payments will be issued.
Introduce yourself and state your relationship to the person you're guaranteeing. State what you will guarantee in your own words (like co-signing a lease). Explain why the guarantor letter may be needed in the first place. End the letter with a concise, detailed summary of what you're promising.