Factoring Agreement Investopedia Forfaiting In Nevada
Description
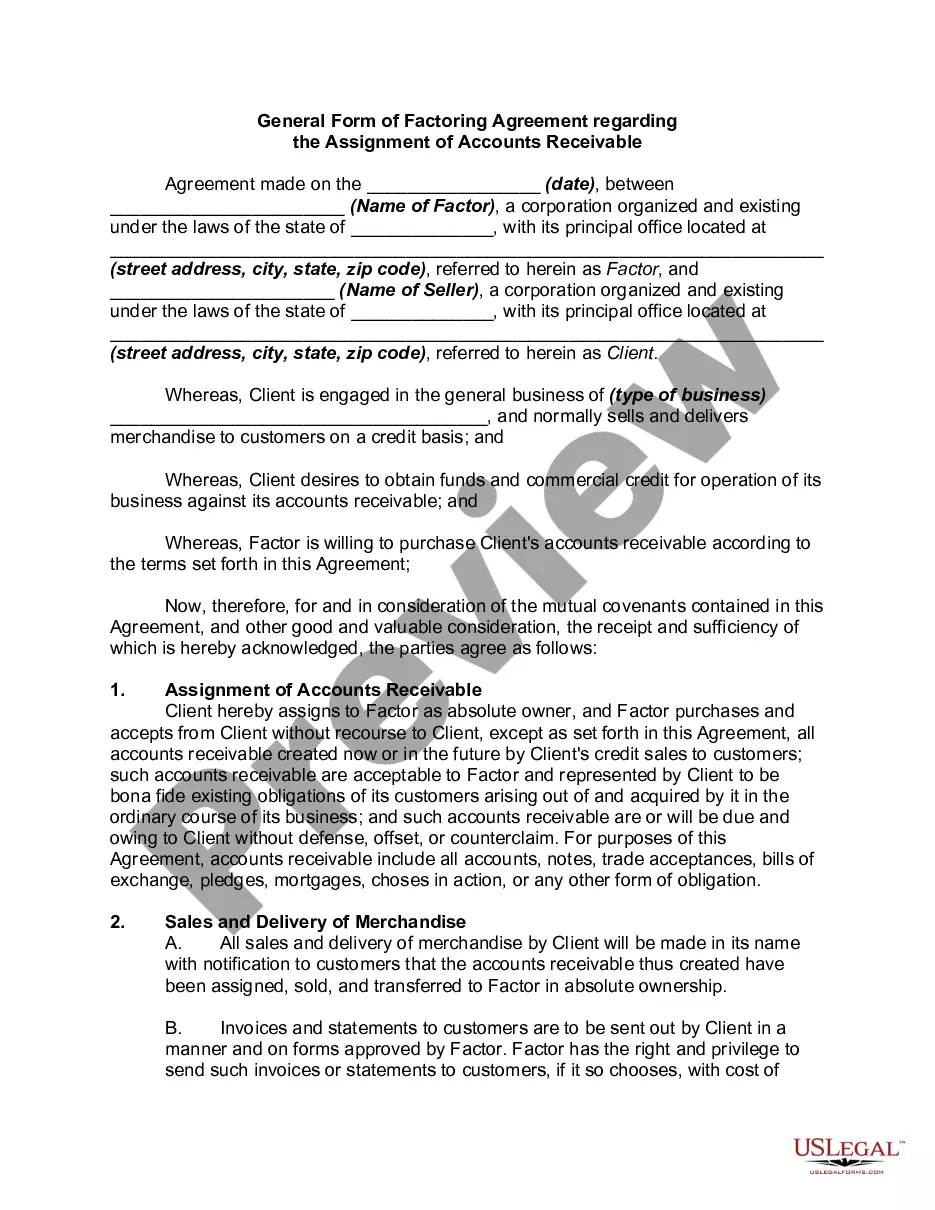
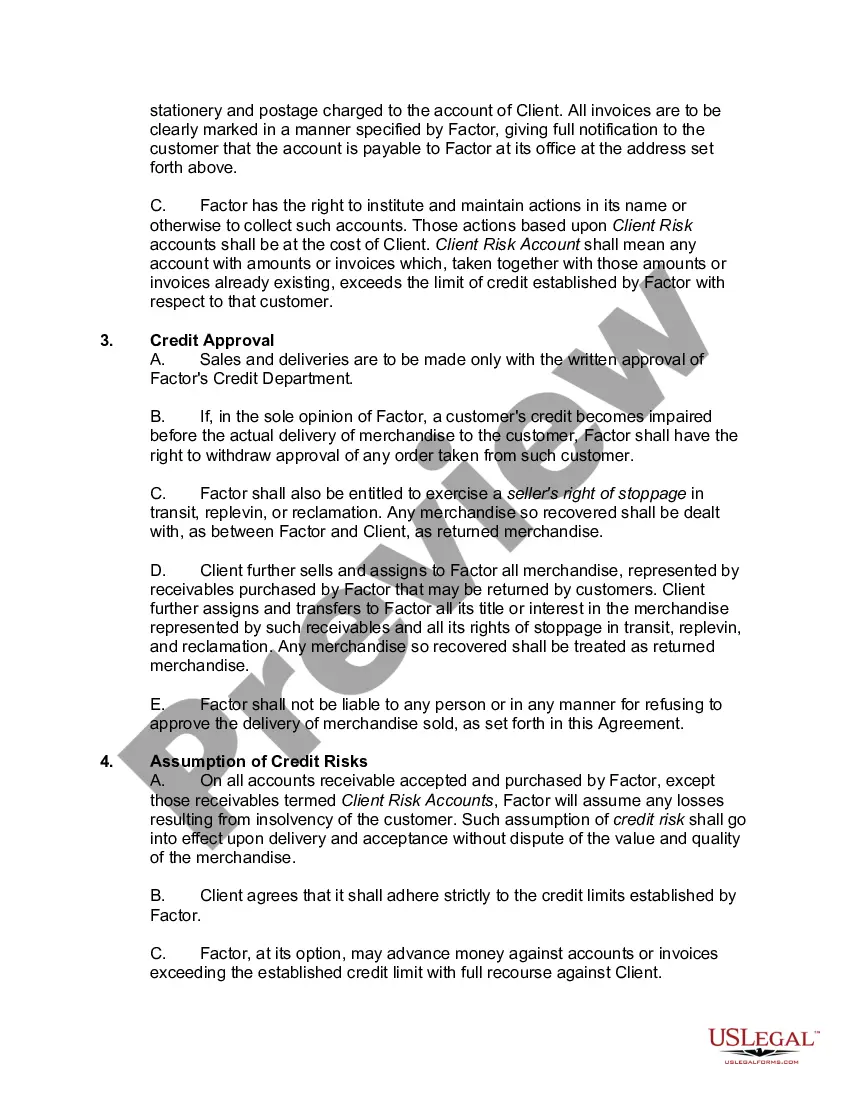
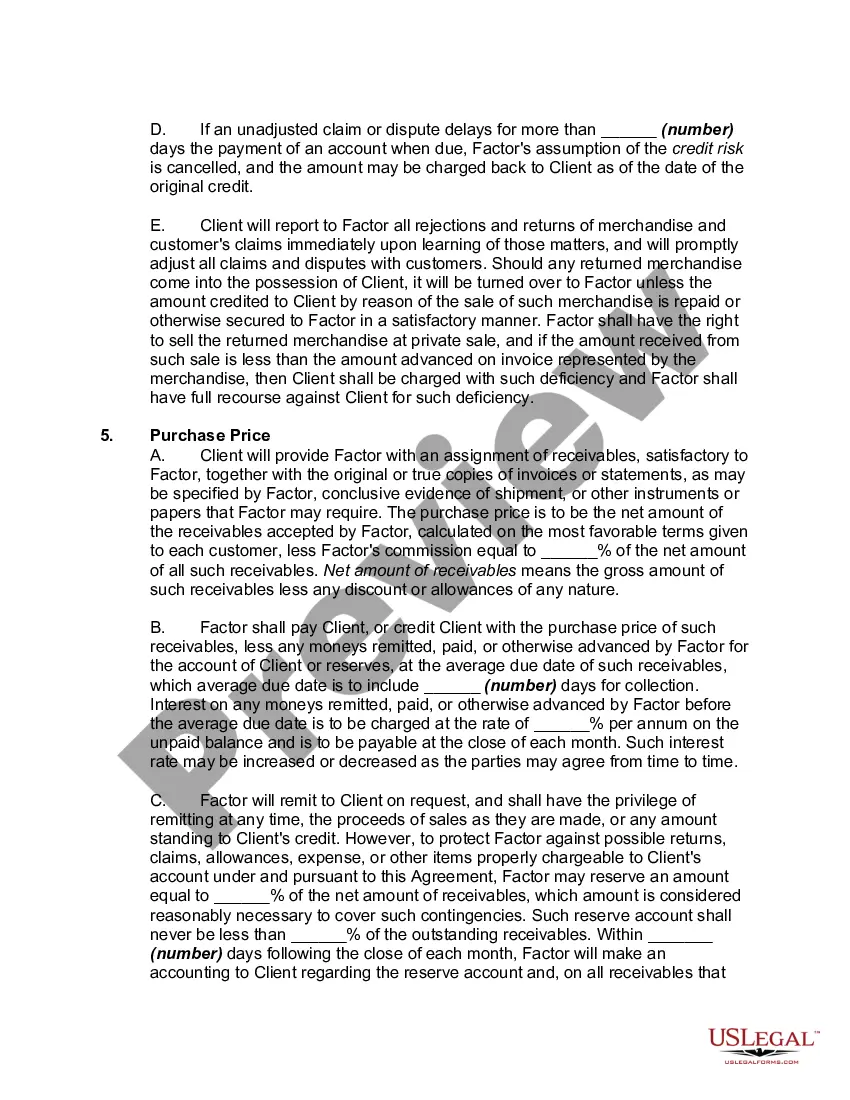

Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
In factoring, the factor (the third party buying the invoice) assumes some risk because they are responsible for collecting the payment from the customer. In forfaiting, the forfaiter (the third party buying the invoice) assumes no risk because they are not responsible for collecting the payment from the customer.
When you enter into an ABL agreement, you are making an investment in your business and your bank. Unlike factoring, which uses your customers' credit/payment history in the underwriting process, ABL lenders take into consideration your company's credit history, complete financial history and quality of your assets.
Bill discounting is always with recourse whereas factoring can be either with recourse or without recourse. 2. In bill discounting the drawer undertakes the responsibility of collecting the bills and remitting the proceeds to the financing agency, while the factor usually undertakes to collect the bills of the client.
The clients' credit risk was not transferred because the factor has the right of return. As a result, Tradex keeps the receivables in the balance sheet, because the derecognition criteria in IFRS 9 are not met. The amount received from factoring company is recognized as a liability.
Difference between forfaiting and discounting Forfaiting is a non-recourse financing arrangement, in which the exporter is no longer liable for the receivables if the importer defaults. Discounting is a recourse financing arrangement, in which the exporter remains liable for the receivables if the importer defaults.
What are the disadvantages of forfaiting? Forfaiting can be expensive due to higher interest rates and fees. It's limited to international trade and typically requires bank guarantees, making it less accessible for small businesses without strong financial backing.
Recourse factoring is the most common and means that your company must buy back any invoices that the factoring company is unable to collect payment on. You are ultimately responsible for any non-payment. Non-recourse factoring means the factoring company assumes most of the risk of non-payment by your customers.
Purpose: Factoring is typically used to obtain short-term financing, while forfaiting is used to manage long-term trade receivables. Types of assets: Factoring involves the sale of accounts receivable, while forfaiting involves the sale of trade receivables, such as promissory notes and bills of exchange.
What is a Letter of Credit? A Letter of Credit (LC) is a financial instrument used in international trade to provide payment security. It guarantees that the seller will receive payment from the buyer, as long as the seller fulfils the agreed-upon terms and conditions.
Letter of Credit (L/C) forfaiting allows an exporter to receive up–front payment for selling L/C–based receivables at a discount on a non–recourse basis.