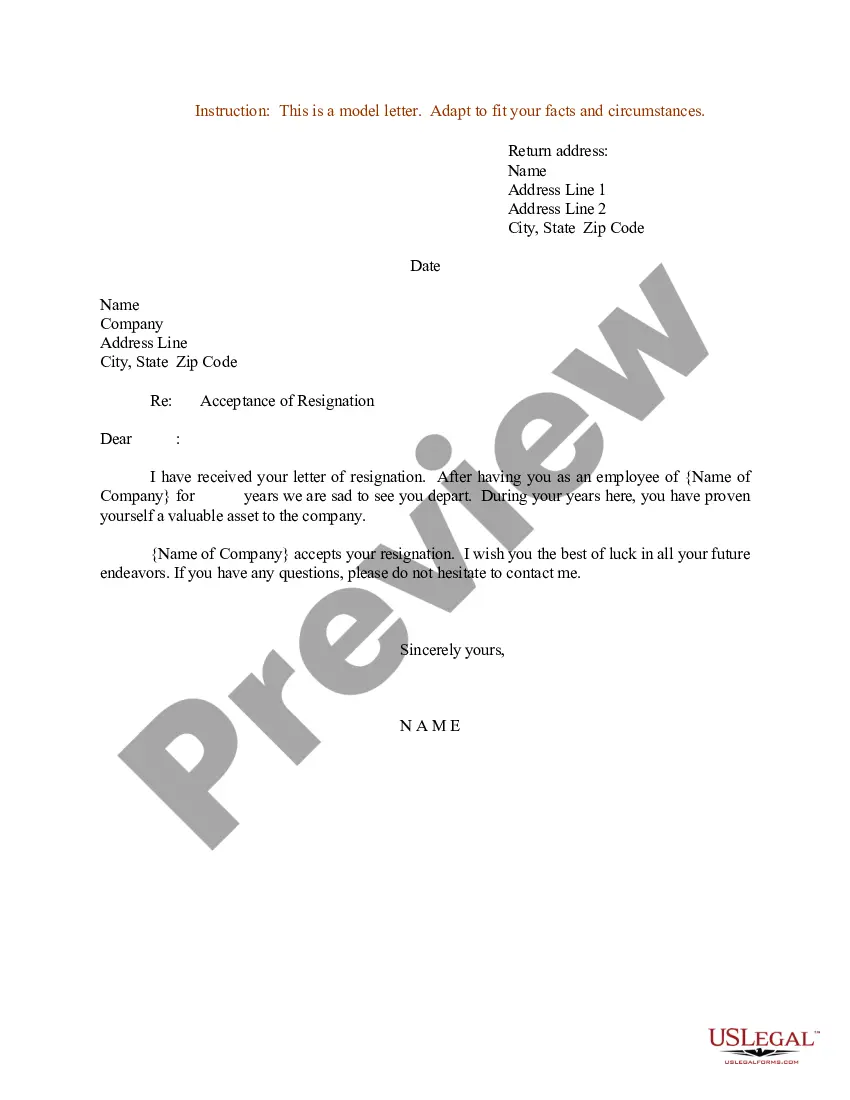
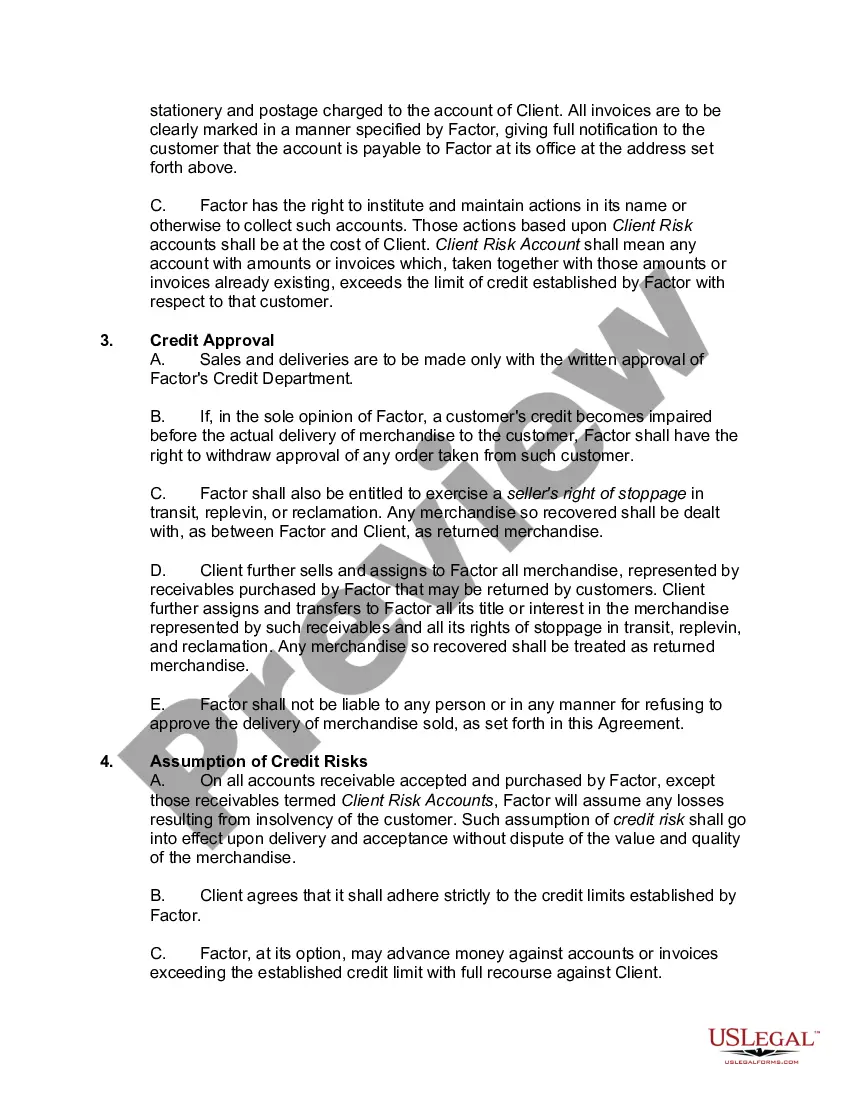
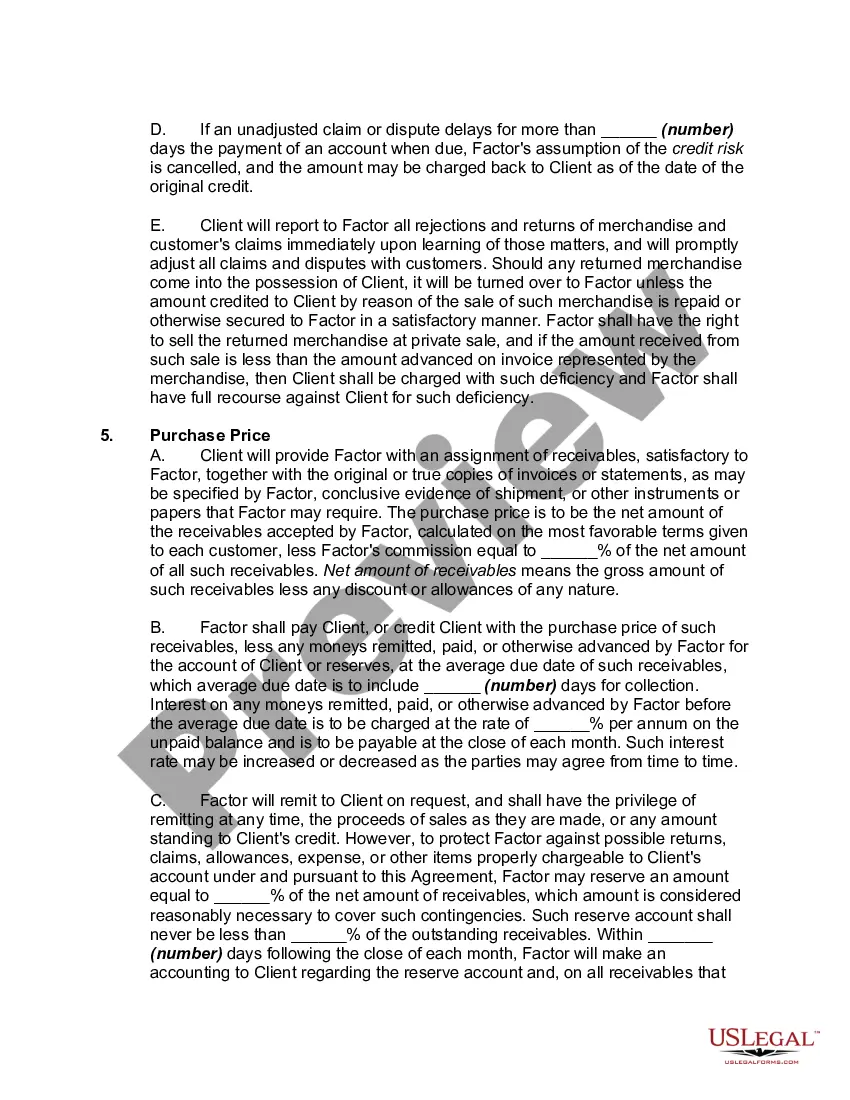
Factoring Agreement File With Irs In Maryland
Description

Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?




Form popularity
FAQ
How do I complete abatement form 843? Line 1 is the tax year the abatement is for. Line 2 is the total fees/penalties you are asking the IRS to remove. Line 3 is generally going to be Income (tax). Line 4 is the Internal Revenue Code section. Line 5a is the reason you are requesting the abatement.
In most cases, no. Recourse and nonrecourse factored receivables are treated as regular income.
Generally, C corporations, S Corporations, and LLCs formed as corporations or S Corps don't need to receive a 1099-NEC or 1099-MISC.
Form 433-A is used to obtain current financial information necessary for determining how a wage earner or self-employed individual can satisfy an outstanding tax liability.
In most cases, no. Recourse and nonrecourse factored receivables are treated as regular income. The only difference is if a customer defaults on their debt, in which case that debt may be written off by whoever owns it.
It's the broker's responsibility to send the 1099 to carriers, but it is not legally required. The Income Tax Regulations, under Section 1.6041-3(c), provide an exemption for freight payments from the requirement of 1099 information reporting.
Your reporting of factoring expenses as a deduction Commissions, set-up fees, and other factoring expenses are all tax deductible. But the reporting method differs depending on whether you retain the ownership of your receivables or end up selling them to a factoring company as described above.
In most cases, no. Recourse and nonrecourse factored receivables are treated as regular income.
Generally, C corporations, S Corporations, and LLCs formed as corporations or S Corps don't need to receive a 1099-NEC or 1099-MISC.