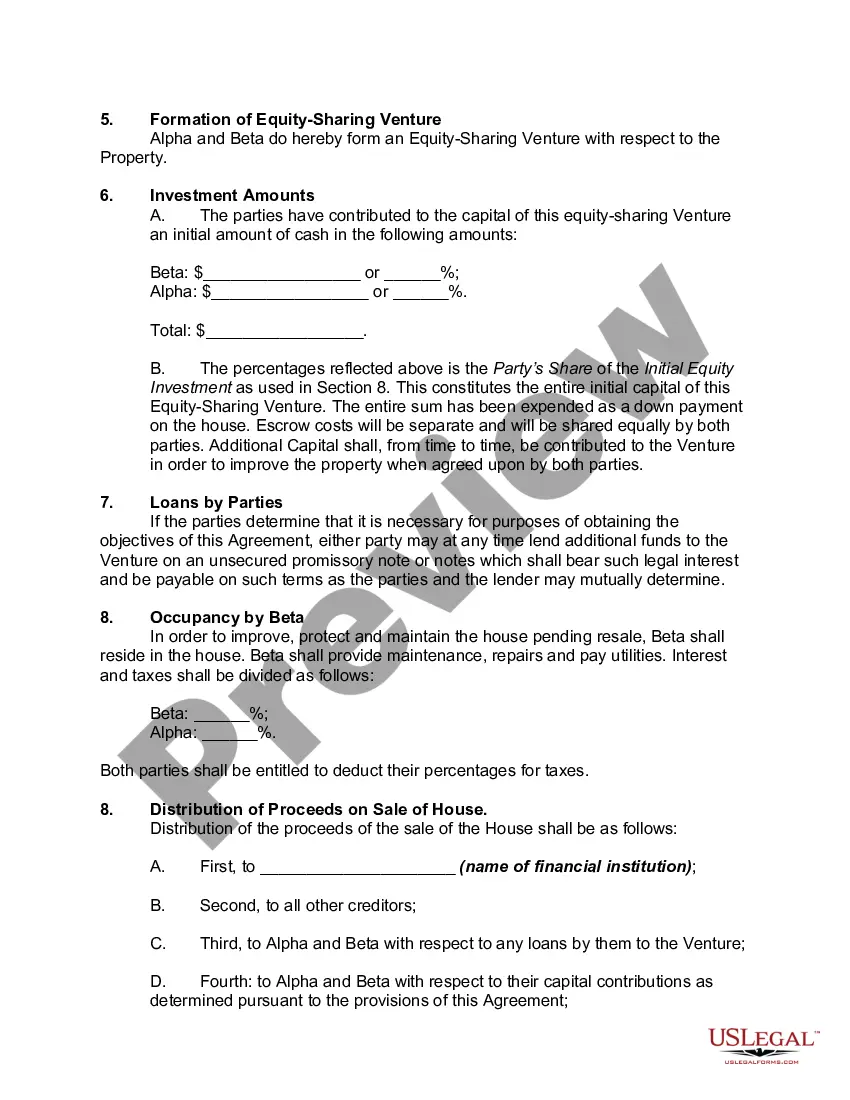
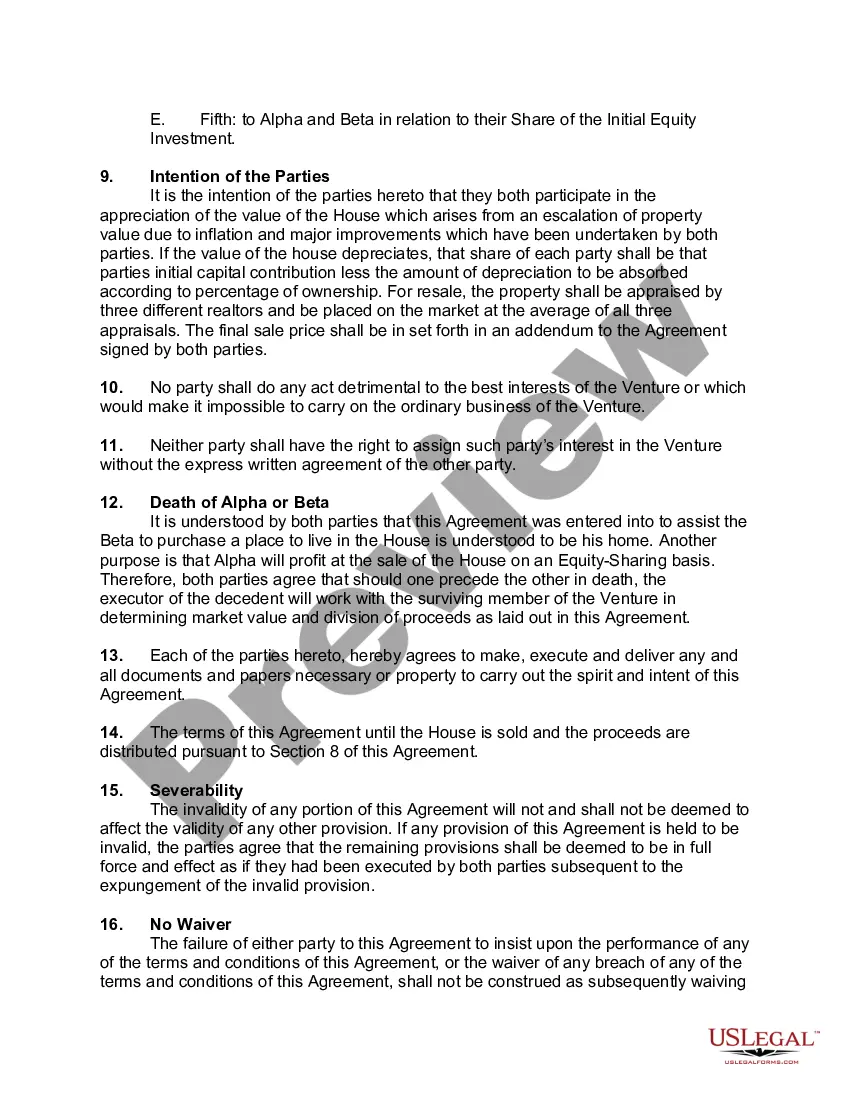
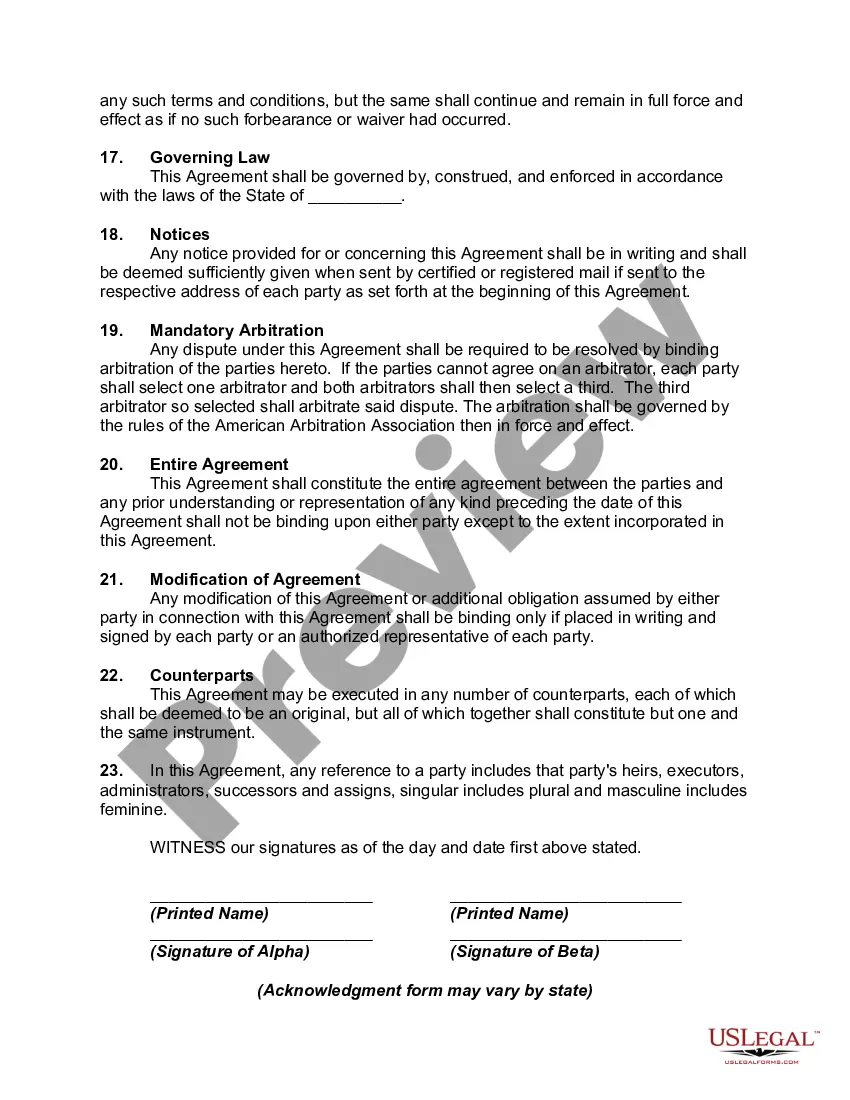
Equity Sharing Agreement With Investor In Georgia
Description

Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
Home equity sharing agreements involve selling a percentage of your home's value or appreciation to an investor in exchange for a lump sum upfront. The agreement typically is settled, with the homeowner paying back the investor, after the home is sold or at the end of a 10- to 30-year period.
How our HEI process works Get your initial offer and apply. See if you qualify in 60 seconds or less and get your initial offer with no obligation and no effect on your credit. Verify information and receive a home appraisal. Gather the documents you'll need and submit them online. Get your funds.
A HEA might make more sense if you need a lump sum now, prefer not to take on monthly debt, or have limited income or credit history. Both can be smart ways to tap into your home's equity. Just make sure to read the fine print, weigh the long-term costs, and choose the option that best aligns with your plans.
A HEA might make more sense if you need a lump sum now, prefer not to take on monthly debt, or have limited income or credit history. Both can be smart ways to tap into your home's equity. Just make sure to read the fine print, weigh the long-term costs, and choose the option that best aligns with your plans.
One major drawback is that releasing equity will reduce the value of your estate, meaning there will be less left over to leave as a gift within your Will. Usually, the Lifetime Mortgage will be repaid with the sale of the home after you die or enter long-term care.
Key Takeaways An equity investment contract involves trading ownership in a company for funding, without repayment obligations. These agreements typically include key terms like valuation, share class, investor rights, and exit strategies.