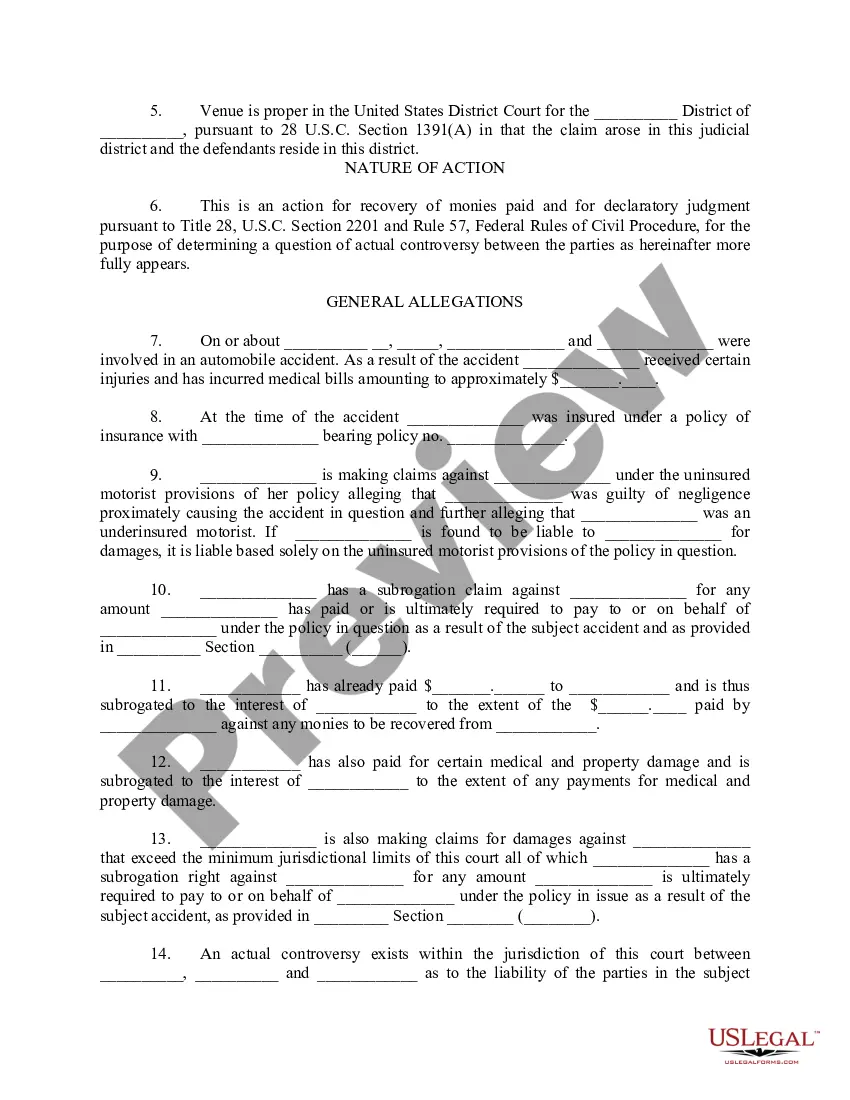
Accident With Uninsured Motorist In Nassau
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
Subrogation is a legal concept where the insurance company steps into the shoes of the insured to recover the costs of the claim from the party at fault. If the at-fault party is uninsured, the insurer may pursue subrogation against the driver personally.
The statute of limitations for UM or SUM claim is six years. For a UM claim, the statute begins either from the date of the accident, or from the time when subsequent events render the offending vehicle uninsured.
It may be better to file a claim with your own insurance company if you have uninsured motorist coverage. Unless the at-fault driver is stable financially or has well-off parents or guardians and can afford to cover your damages in full, you may want to avoid the unnecessary trouble of suing.
Ing to the U.S. Department of Justice, personal injury lawsuit outcome statistics include a majority (90 to 95 percent) settled before trial. Out of the small percentage that end up seeing a courtroom, the data suggests that the success rate of personal injury cases is around half.
Policy limits: Uninsured motorist coverage comes with limits, just like other insurance coverages. Severe accidents might exceed these limits, leaving you with uncovered expenses. Claim disputes: There might be disputes over the extent of your coverage and the amount you can claim, leading to potential legal battles.
While insurance companies may pursue uninsured drivers to recover claim costs, the process can be complex and time-consuming. Uninsured drivers involved in accidents should seek legal counsel promptly to protect their rights and explore possible compensation avenues.
While the vast majority of states, excluding Virginia and New Hampshire, require that all motor vehicle operators carry minimum limits of auto insurance coverage, an uninsured driver will not automatically be found at fault and liable for a car crash.
In situations where you are not insured but the other driver is at fault, you can still file a claim against the at-fault driver's insurance company for damages. Your lack of insurance does not negate your ability to pursue compensation under California law.