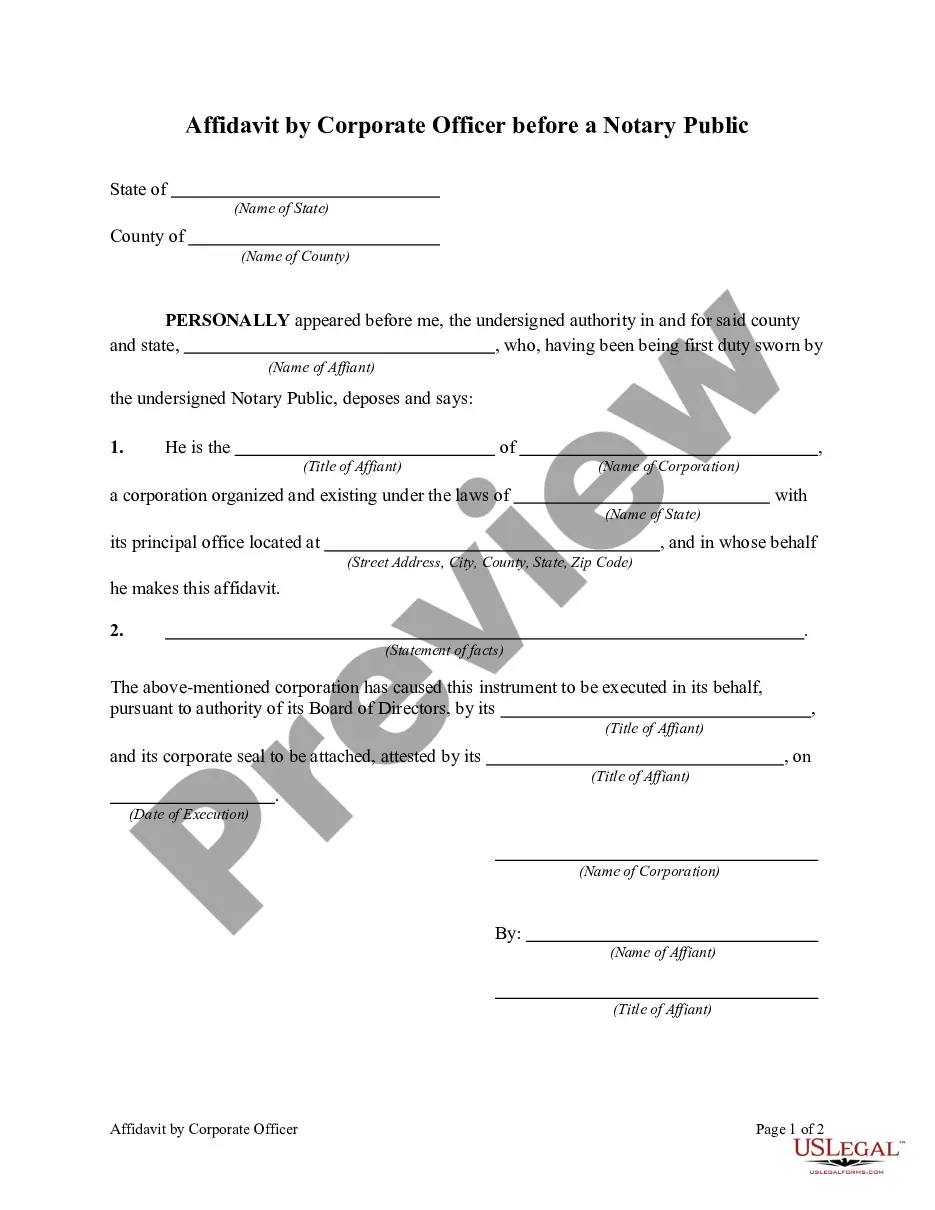
Repossession Letter In Spanish In Arizona
Description

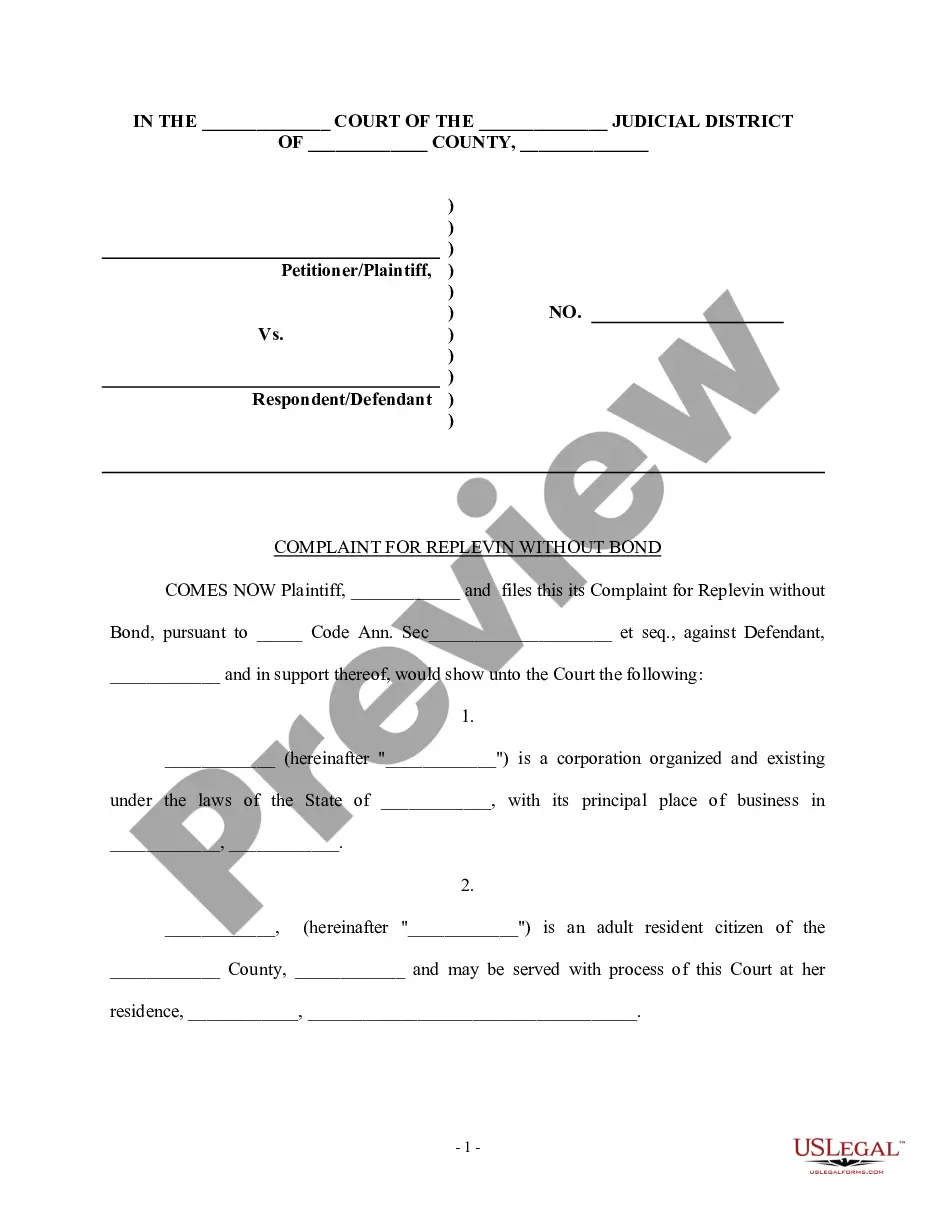
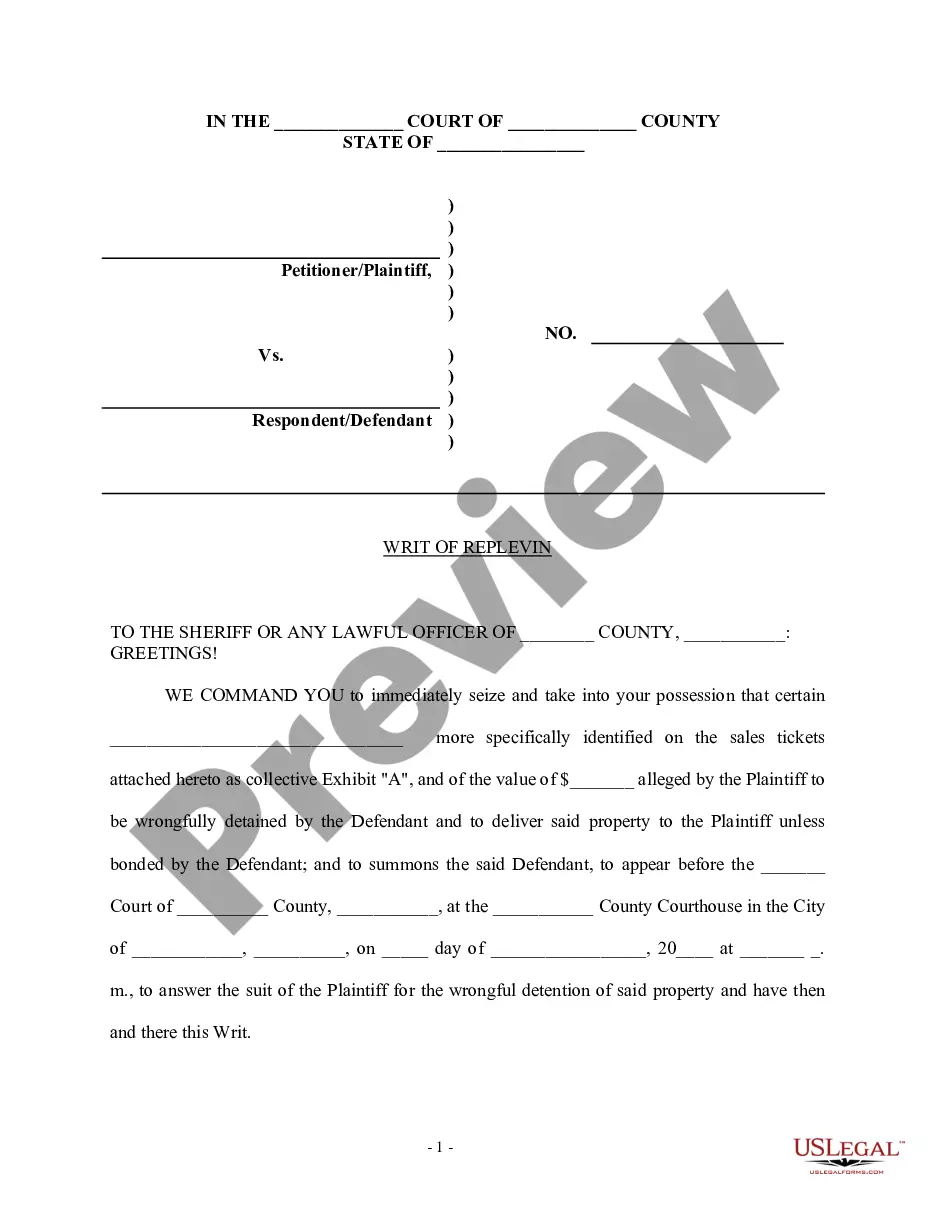
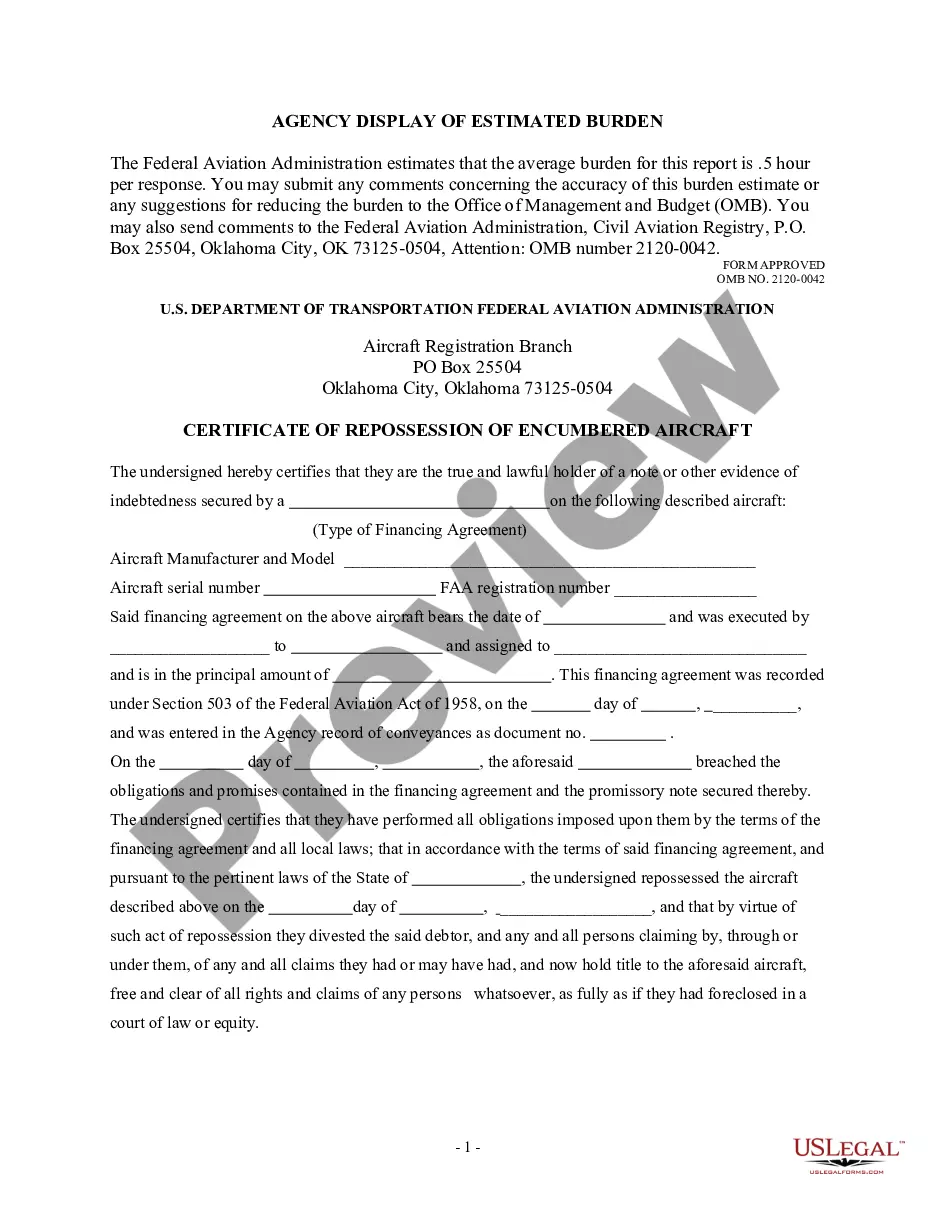
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
However, the lender has absolutely no obligation to do so. Even though you want to surrender the vehicle the lender won't pick it up.
Does voluntary repossession hurt your credit? Voluntary surrender counts as a derogatory or negative mark and will stay on your credit reports for up to seven years. This stain on your credit reports might prevent you from being approved for new credit and your terms, like interest rates, will likely be higher.
A repo stays on your credit report for seven years.
Future lenders might view a voluntary repossession more favorably than an involuntary one. Realistically, lenders look at your credit history as an indicator of whether you can repay your future debts in a timely manner, and not the circumstances that caused you to fall behind.
However, the lender has absolutely no obligation to do so. Even though you want to surrender the vehicle the lender won't pick it up.
You are hereby notified that your description of motor vehicle, year, make, model and VIN #, was lawfully repossessed on Date because you defaulted on your loan with Credit Union Name. The vehicle is being held at location address of vehicle. be sold at public sale. A sale could include a lease or license.
Banks and loan companies don't want a vehicle to go to repossession - they will take a loss on it if it does. So they want to work with you on payments first. Typically you have to be behind on payments - as In not paying at all - for some time before the unit goes to repo. That depends on a few things though.
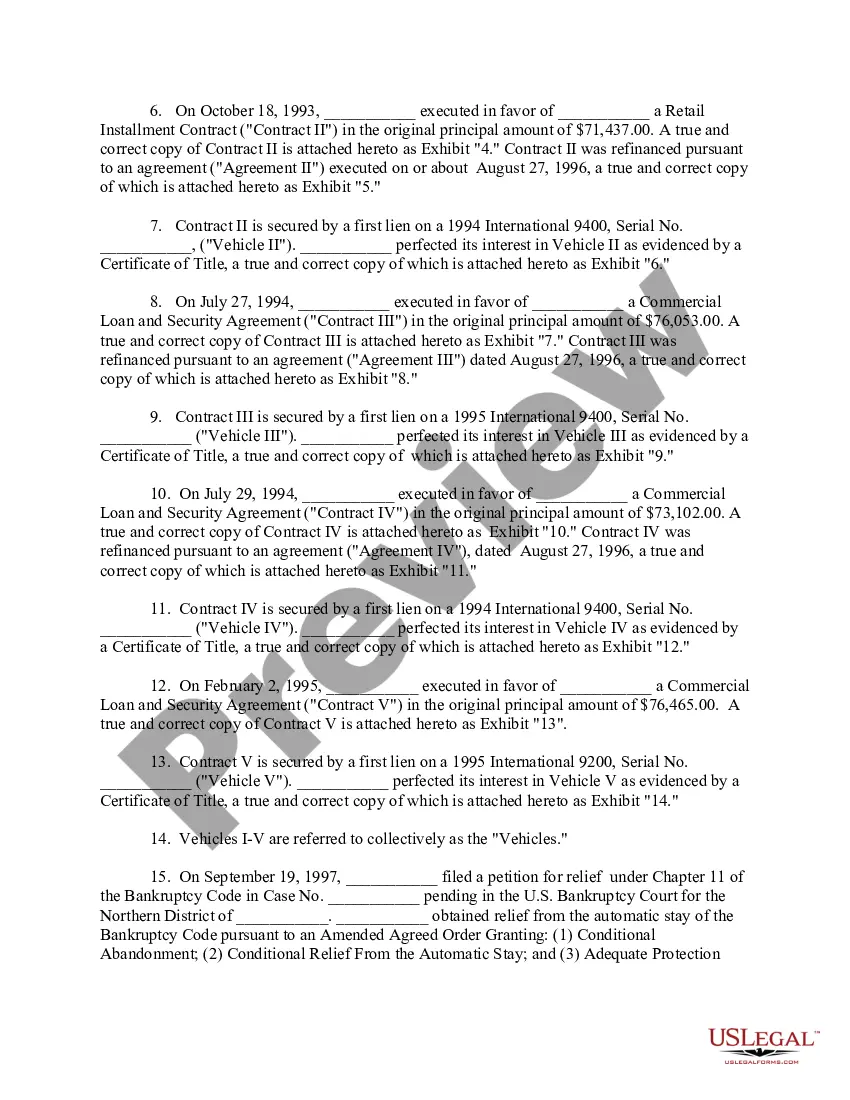
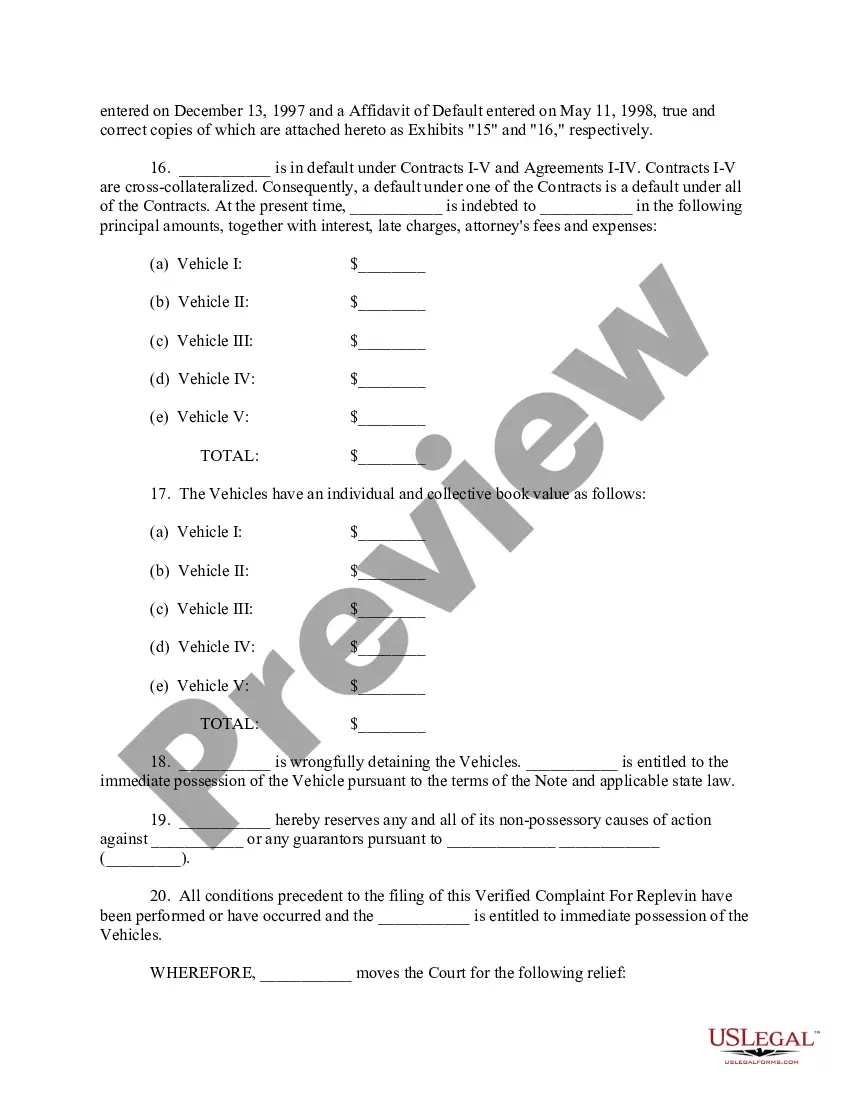
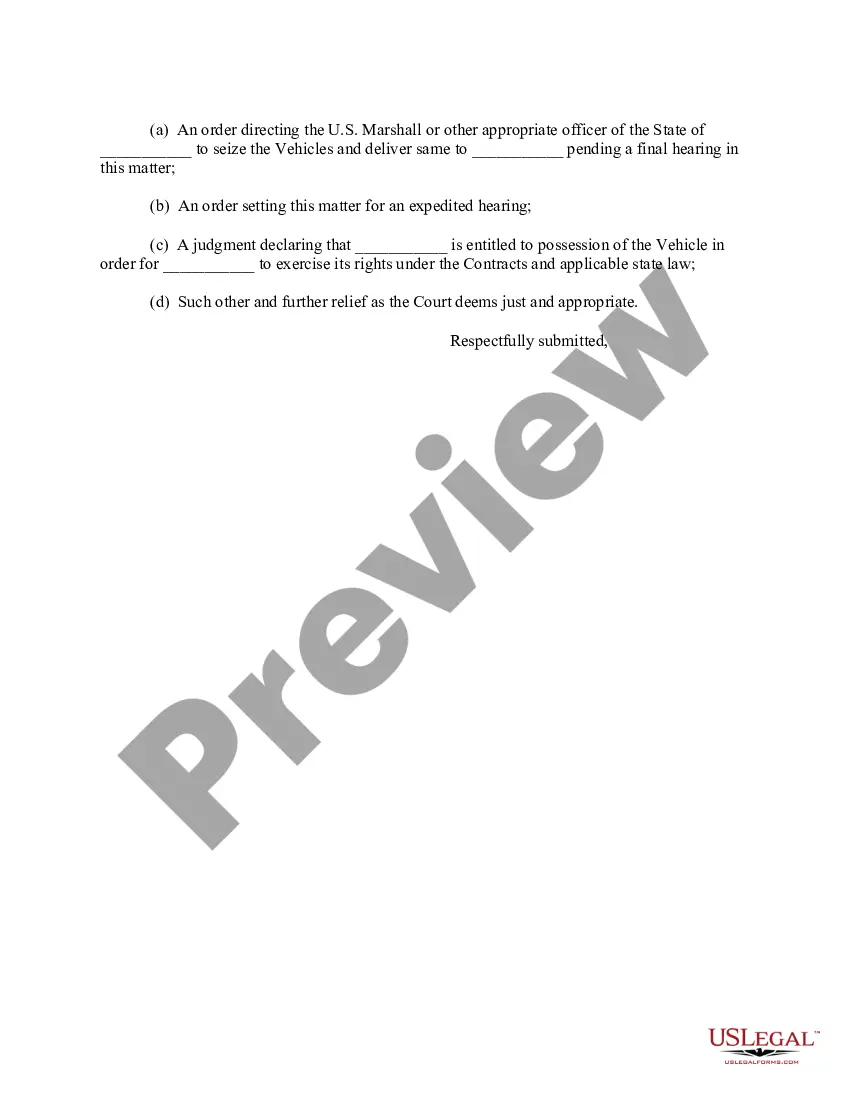
What Happens If the Repo Agent Doesn't Find Your Car? But if you make it hard for the repo agent to get it, then the creditor may use another method to get the car back, called "replevin." Replevin can be just as costly as a repossession, if not more so.
After the repossession, the lender must send you a written notice that tells you: The date and time the car will be sold at a public auction or the time after which a private sale will be made. About your right to know how the sale proceeds get applied. Whether you'll be liable for any unpaid balance after the sale.