Loan Agreement for Friends
About this form
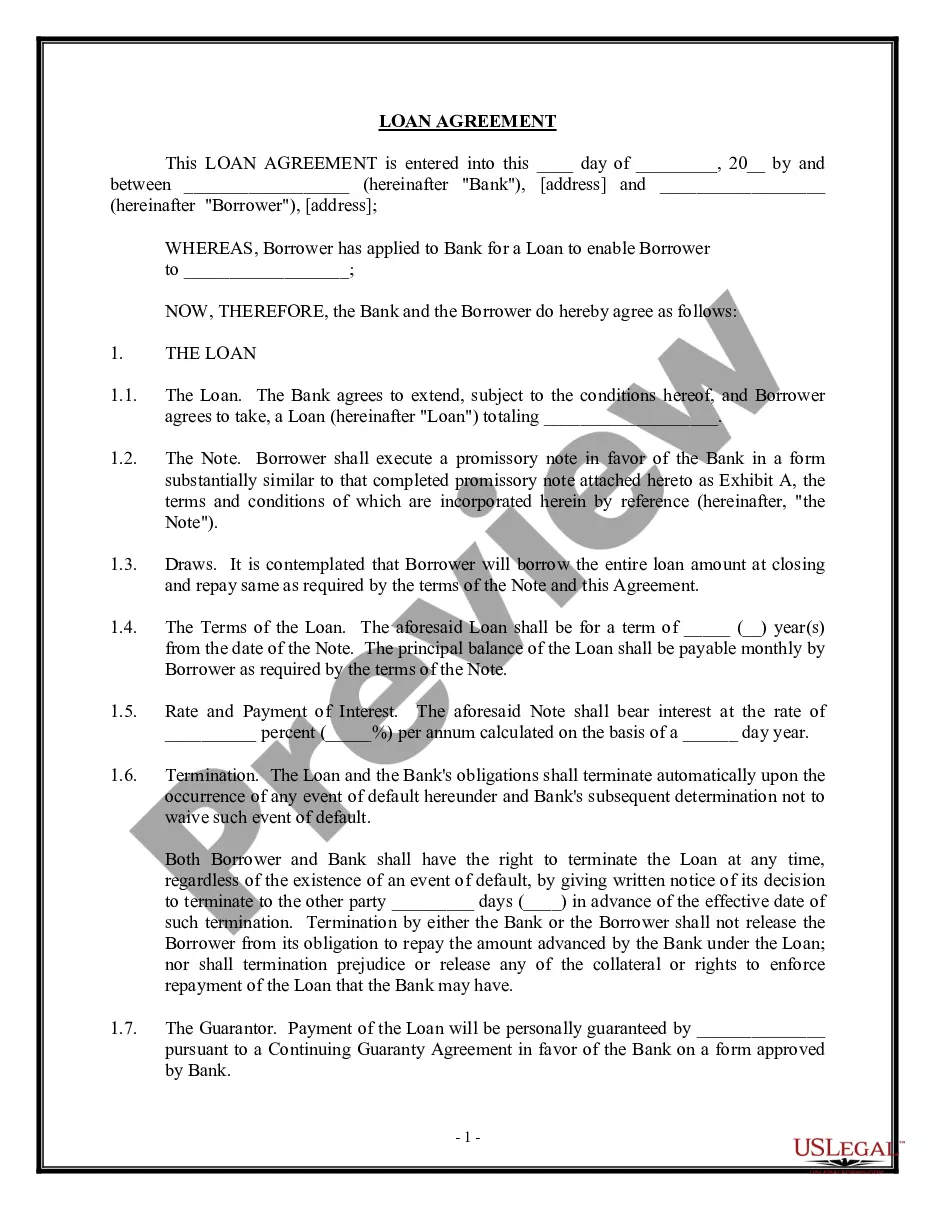
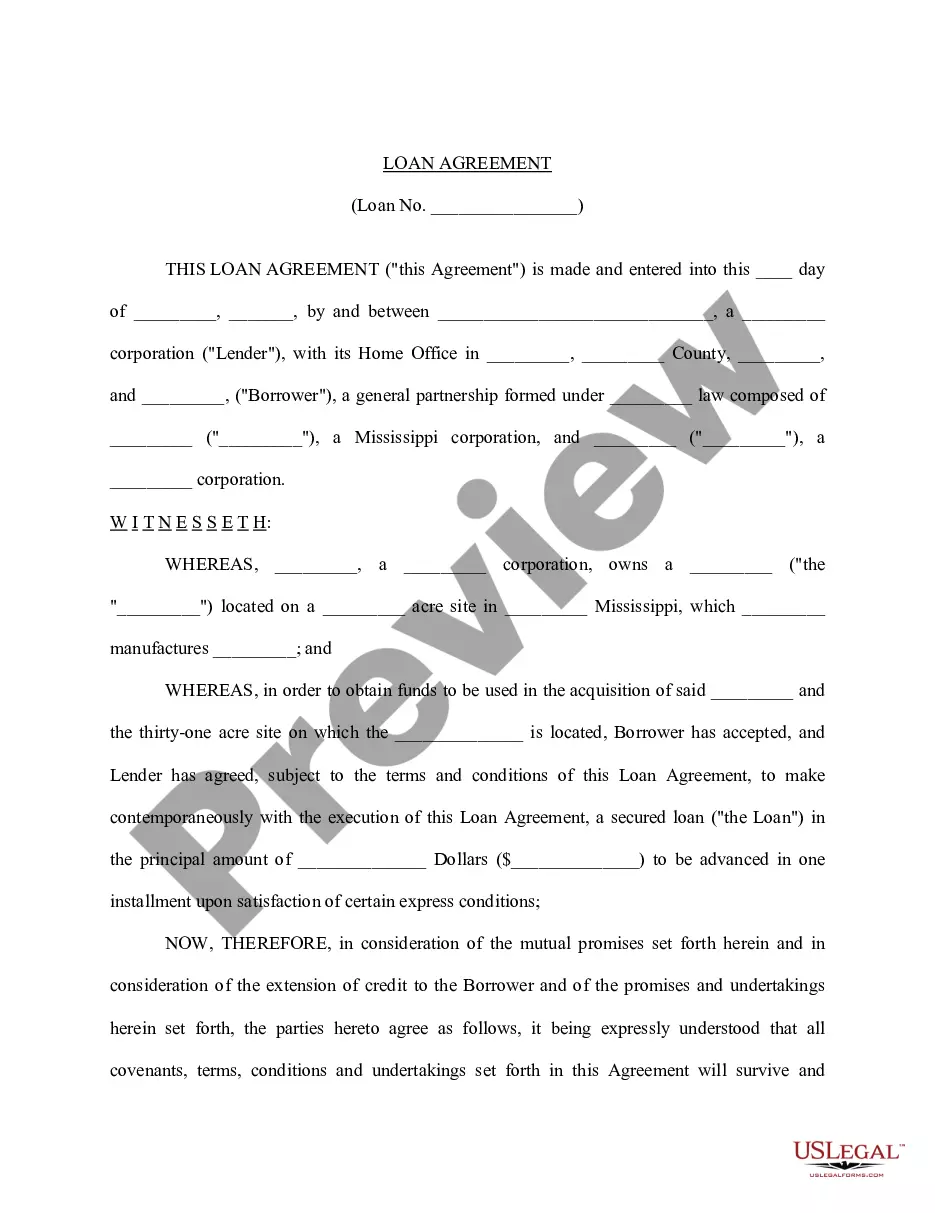
A Loan Agreement for Friends is a legal document that outlines the terms of a loan made between two parties, specifically friends. This form clearly defines the responsibilities, obligations, and liabilities of both the lender and the borrower, ensuring that both parties understand their rights in the arrangement. It is different from standard loan agreements as it focuses on informal lending among friends, establishing a clear record to prevent misunderstandings and protect relationships.
Form components explained
- Identification of the parties involved (Lender and Borrower)
- Description of the loan terms, including the amount and interest rate
- Repayment schedule and method of payment
- Events of default and remedies for failure to repay
- Signatures of all parties to validate the agreement
Situations where this form applies
This form should be used when a friend lends money to another friend and both parties wish to formalize the loan agreement. It is particularly useful to clearly outline loan terms to avoid potential conflicts or misunderstandings in the future. Whether for personal loans for expenses, buying items, or funding activities, this agreement helps ensure both parties are on the same page regarding repayment and conditions.
Intended users of this form
This form is intended for:
- Individuals lending money to friends
- Individuals borrowing money from friends
- Those who want to ensure clarity and accountability in personal loans
- Parties looking for a written agreement to formalize an informal loan
How to complete this form
- Identify the parties: Clearly state the names and addresses of the lender and borrower.
- Specify the loan amount: Fill in the exact amount being lent.
- Set the interest rate: Determine and include any applicable interest rate for the loan.
- Outline repayment terms: Include the repayment schedule and method agreed upon by both parties.
- Sign the agreement: Both parties should sign the document to acknowledge and agree to the terms.
Notarization requirements for this form
This form does not typically require notarization unless specified by local law. However, having a notary witness the signatures can add an extra layer of formality and may help prevent disputes in the future.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Typical mistakes to avoid
- Not clearly defining the repayment terms, leading to confusion later.
- Failing to specify penalties for late payments or defaults.
- Not having both parties sign the agreement, making it unenforceable.
- Leaving key details, such as interest rate or loan amount, blank.
Benefits of using this form online
- Convenience of accessing the form anytime and anywhere.
- Ability to customize the agreement based on personal circumstances.
- Quick download and print options for immediate use.
- Legal assurance that the form complies with standard requirements.
Summary of main points
- The Loan Agreement for Friends formalizes financial transactions between friends, helping to avoid misunderstandings.
- Key components include loan amounts, interest rates, repayment terms, and penalties for default.
- Always ensure all parties sign the document for it to be legally binding.
- Consider notarizing the document for better enforceability.
Looking for another form?
Form popularity
FAQ
Normally the loan is repaid, however occasionally the company may decide to write off (release) the loan, meaning the individual does not have to pay back the balance. If the loan is made to an employee (including a director), the amount of the loan released is treated as employment income.
Ask for help only when you really don't have any other option. Pay interest. Never negotiate. Create proper documentation regarding the loan. Don't get a third party involved. Try to pay the loan ASAP. Return the favour when needed.
Generally, to deduct a bad debt, you must have previously included the amount in your income or loaned out your cash.If you lend money to a relative or friend with the understanding the relative or friend may not repay it, you must consider it as a gift and not as a loan, and you may not deduct it as a bad debt.
State the purpose for the loan. #Set forth the amount and terms of the loan. Your agreement should clearly state the amount of money you're lending your friend, the interest rate, and the total amount your friend will pay you back.
The addresses and contact information of all parties involved. The conditions of use of the loan (what the money can be used for) Any repayment options. The payment schedule. The interest rates. The length of the term. Any collateral. The cancellation policy.
This is true whether a bank, credit union, peer-to-peer lender or another financial institution lent you the money. If you receive a personal loan from a friend or family member, there may be other tax implications, but the money still won't be taxable income for you.
Though personal loans are not tax deductible, other types of loans are. Interest paid on mortgages, student loans, and business loans often can be deducted on your annual taxes, effectively reducing your taxable income for the year.
Put It in Writing An agreement can be as simple as a piece of paper stating how much you're borrowing, for what reasons, and how and when you will pay your friend back. Include both your names, the date and signatures.
Gifts from family members are not taxable, neither are the loans. But any gift above Rs 50,000 from a friend (non-relative or anyone who falls outside the definition of 'family' under the Income Tax Act) during a financial year is taxable. However, if it's a loan (with or without interest), it becomes tax-free.