Letter Informing Debt Collector of False or Misleading Misrepresentations in Collection Activities - False Representation or Implication that the Debt Collector is an Attorney or that Communication is From an Attorney
What is this form?
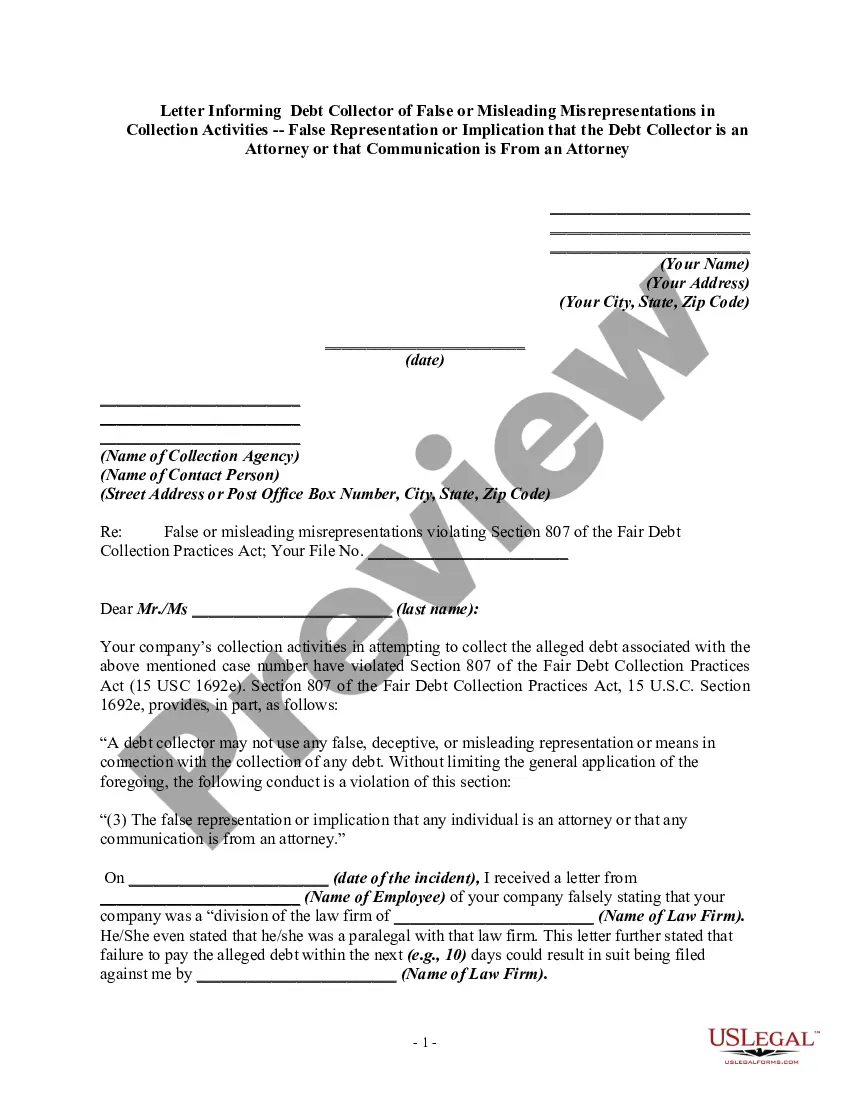
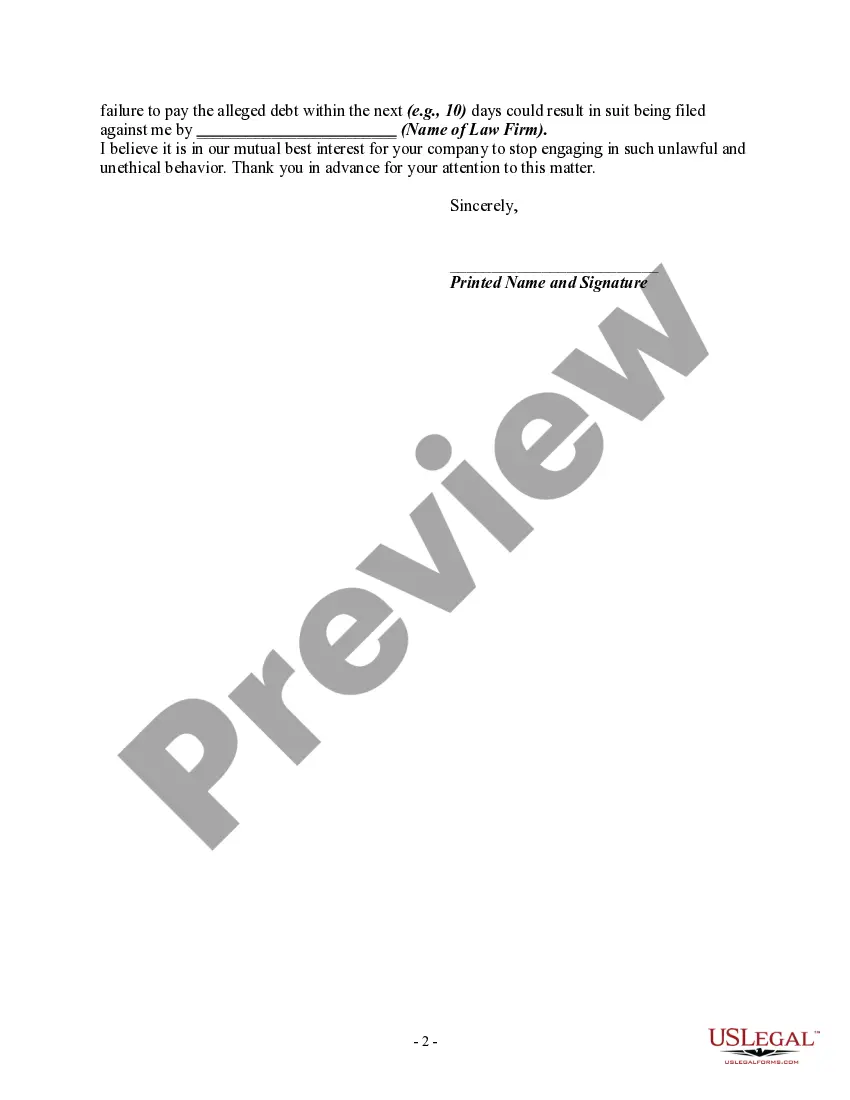
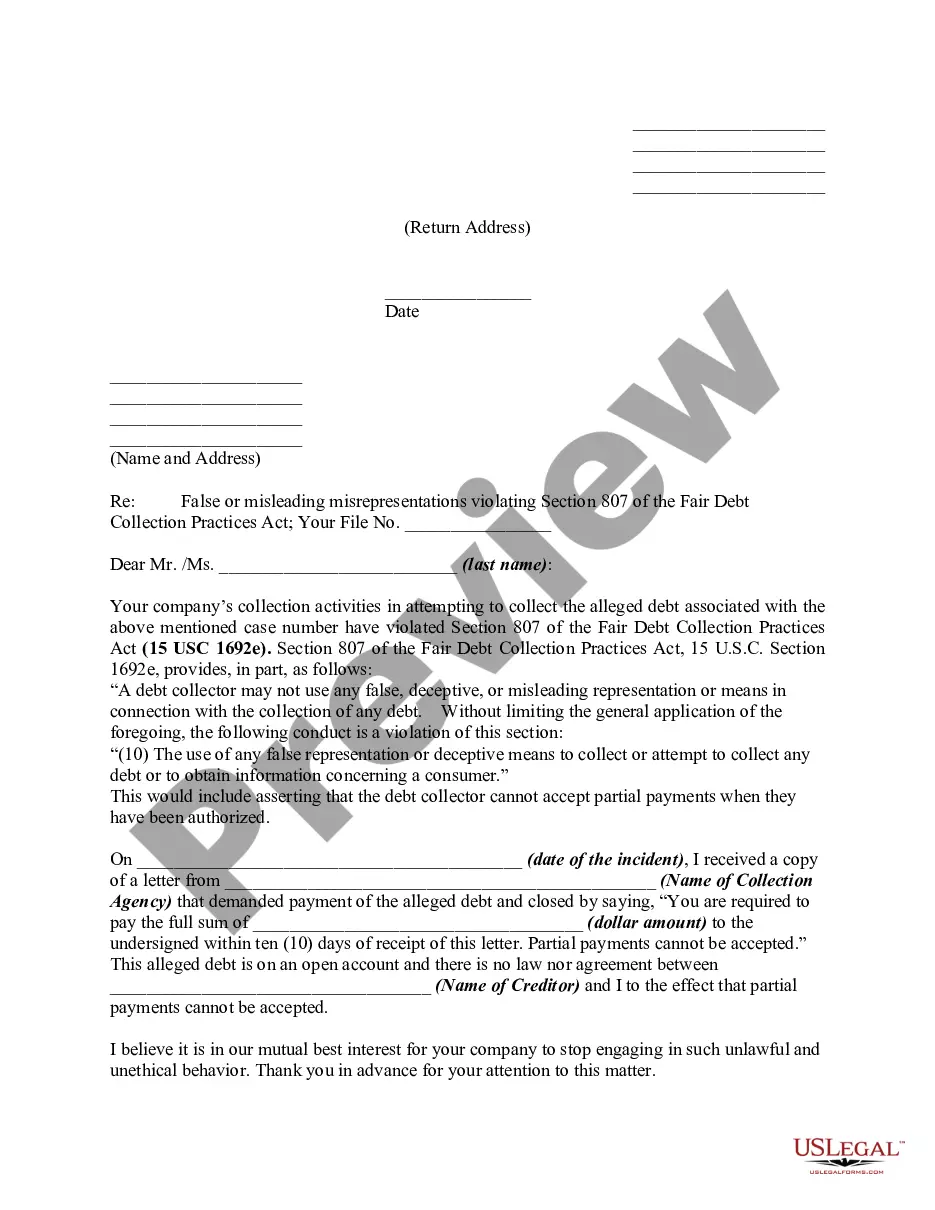
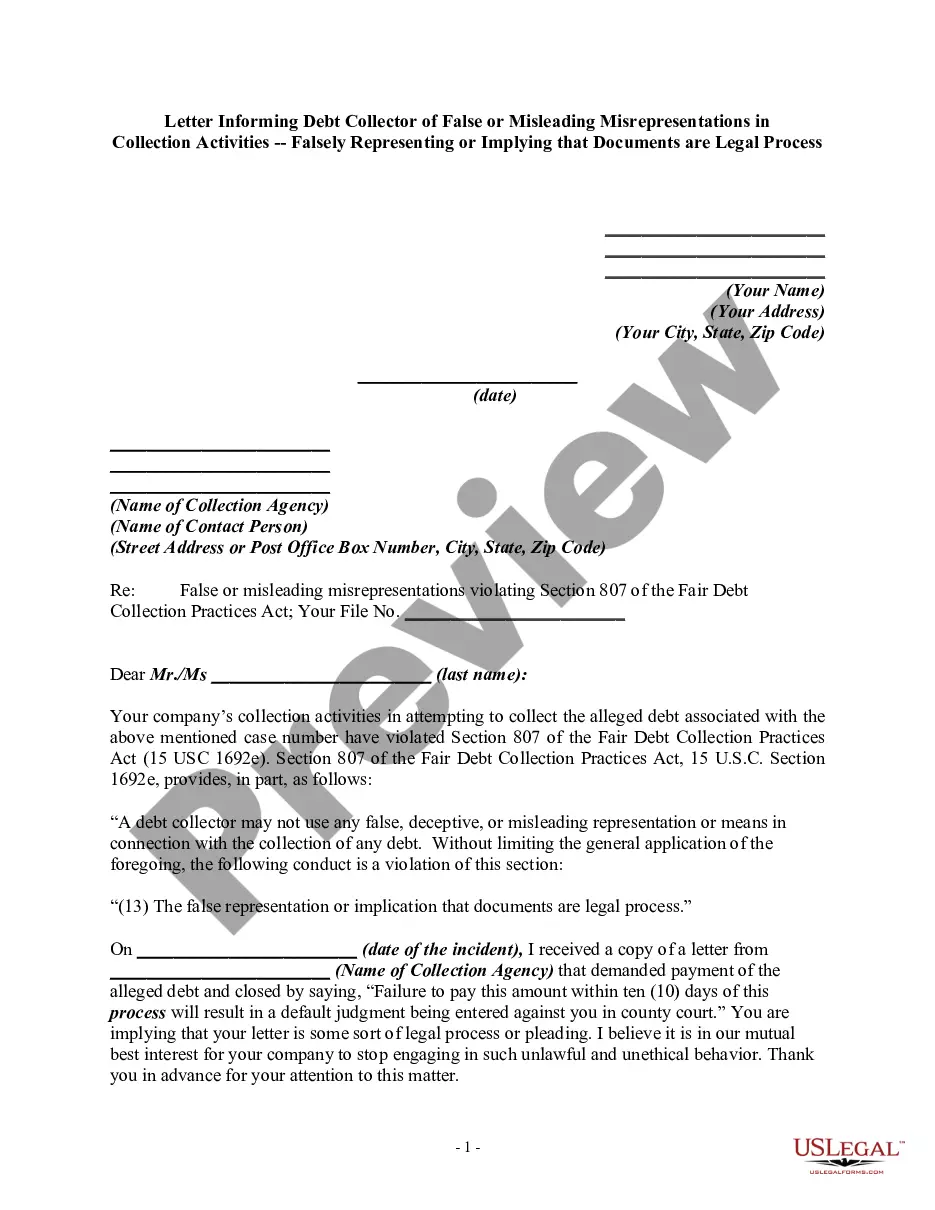
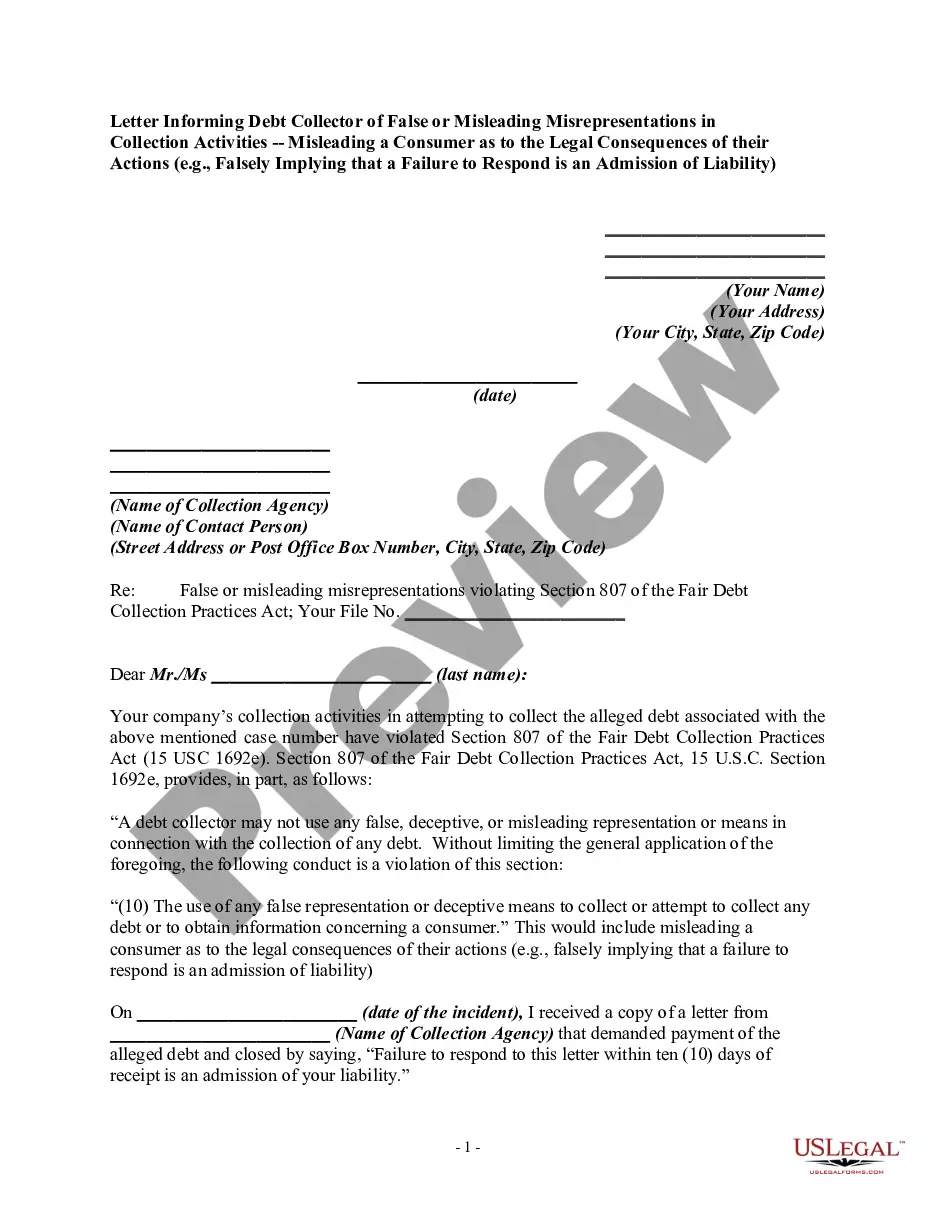
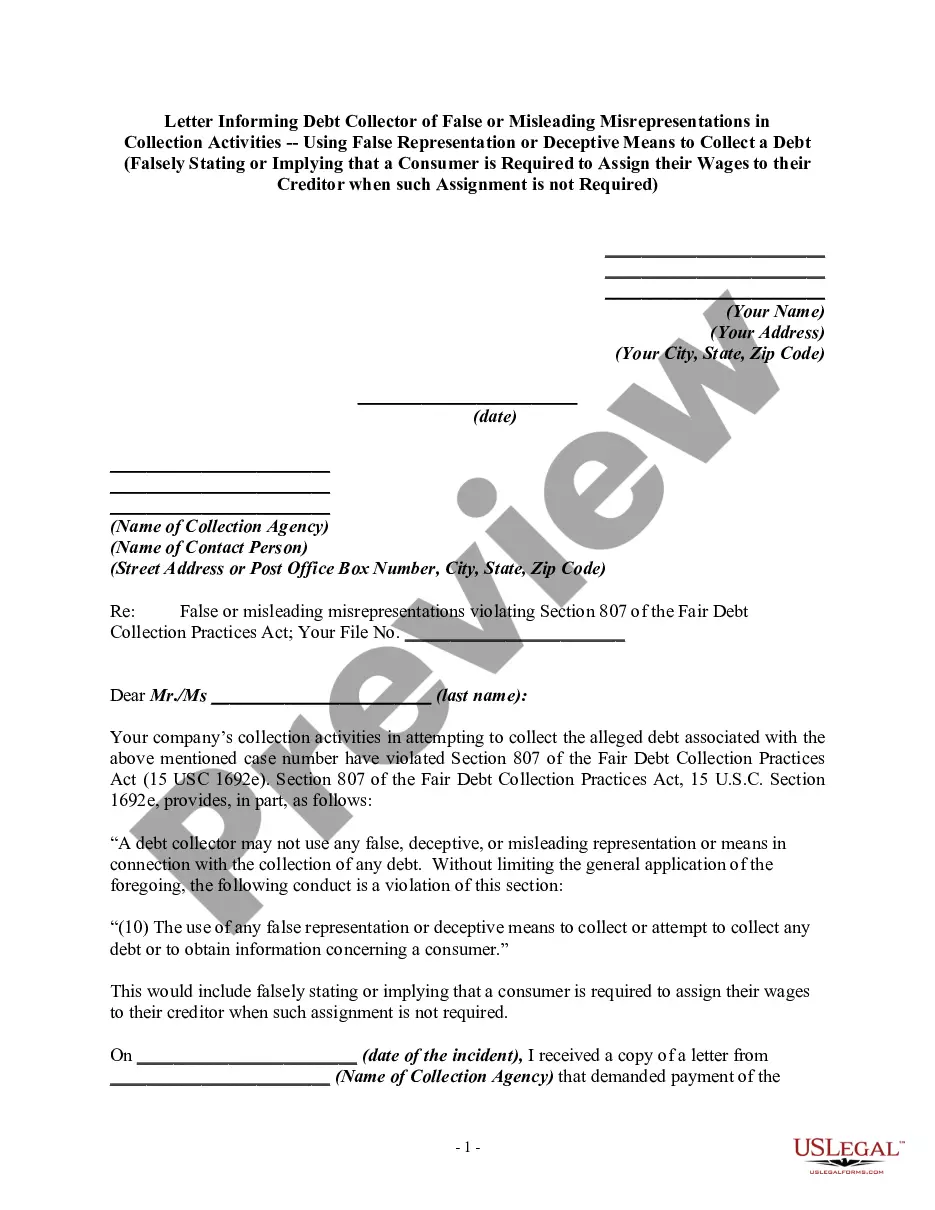
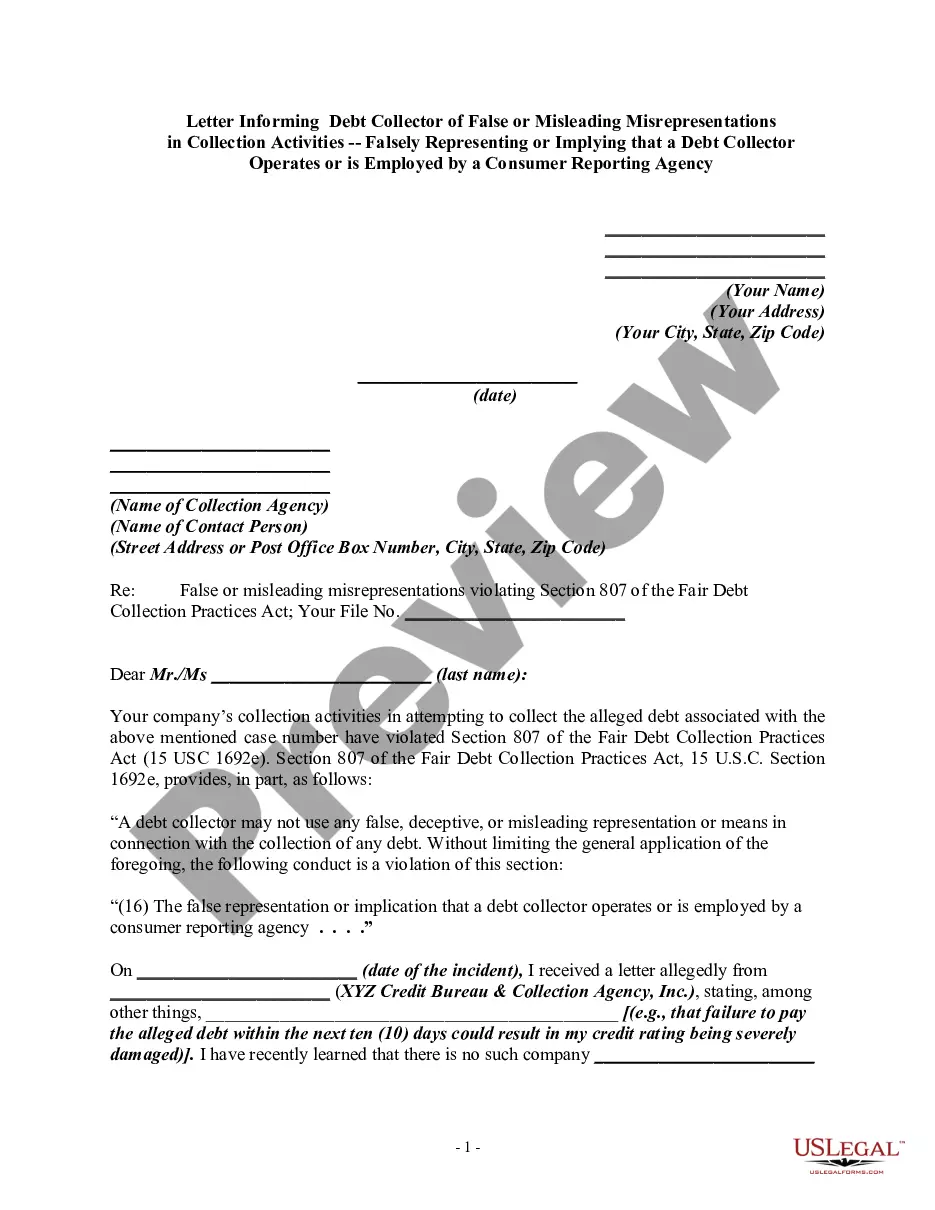
This form is a letter informing a debt collector of false or misleading misrepresentations in their collection activities. Specifically, it addresses violations of the Fair Debt Collection Practices Act (FDCPA), particularly the false implication that the debt collector or their communication is from an attorney. This form serves as a formal notification to the collection agency regarding their unlawful actions and seeks to halt such practices.
Key parts of this document
- Your name and address
- Date of the letter
- Name and address of the collection agency
- Details of the alleged debt and any associated file number
- Description of the misleading communications received
- Your printed name and signature
Situations where this form applies
You should use this form if you have received a communication from a debt collector that falsely represents them or implies that they are associated with an attorney. This letter helps to formally address and document the misleading behavior, asserting your rights under the FDCPA.
Who this form is for
- Consumers who are contacted by debt collectors
- Individuals who believe they have been subjected to misleading or false representations regarding their debt
- Anyone who wishes to assert their rights under the Fair Debt Collection Practices Act
How to complete this form
- Identify yourself by entering your name and address at the top of the letter.
- Input the date you are sending the letter.
- Fill in the name and address of the collection agency.
- State the details of the misleading communication you received, including dates and names where possible.
- Sign the letter and print your name below the signature.
Does this document require notarization?
This form does not typically require notarization unless specified by local law.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Avoid these common issues
- Failing to include all relevant details about the misleading communication.
- Not signing the letter or omitting your printed name.
- Using informal language instead of a professional tone.
Benefits of using this form online
- Convenient access to a legally sound template tailored to address your needs.
- Edit and customize the form easily to suit your specific circumstances.
- Reliable guidance from language drafted by licensed attorneys.
Looking for another form?
Form popularity
FAQ
Debt collectors cannot harass or abuse you. They cannot swear, threaten to illegally harm you or your property, threaten you with illegal actions, or falsely threaten you with actions they do not intend to take. They also cannot make repeated calls over a short period to annoy or harass you.
Unfair practices are prohibited Deposit or threaten to deposit a postdated check before your intended payment date. Take or threaten to take property if it's not allowed. Collect more than you owe on a debt, which may include fees and interest.
Within 30 days of receiving the written notice of debt, send a written dispute to the debt collection agency. You can use this sample dispute letter (PDF) as a model. Once you dispute the debt, the debt collector must stop all debt collection activities until it sends you verification of the debt.
You have the right to sue the collection agency if they act improperly for one year from the improper action. You can sue for lost wages and other expenses incurred, including legal and court costs. Also, the judge is allowed to award you up to $1,000 in punitive damages.
No. Debt collectors are prohibited from deceiving or misleading you while trying to collect a debt. Debt collectors are generally prohibited under federal law from using any false, deceptive, or misleading misrepresentation in collecting a debt.
The debt dispute letter should include your personal identifying information; verification of the amount of debt owed; the name of the creditor for the debt; and a request that the debt not be reported to credit reporting agencies until the matter is resolved or have it removed from the report, if it already has been
Debt validation is your federal right granted under the Fair Debt Collection Practices Act (FDCPA). To request debt validation, you must send a written request to the debt collector within 30 days of being contacted by the collection agency.
The name 623 dispute method refers to section 623 of the Fair Credit Reporting Act (FCRA). The method allows you to dispute a debt directly with the creditor in question as long as you have already filed your complaint with the credit bureau and completed their process.
If you pay the collection agency directly, the debt is removed from your credit report in six years from the date of payment. If you don't pay, it purges six years from the last activity date, but you may be at risk for wage garnishment.