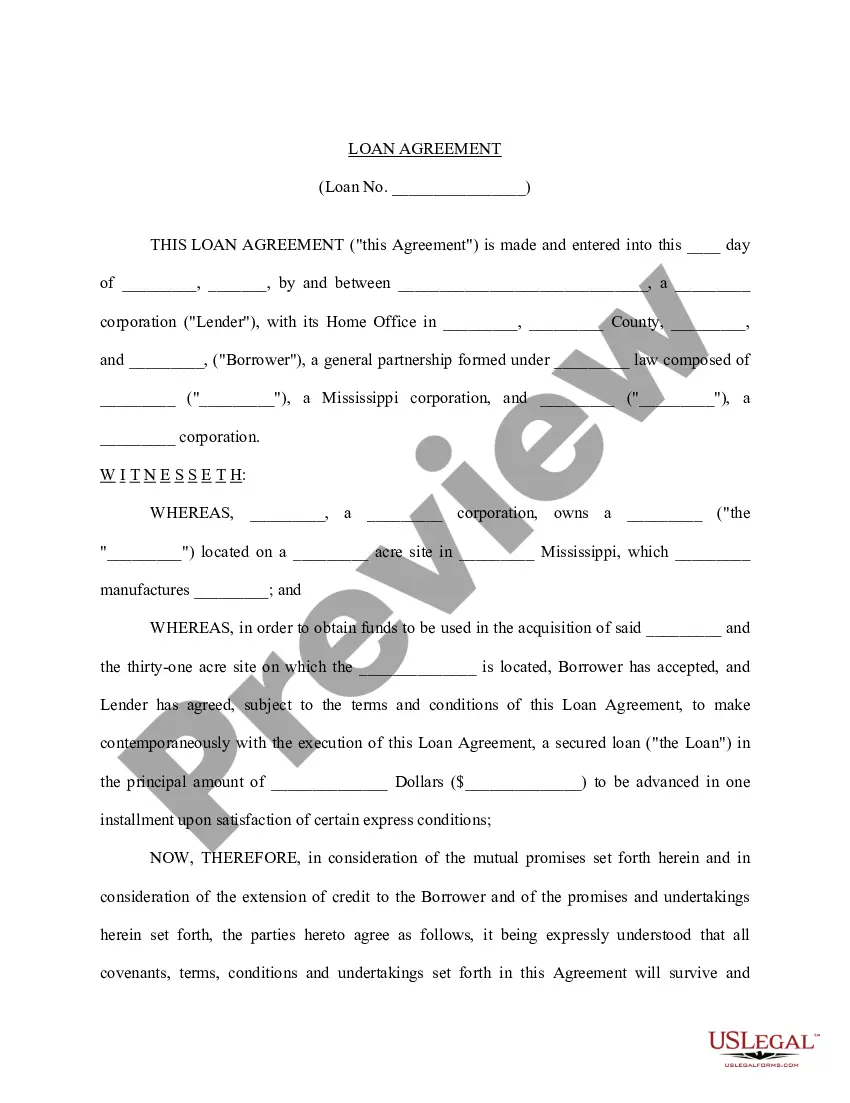
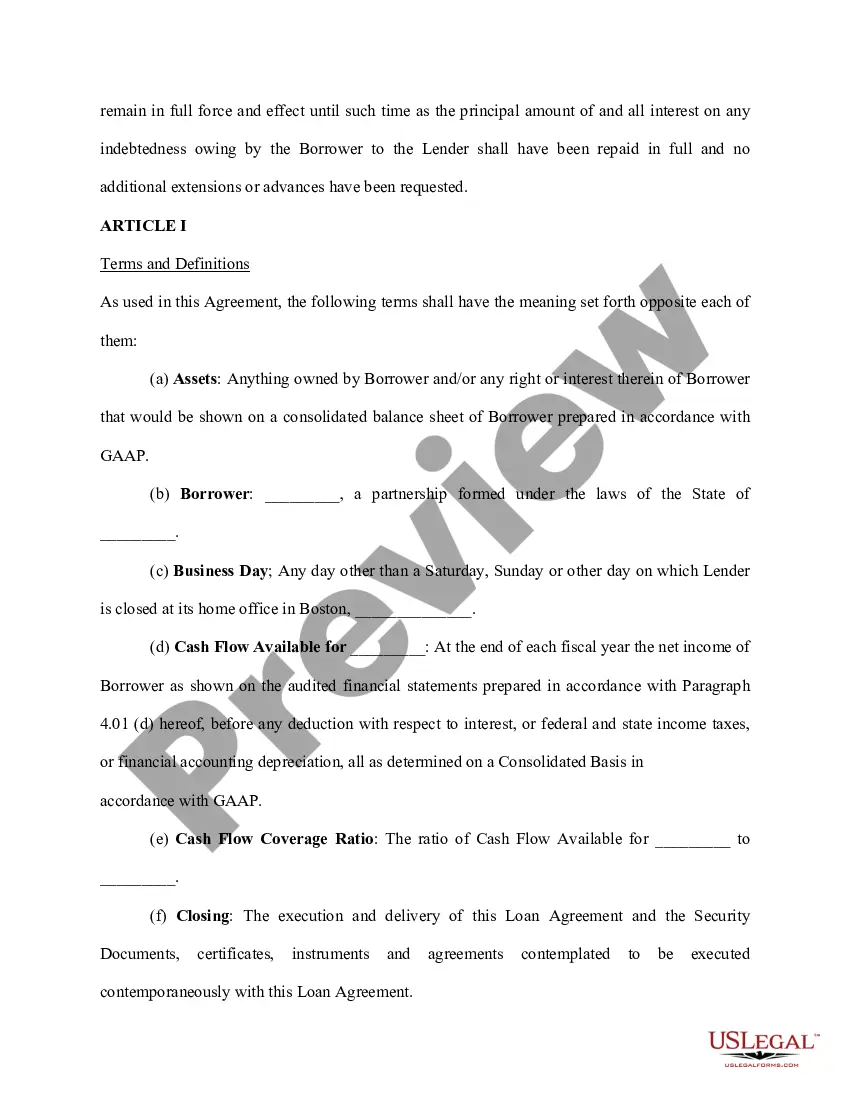
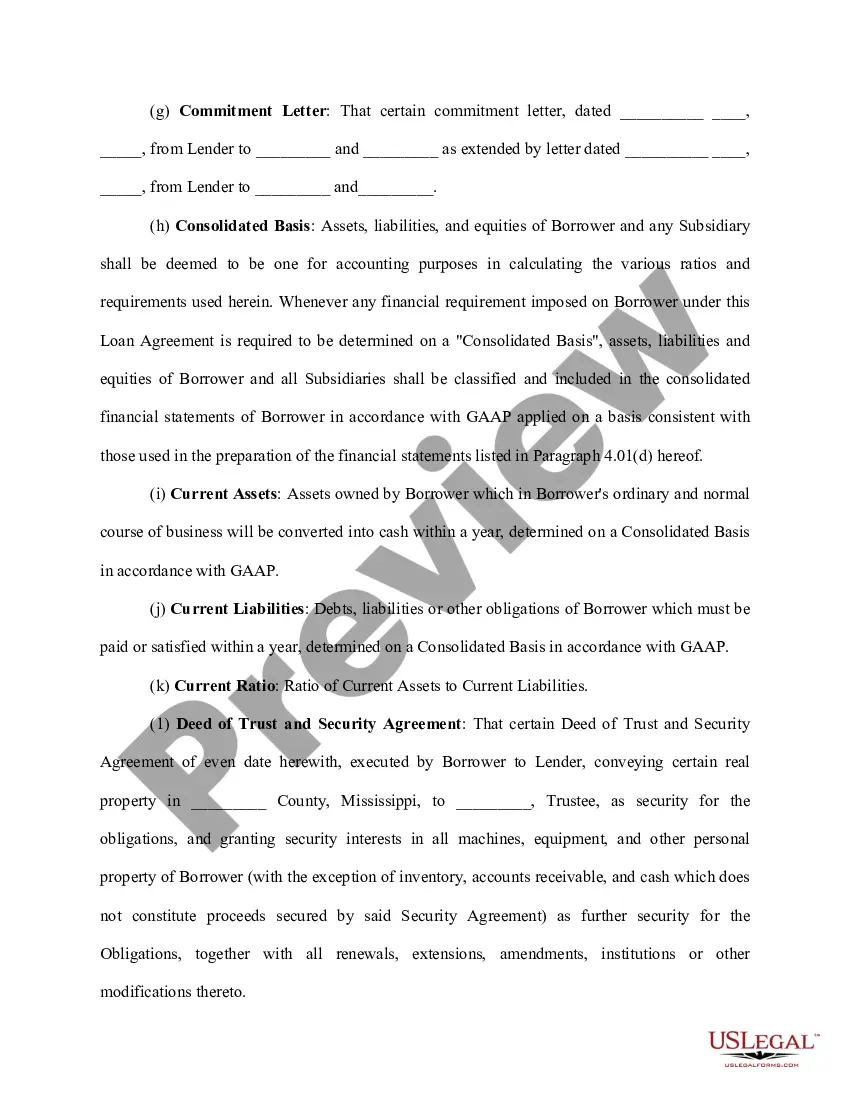
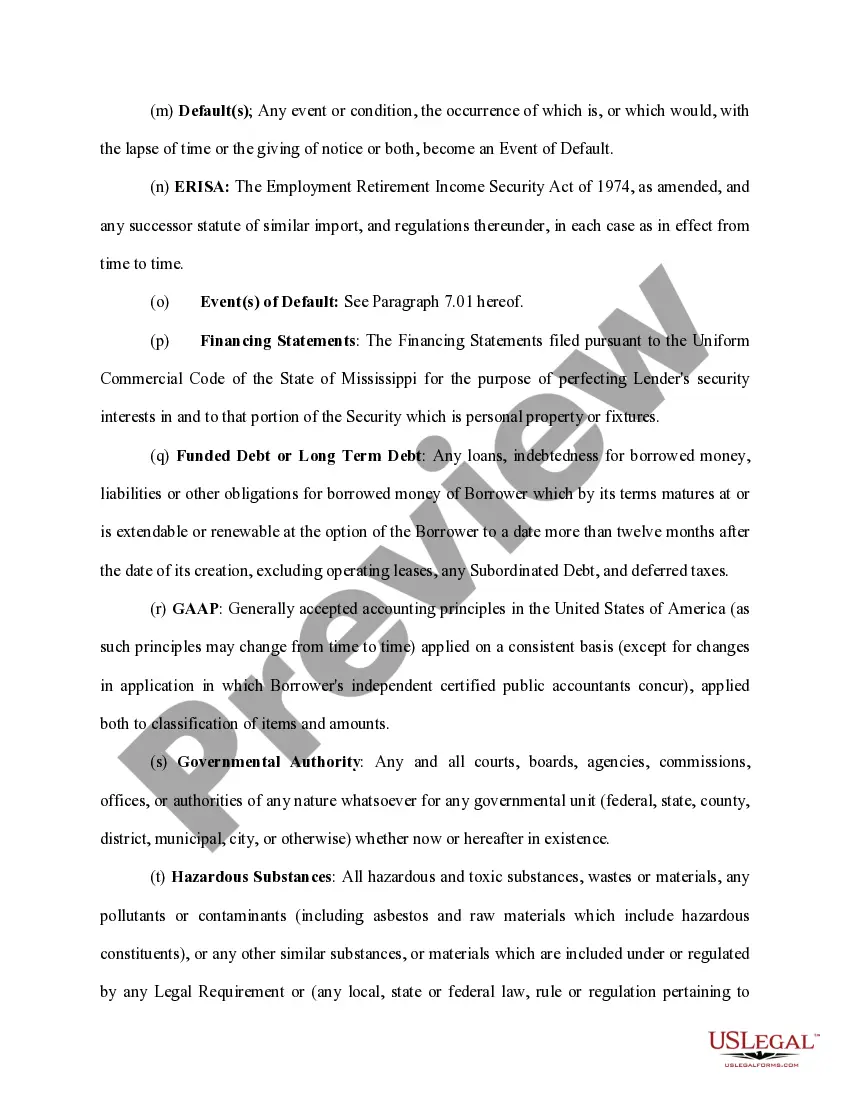
Los Angeles California Loan Agreement for Car
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

How to fill out Loan Agreement For Car?
A document process consistently accompanies any legal activity you undertake.
Establishing a business, applying for or accepting a job offer, transferring ownership, and numerous other life situations require you to prepare official paperwork that varies from state to state.
This is why having everything consolidated in one location is incredibly advantageous.
US Legal Forms is the largest online repository of up-to-date federal and state-specific legal documents.
This is the simplest and most trustworthy method to acquire legal documents. All the templates available in our library are professionally crafted and verified for compliance with local laws and regulations. Prepare your documentation and manage your legal matters efficiently with US Legal Forms!
- On this platform, you can effortlessly locate and download a document for any personal or business purpose utilized in your area, including the Los Angeles Loan Agreement for Car.
- Finding templates on the platform is exceptionally easy.
- If you already have a subscription to our service, Log In to your account, search for the sample using the search bar, and click Download to save it on your device.
- Afterward, the Los Angeles Loan Agreement for Car will be available for further use in the My documents section of your profile.
- If you are interacting with US Legal Forms for the first time, adhere to this brief guide to acquire the Los Angeles Loan Agreement for Car.
- Ensure you have accessed the correct page with your local form.
- Utilize the Preview mode (if available) and browse through the sample.
- Read the description (if any) to confirm the form satisfies your requirements.
- Search for another document using the search tab if the sample does not suit you.
- Click Buy Now when you find the necessary template.
- Choose the suitable subscription plan, then sign in or create an account.
- Select the preferred payment method (with credit card or PayPal) to advance.
- Choose the file format and save the Los Angeles Loan Agreement for Car on your device.
- Utilize it as required: print it or fill it out electronically, sign it, and send it where requested.
Form popularity
FAQ
What is a car loan contract? A car loan contract is the agreement that you sign with a lender that sets out the arrangements dictating how much they lend you, the fees charged for the loan of the money, and how you will repay the car loan.
The 20/4/10 rule of thumb for car buying helps you shop for a vehicle that will fit your budget. The rule is to make a 20% down payment on a four-year car loan and spend no more than 10% of your monthly income on transportation expenses.
Loan agreements typically include covenants, value of collateral involved, guarantees, interest rate terms and the duration over which it must be repaid. Default terms should be clearly detailed to avoid confusion or potential legal court action.
A loan agreement is a contractual agreement between two parties whereby one party (lender) agrees to provide a loan to the other party (borrower) There are two types of loans; secured loans and unsecured loans.
Loan agreements are beneficial for borrowers and lenders for many reasons. Namely, this legally binding agreement protects both of their interests if one party fails to honor the agreement. Aside from that, a loan agreement helps a lender because it: Legally enforces a borrower's promise to pay back the money owed.
The signed loan contract is proof that the borrower and the lender have a commitment that funds will be used for a specified purpose, how the loan will be paid back and at what amortization rate. If the money is not used for the specified purpose, it should be paid back to the lender immediately.
A transaction whereby property is lent or given to another on condition of return or, where the loan is of money, repayment. During the period of the loan the borrower is entitled to use the thing loaned for the purpose agreed between the parties.
For a personal loan agreement to be enforceable, it must be documented in writing and signed by both parties. You may choose to keep a copy in your county recorder's office if you wish, though it's not legally necessary. It's sufficient for both parties to store their own copy, ideally in a safe place.
A personal loan contract is a legally binding document regardless of whether the lender is a financial institution or another person. The consequences are the same if you default on the contract. As a borrower, you could be sued by the lender or lose the asset or assets used to secure the loan.
You must notify your lender in writing that you are cancelling the loan contract and exercising your right to rescind. You may use the form provided to you by your lender or a letter. You can't rescind just by calling or visiting the lender.