Life Insurance Trust With For Mortgage
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
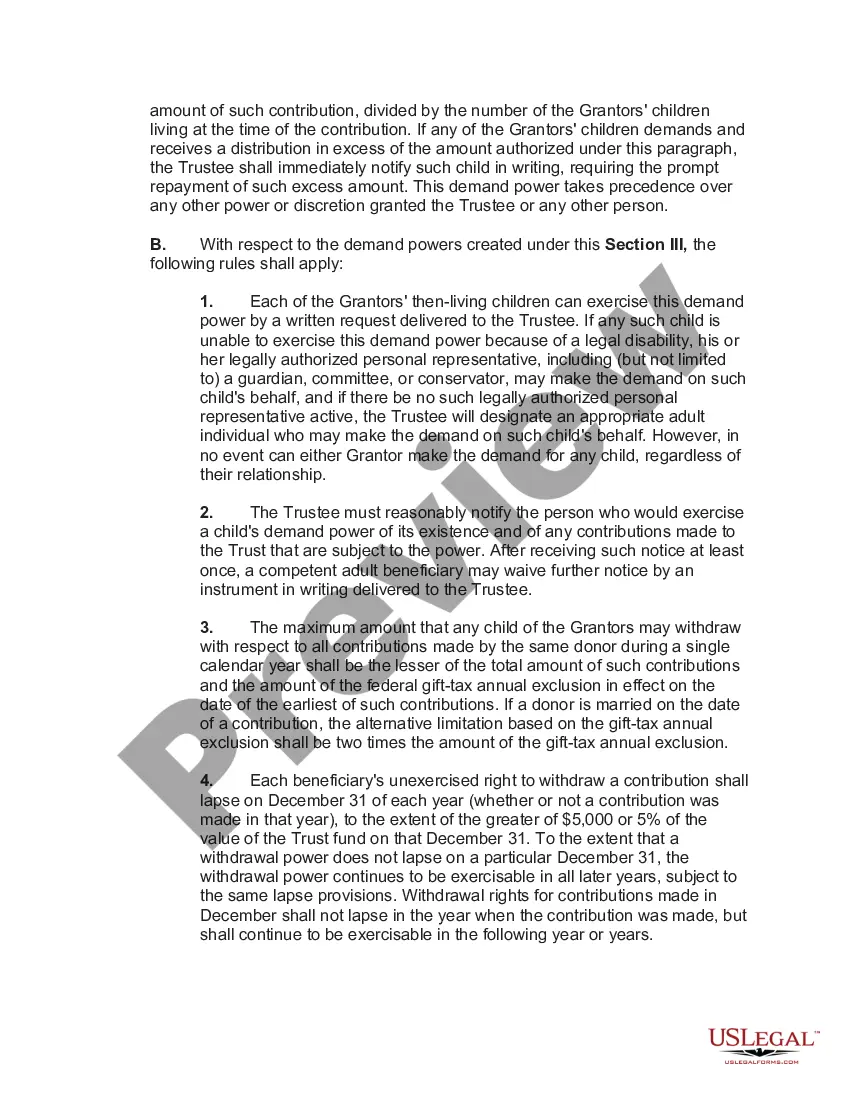
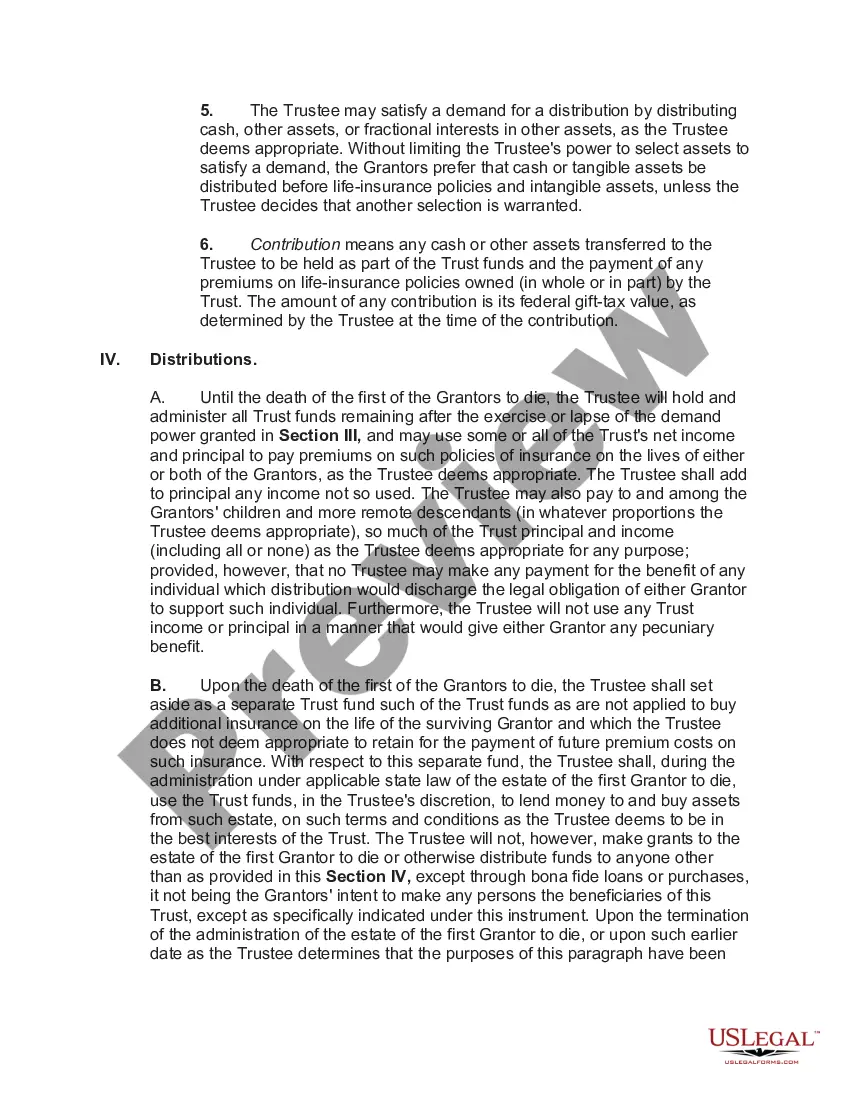
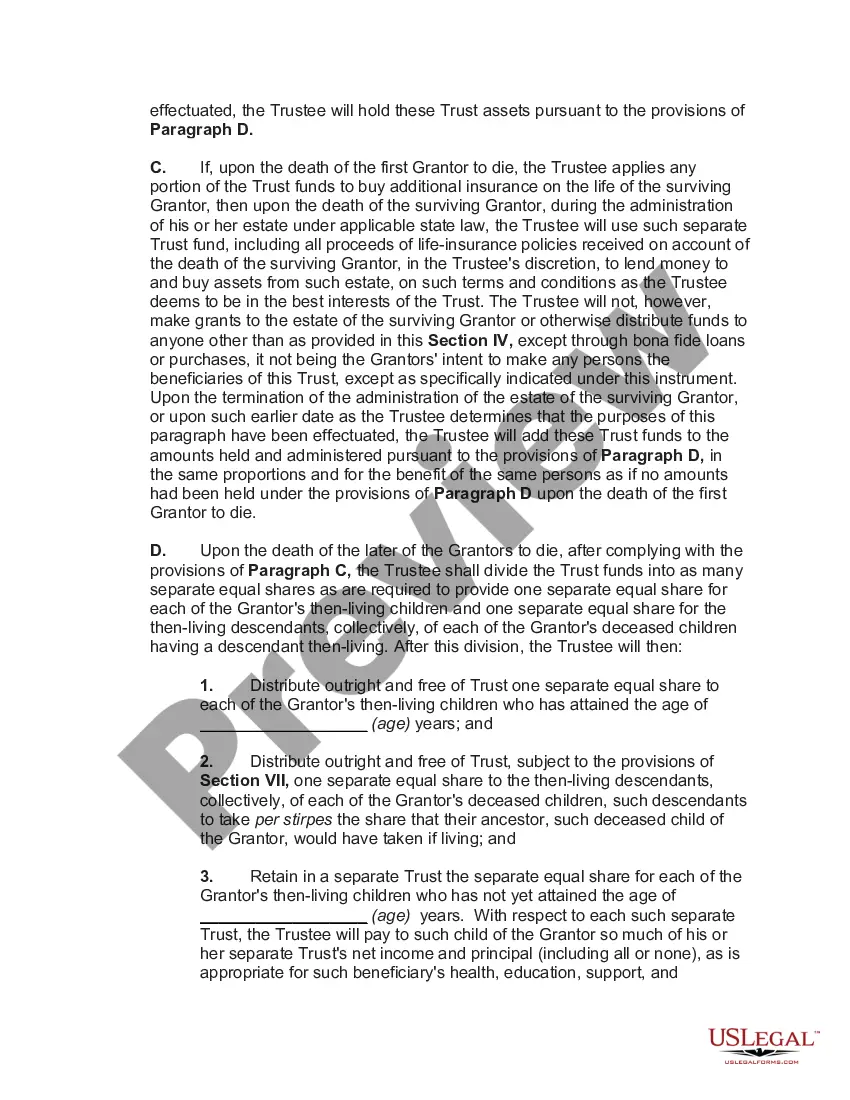
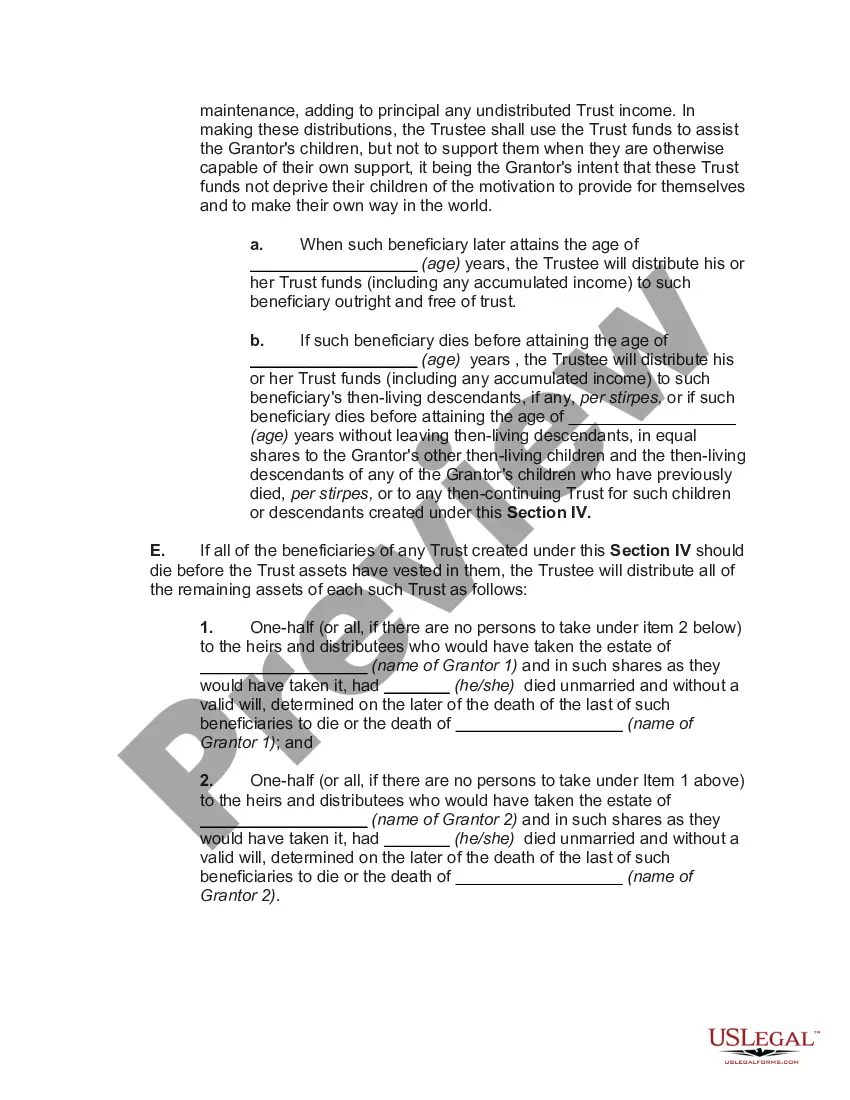
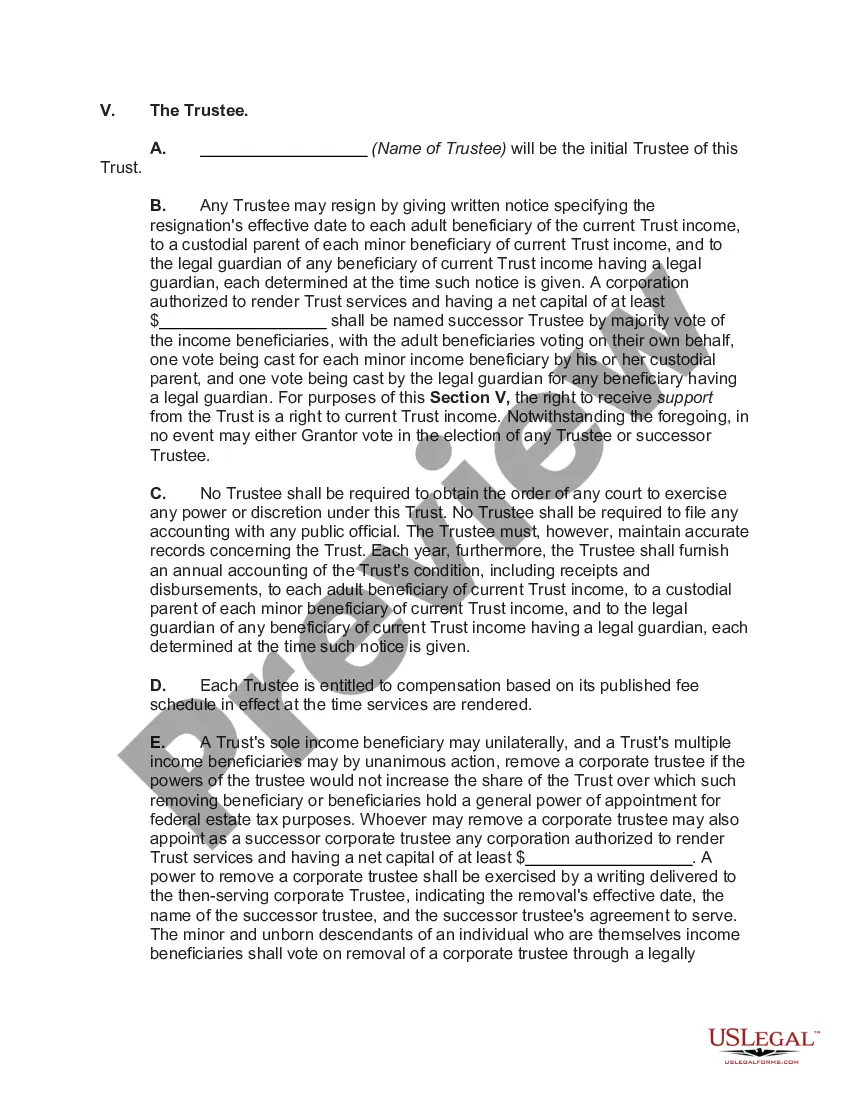
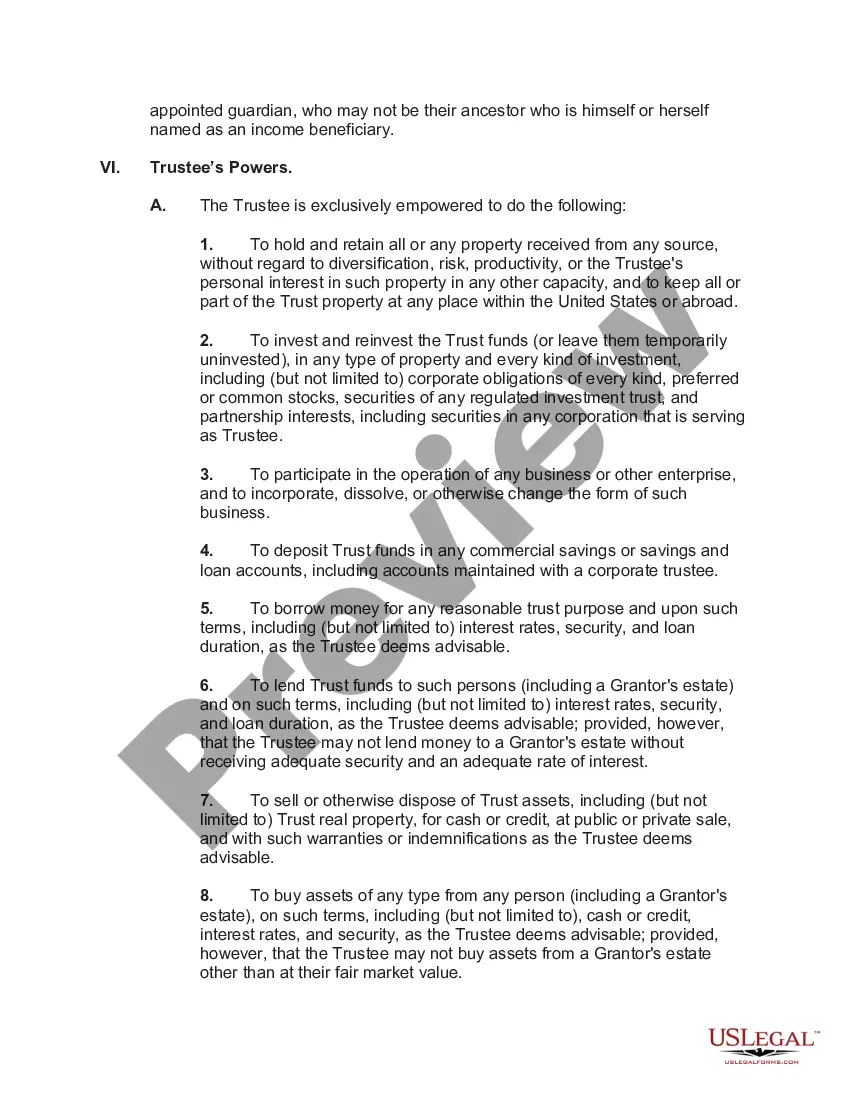
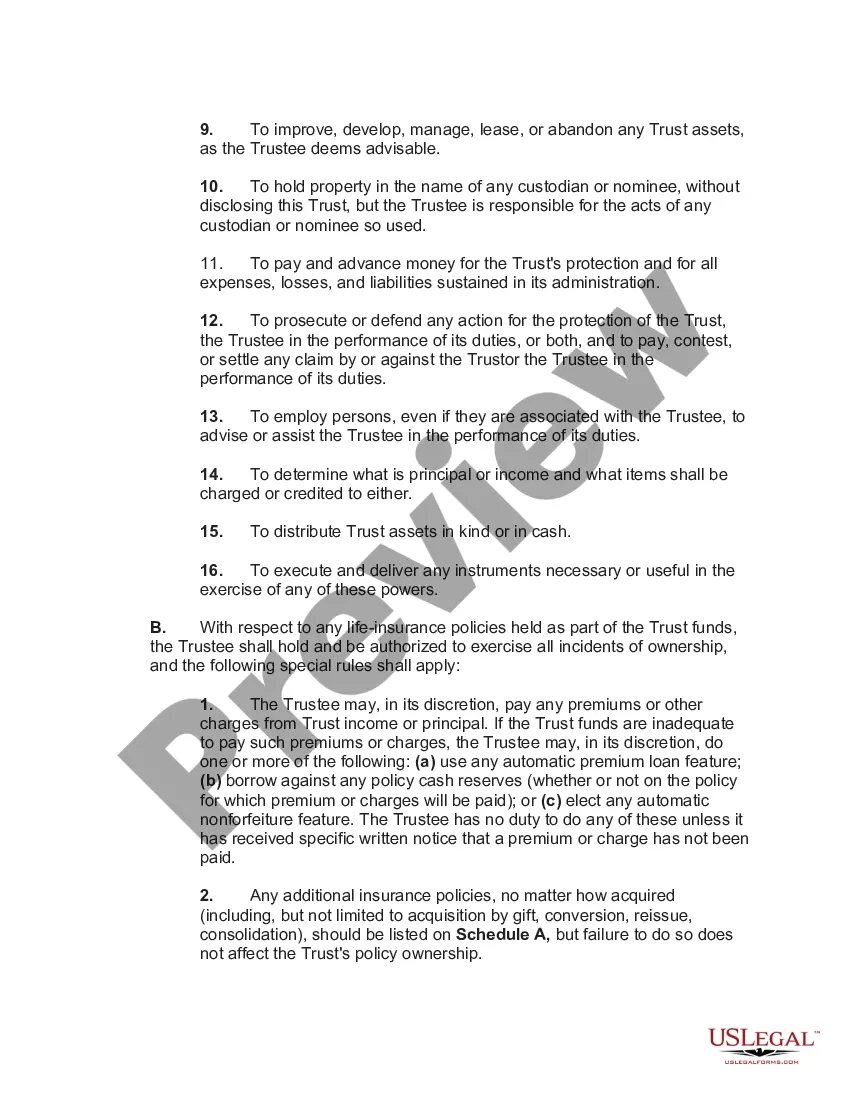
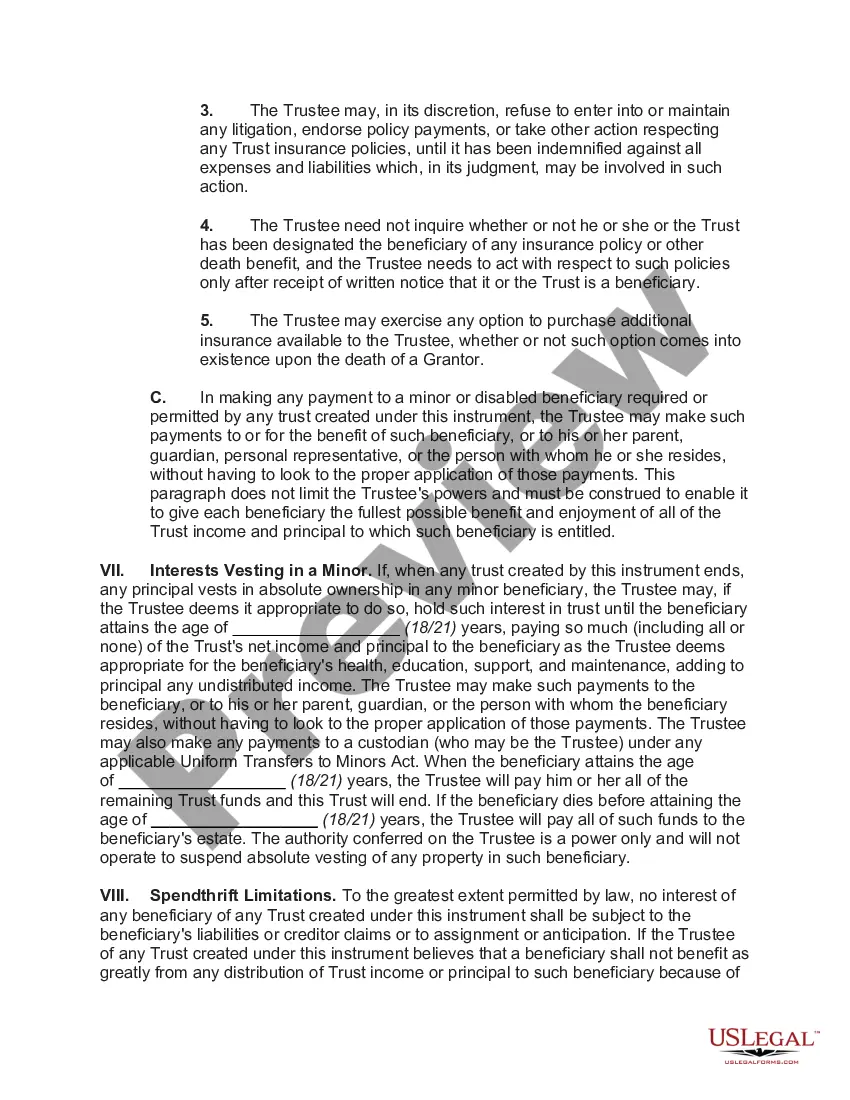
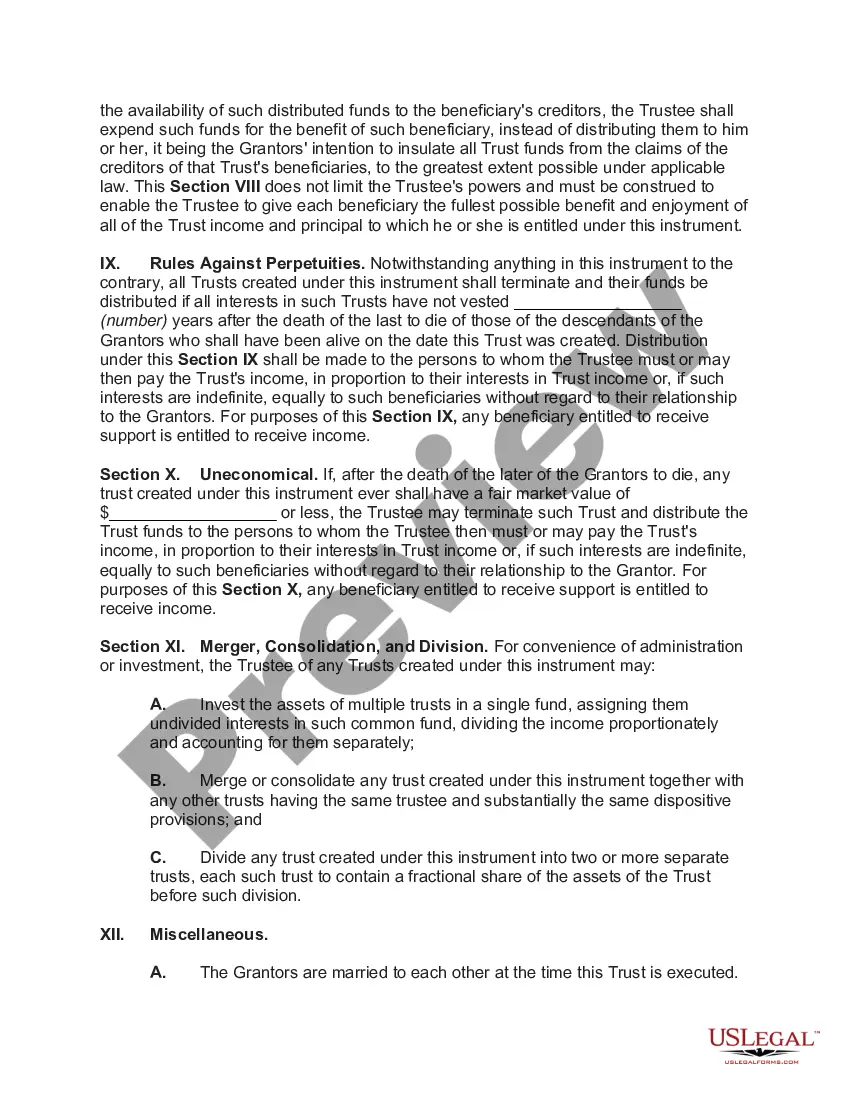
Life insurance trusts can be quite valuable, especially when considering tax implications and asset protection. They allow you to control how your insurance proceeds are distributed after your passing, which can help beneficiaries manage any debts or mortgages. Therefore, using a life insurance trust with for mortgage is often a strategic choice to ensure financial stability for your loved ones.
One of the biggest mistakes parents make when setting up a trust fund is failing to clearly define the terms and conditions. Without detailed guidelines on how the funds should be used, beneficiaries may misuse the trust. When establishing a life insurance trust with for mortgage, clarity ensures that the funds serve their intended purpose, providing financial security for your loved ones.
The 3-year rule for life insurance trusts indicates that if you transfer a life insurance policy into a trust, you must survive the transfer by at least three years for the trust to avoid estate taxes. If you pass away within three years, the policy may still be included in your taxable estate. This rule is vital when you're considering a life insurance trust with for mortgage needs, as it can impact the overall estate planning strategy.
The 3-year inclusion rule stipulates that for tax purposes, if you transfer life insurance within three years of passing, the policy's value can still affect your estate’s tax calculation. This rule can catch individuals off guard, as it impacts how inheritances are valued. When planning to cover debts like a mortgage, incorporating a life insurance trust with for mortgage can help mitigate these potential tax impacts. Understanding this rule empowers you to make informed decisions in trust creation.
Yes, a life insurance trust may need to file a tax return depending on its income. If the trust generates income that exceeds a specific threshold, it must report that income to the IRS. This requirement arises because the trust is regarded as a separate legal entity. If you are considering a life insurance trust with for mortgage, consulting with a tax professional can provide clarity on your tax obligations.
The 3-year rule for life insurance relates to how the IRS manages gift taxes. If you transfer a life insurance policy to another entity or person and die within three years, the policy’s value may be included in your estate for tax calculations. This can result in unexpected tax liabilities for your heirs. A life insurance trust with for mortgage provisions can help you manage these risks better.
The 3-year rule for an irrevocable trust indicates that any assets transferred into the trust cannot be removed for a period of three years. This is crucial for estate tax purposes, as the IRS looks back at these transfers. If the policyholder passes away within this time frame, the value of the life insurance may still be considered part of their estate. Using a life insurance trust with for mortgage strategies allows for better financial management while navigating these regulations.
Naming a trust as the beneficiary of a life insurance policy can complicate the distribution process. If not properly set up, the trust may face delays in accessing the funds. Furthermore, legal fees and administrative costs might increase, impacting the financial support intended for your beneficiaries. The key benefit of using a life insurance trust with for mortgage is to ensure that your loved ones can cover obligations, but careful planning is essential.
Putting your mortgage in a trust can offer several advantages. With a life insurance trust with for mortgage, you can protect your home and ensure that your beneficiaries receive clear ownership. This approach can also aid in managing your estate, making the transition smoother for your heirs. Moreover, a legal platform like US Legal Forms can guide you in creating the necessary documentation to establish a trust effectively.
Using a life insurance trust with for mortgage can be beneficial. It can help manage how the policy pays out, ensuring that funds are available to cover mortgage payments upon your passing. Additionally, the trust can provide estate tax benefits, making sure your loved ones receive more financial support. By keeping the life insurance separate from your estate, you also prevent creditors from accessing these funds.