Engagement Letter In Auditing In Salt Lake
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
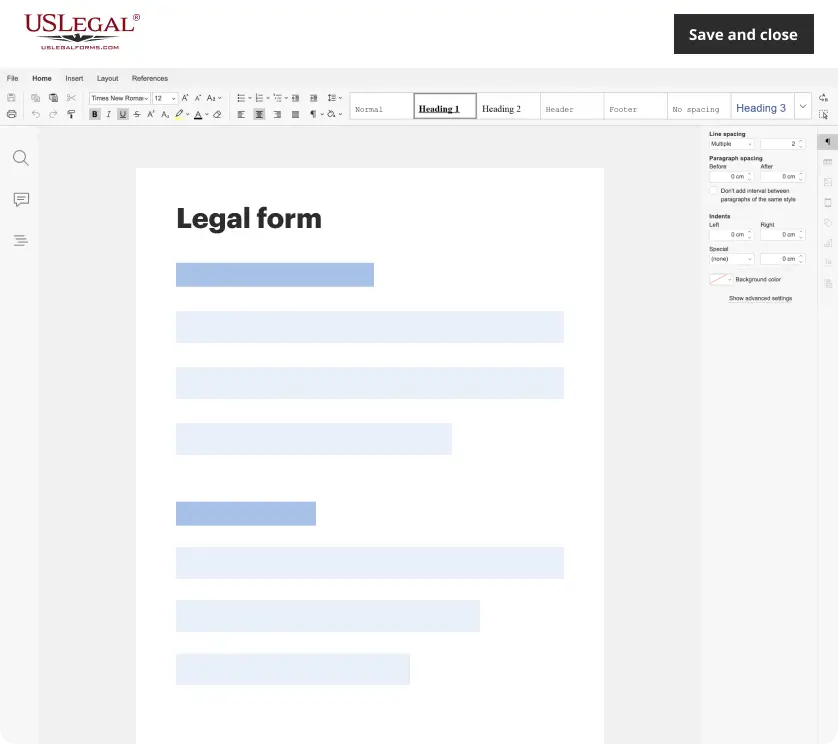
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
An audit engagement is an agreement between a client and an independent third-party auditor to perform an audit of some element of the client's business, such as accounting records, financial statements, internal controls, regulatory compliance, information systems, operational processes, etc.
Although every audit is unique, the audit process usually consists of four stages: Planning, Field work, Reporting and (for some audits) Follow-up. Engagement of the client, or the area being audited, is critical at every stage of the audit process.
It is in the interests of both the entity and the auditor that the auditor sends an audit engagement letter before the commencement of the audit to help avoid misunderstandings with respect to the audit.
An audit engagement is an arrangement that an auditor has with a client to perform an audit of the client's accounting records and financial statements. The term usually applies to the contractual arrangement between the two parties, rather than the full set of auditing tasks that the auditor will perform.
The scope of a review engagement is narrower and less intrusive compared to an audit. Procedures primarily include: Inquiry: Asking management and staff about the financial statements and related matters. Analytical Procedures: Applying analytical techniques to identify unusual trends or variances in financial data.
This Revised Standard on Auditing (SA 210) deals with the auditor's responsibilities in agreeing to the terms of the audit engagement with management. SA 210 establishes the preconditions for an audit, terms of an audit engagement and changes thereof, segregates the responsibility of the management and auditors etc.
Forming Engagement Objectives These should articulate what the engagement is specifically attempting to accomplish; therefore, the objectives should have a clear purpose, be concise, and be linked to the risk assessment (Standard 2210. A1).
When should the engagement letter be sent and signed? The audit engagement letter should be sent after verbal confirmation of the appointment of you as the auditor and ideally signed before the start of any audit work.
An audit engagement letter is one of the most crucial initial items in the entire audit process reflecting the general terms, responsibilities and the scope of the audit service by the auditor and his or her client. Learn about official guidelines, standards and key elements.
The AICPA requires the issuance of a management letter, to those charged with governance, in the event material weaknesses or significant deficiencies are identified.