New York State Deferred Compensation Plan Terms Of Withdrawal In Pennsylvania
Description
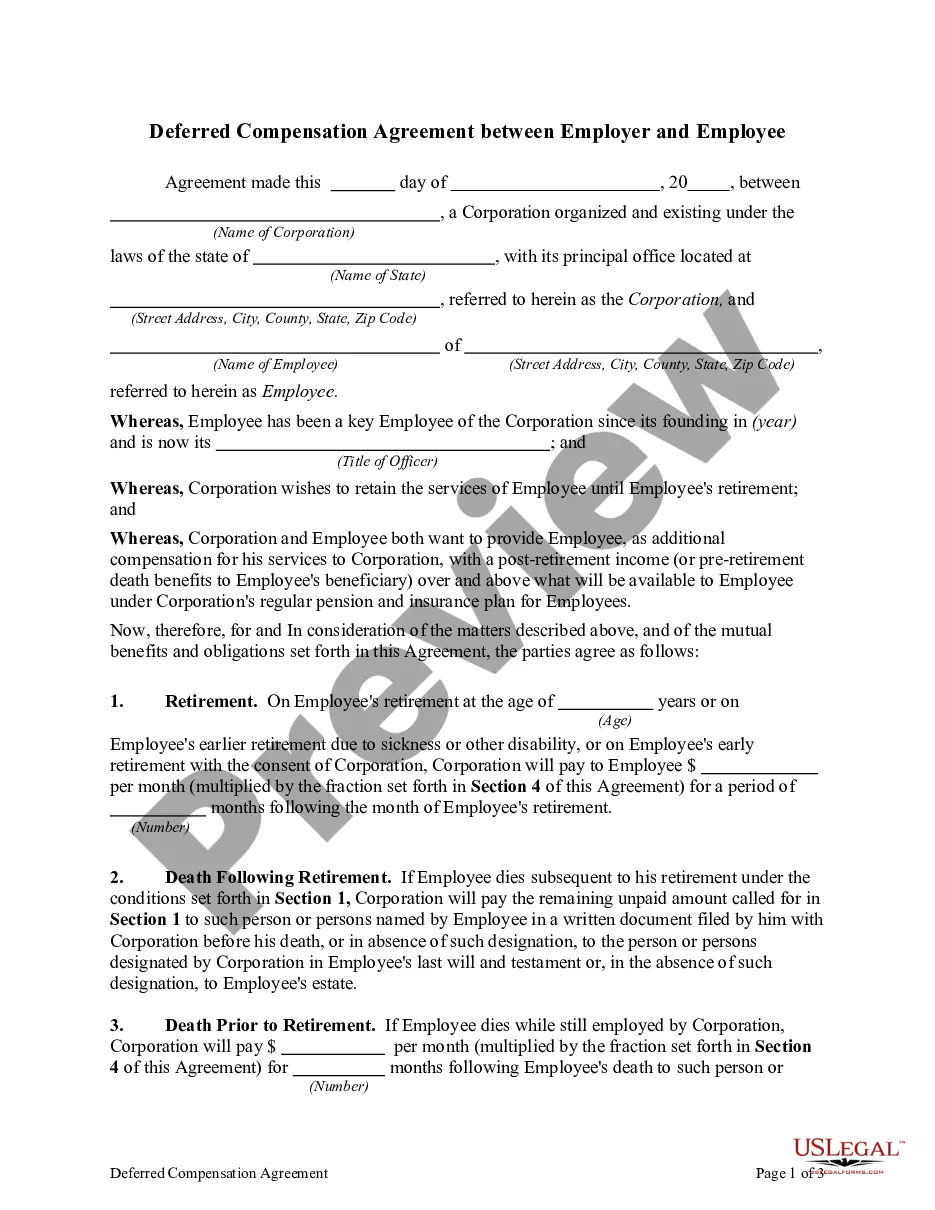
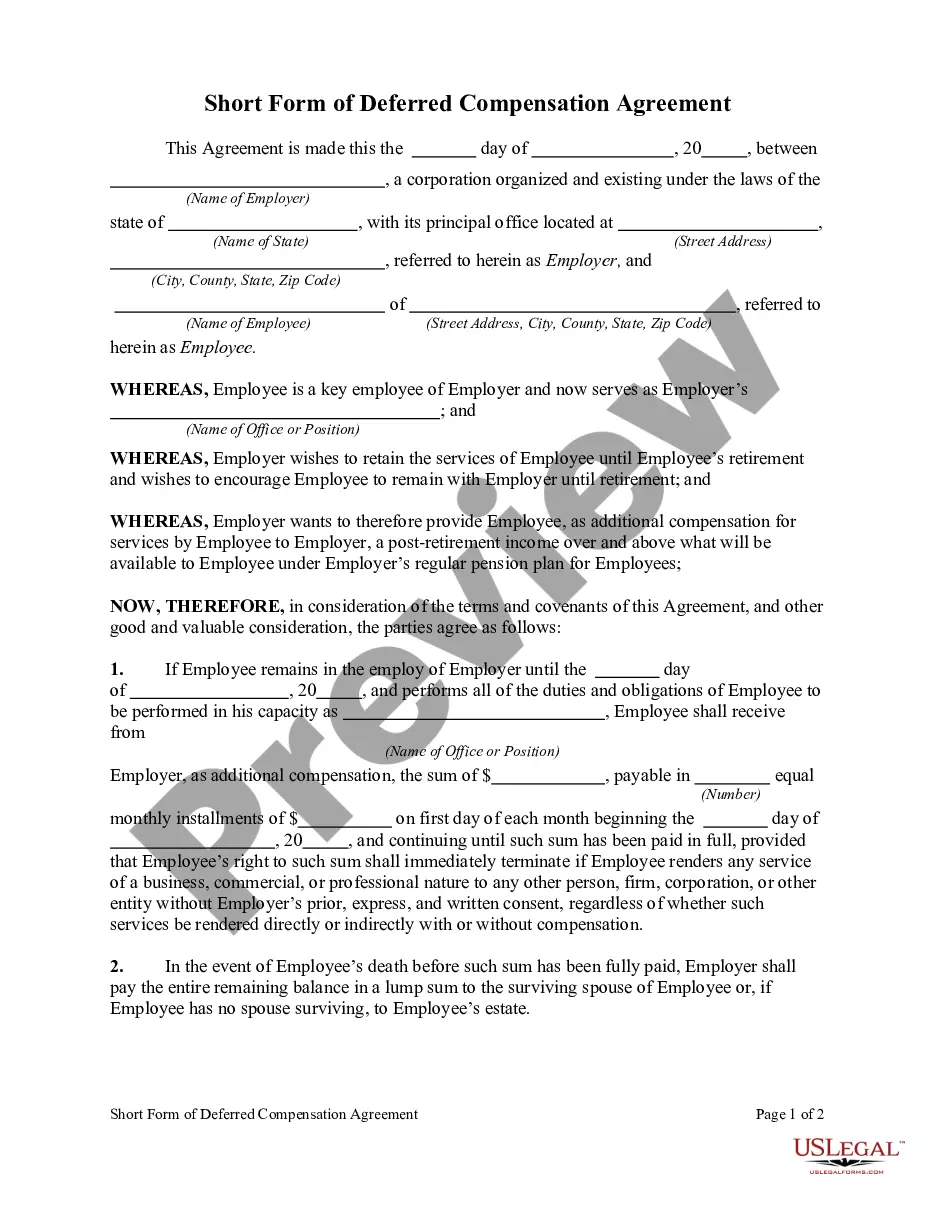
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?


Form popularity
FAQ
About Your Deferred Compensation Plan. Your "deferred comp plan" offers a simple, flexible way for you to save for retirement. With its powerful pretax savings features, investment options and planning resources, you can work toward replacing your working income in retirement — for life.
You can't borrow from an IRA, and early withdrawals could incur taxes and penalties.
The Plan differs from other defined contribution retirement plans (like a 401(k) or 403(b)), because it is designed and managed with public employees in mind. The New York State Deferred Compensation Board establishes and administers the Plan policies.
Dipping into a 401(k) or 403(b) before age 59 ½ usually results in a 10% penalty.
You may keep your contributions in the Plan and continue to build savings for retirement. However, you may withdraw your contributions if you: Have a Plan account balance of less than $5,000, exclusive of any assets you may have in a rollover account, AND. Have not contributed to the Plan in the last two years, AND.
Upon severance from City service, or upon reaching age 59½, participants can begin receiving distributions at any time by either accessing their account online or submitting a Distribution Form to the Plan's Administrative Office. Participants can change or stop distributions at any time.
Distribution of earnings from the Roth 457 and 401(k) Plan before age 59½ or for a period shorter than five taxable years are subject to all applicable income taxes (Roth 401(k) distribution is also subject to penalties).
