Decedent Account Bank For Union In Pennsylvania
Description
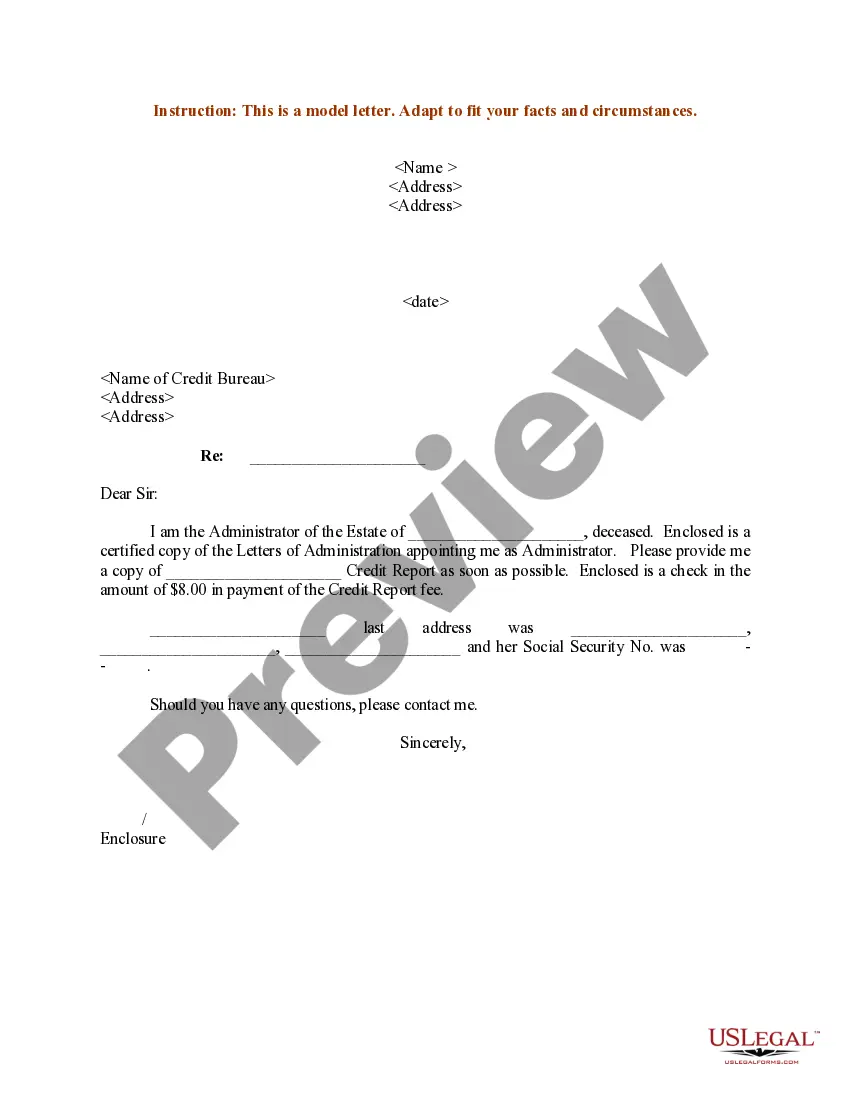
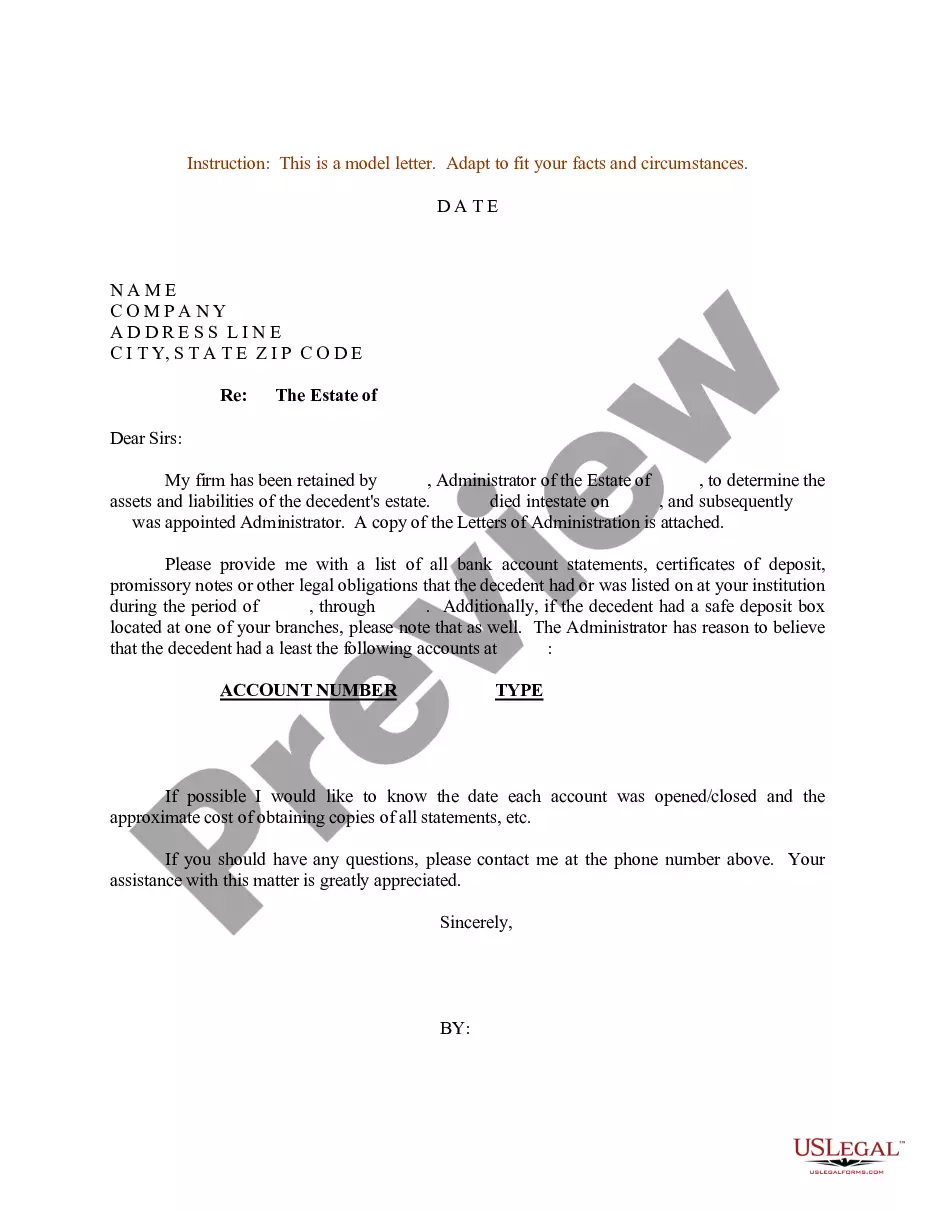
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?



Form popularity
FAQ
Joint accounts You can set up a bank account with anyone you want, including your spouse, a family member or another friend. If the account has a “joint with rights of survivorship,” or JWROS, clause, then upon your death, the bank will transfer all the funds in there to them.
Joint owners or beneficiaries of the deceased person's account can work with the bank directly to access the funds. If the account becomes part of the owner's estate, the legally designated executor can collect the funds and place them into an estate account.
Jointly Owned Assets When one co-owner dies, the surviving co-owner or co-owners automatically inherit the deceased co-owner's share of the asset, without the need for probate. Examples of jointly owned property include: Joint bank accounts.
In a jointly owned account, when two people have equal access and one dies, the survivor is taxed on one half of the amount (50%) in the account.
Property owned jointly between husband and wife is exempt from inheritance tax, while property inherited from a spouse, or from a child aged 21 or younger by a parent, is taxed a rate of 0%. Inheritance tax returns are due nine calendar months after a person's death.
Jointly owned property with right of survivorship, except between husband and wife, including but not limited to real estate, securities, bank accounts, etc., is taxable to the extent of the decedent's fractional interest in the joint property (calculated by dividing the value of the joint property by the number of ...
If the account becomes part of the owner's estate, the legally designated executor can collect the funds and place them into an estate account. The joint owner, beneficiary or executor must provide a copy of the death certificate when taking action on the owner's account.
Ans: - Depending on the amount of claim, the following documents need to be submitted. i) Photocopy of Death Certificate (original to be produced for verification by the bank). ii) Photographs and KYC documents of all the claimants/ legal heir(s), (Original documents to be produced for verification by the bank.)
DOCUMENTS REQUIRED: As a matter of general rule following documents are required in all cases of death claim: i. Death Certificate. ii. Application for Deceased claim(Annexure I) /Estate claim form (Annexure II) duly filled in by the legal heirs/claimants.
They generally will need to present to the bank with a certified copy of the decedent's death certificate, their own government-issued ID, and the trust instrument (or a certification of trust) in order for the asset to be released to them, although the documentation needed can vary from bank to bank, so it is best to ...