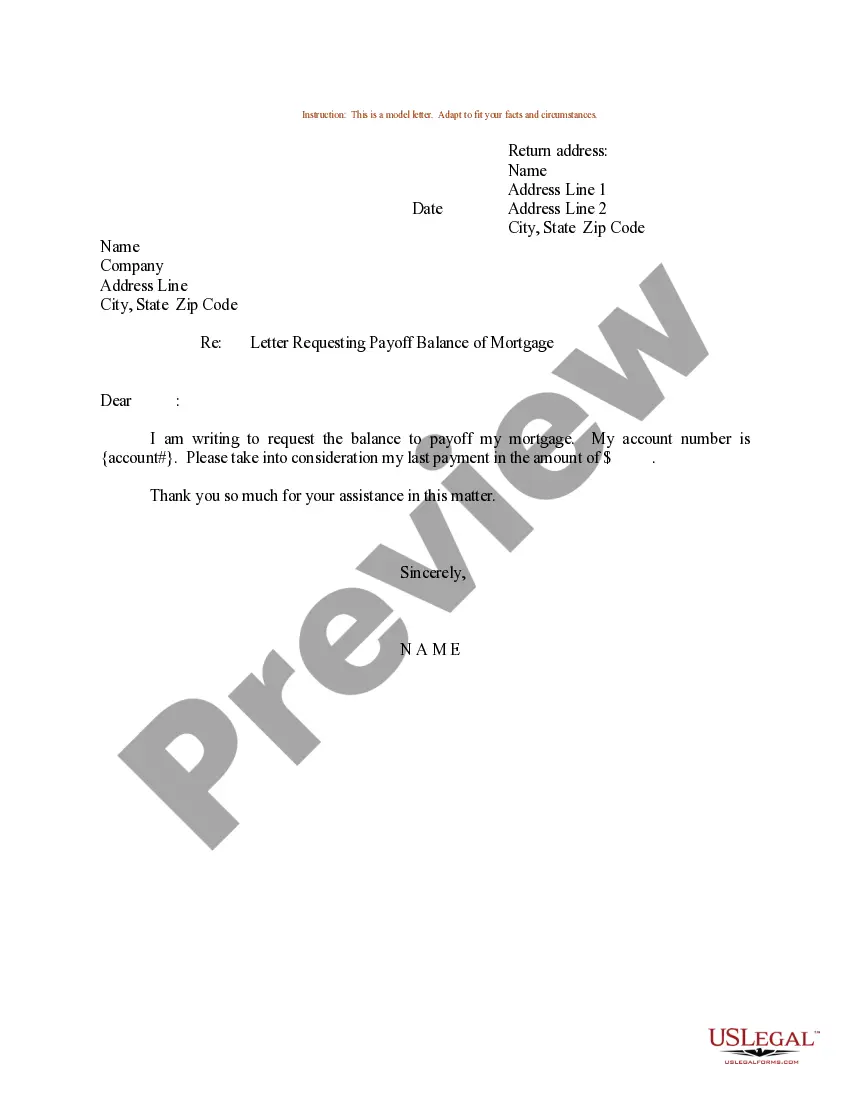
Loan Payoff Letter Example With Credit Card In Salt Lake
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
You'll want to include specific information concerning your account in your debt settlement letter. List your name, account information, the original creditor of the debt, and the debt collection agencies identifying information. Include the current amount you owe and the amount you'd like to offer to settle the debt.
Treat the following as a set of general guidelines: Gather complete information before you start writing. Describe your injuries and medical treatment. List your medical expenses, lost wages, and non-economic damages. Make a settlement demand. Include a deadline for legal action if you want to, but don't bluff.
5 Steps to Negotiate Credit Card Debt Settlement Confirm the Amount You Owe. First, double-check the amount of the debt you want to negotiate a settlement for. Calculate How Much You Can Repay. Get Help From a Professional. Contact Your Creditor. Agree to a Debt Settlement Plan.
A Payoff Letter memorializes a debtor and lender's agreement regarding a debt obligation's early payment and termination. Typically, upon satisfaction of its terms, the Payoff Letter terminates the underlying debt instrument and releases the debtor from most continuing obligations.
First, you'll need to contact your lender and let them know you want the information. Depending on your lender, you may have to sign in to an online account, call a helpline, or send a formal letter to start the request process.
Generally, writing off some or all of your credit card debt is done through a debt solution. There are multiple debt solutions that can allow you to write credit card debt off, including: Individual Voluntary Arrangement (IVA) Debt Relief Order (DRO)
Should the challenges and missed payments continue longer term, the credit card debt could ultimately be written off, which is when a creditor considers it uncollectible and no longer counts it as an asset — typically after 180 days of non-payment. For cardholders, the situation can feel confusing.
Yes, it is possible to have credit card debt forgiven, although it is not a common occurrence. Credit card debt can be forgiven through a variety of methods, including debt settlement negotiations with the lender, debt management programs, and in some cases, bankruptcy.
Which debt solutions write off debts? Bankruptcy: Writes off unsecured debts if you cannot repay them. Any assets like a house or car may be sold. Debt relief order (DRO): Writes off debts if you have a relatively low level of debt. Must also have few assets. Individual voluntary arrangement (IVA): A formal agreement.
To get a payoff letter, ask your lender for an official payoff statement. Call or write to customer service or make the request online.
